
Toast (TOST) Launches Toast Fuel As Investors Ask If The Growth Story Is Priced In
Toast Fuel pushes Toast into adjacent markets
Toast (TOST) has launched Toast Fuel, a fuel and convenience store platform that brings forecourt payments, in store retail, and foodservice operations onto a single cloud based system.
The move takes Toast beyond restaurants into adjacent fuel and convenience operators by using its point of sale, workflow tools, and Toast IQ analytics to manage pumps, EMV payments, in store orders, and loyalty programs together.
Toast shares trade at US$29.79, with a 30 day share price return down about 12% even though the 90 day move is slightly positive. That pullback sits against a 1 year total shareholder return down about 19% but a much stronger 3 year total shareholder return of about 73%, so momentum has cooled recently as investors weigh new products like Toast Fuel alongside leadership changes and fresh partnerships in voice AI.
Scan beyond Toast to see how other payments and retail tech players are positioning for similar shifts with our hand picked 90 AI infrastructure stocks.
Toast now sits at an awkward crossroads where product momentum and AI partnerships point one way, while a cooling share price points another. Does the recent slide reflect business reality, or just sentiment fatigue before valuation work begins?
Most Popular Narrative: 36% Undervalued
Toast trades at $29.79 while the most followed narrative, according to PDSOUSA, anchors fair value around $46.44. The gap between price and that estimate is wide enough to focus attention on what is driving the story rather than short term share moves.
Meaning (Business Model) A cloud-based vertical ecosystem built specifically for the restaurant and hospitality sector. Unifies POS hardware/software, supply chain management, integrated payments, marketing, and kitchen management. Has successfully pivoted from heavy growth investments toward accelerated net profitability.
See why 2 investors see Toast as 36% undervalued.
The narrative from PDSOUSA leans heavily on three pillars. First, a vertically focused platform that ties together Toast POS, Toast IQ, payments, and back office tools into one operating system for hospitality clients. Second, high switching costs and payment network effects that can help keep customers on the platform once embedded. Third, a balance sheet with more than $1.9b in net cash and no significant long term borrowings, which gives Toast room to fund products like Toast Fuel without relying on new debt.
Those fundamentals sit alongside profitability and growth expectations that are already in the data. Earnings moved from losses to profits over the last five years, with earnings growth reported at 63.5% per year over that span and 117% over the past year. Forecasts in the statements point to earnings growth of about 24.5% per year and revenue growth of 15.8% per year, both ahead of the broader US market estimates shared, even though revenue growth is described as slower than 20% per year.
At the same time, the valuation work in the narrative is not relying only on comparables. The fair value estimate of $46.44 implies a discount to fair value of 35.9%, while the separate DCF based statement pegs future cash flow value at $40.40, with Toast trading 26.3% below that figure. Analysts are also grouped around a price target of $38.92, which is about 30.7% above the current quote and flagged as being within a statistically confident range of agreement.
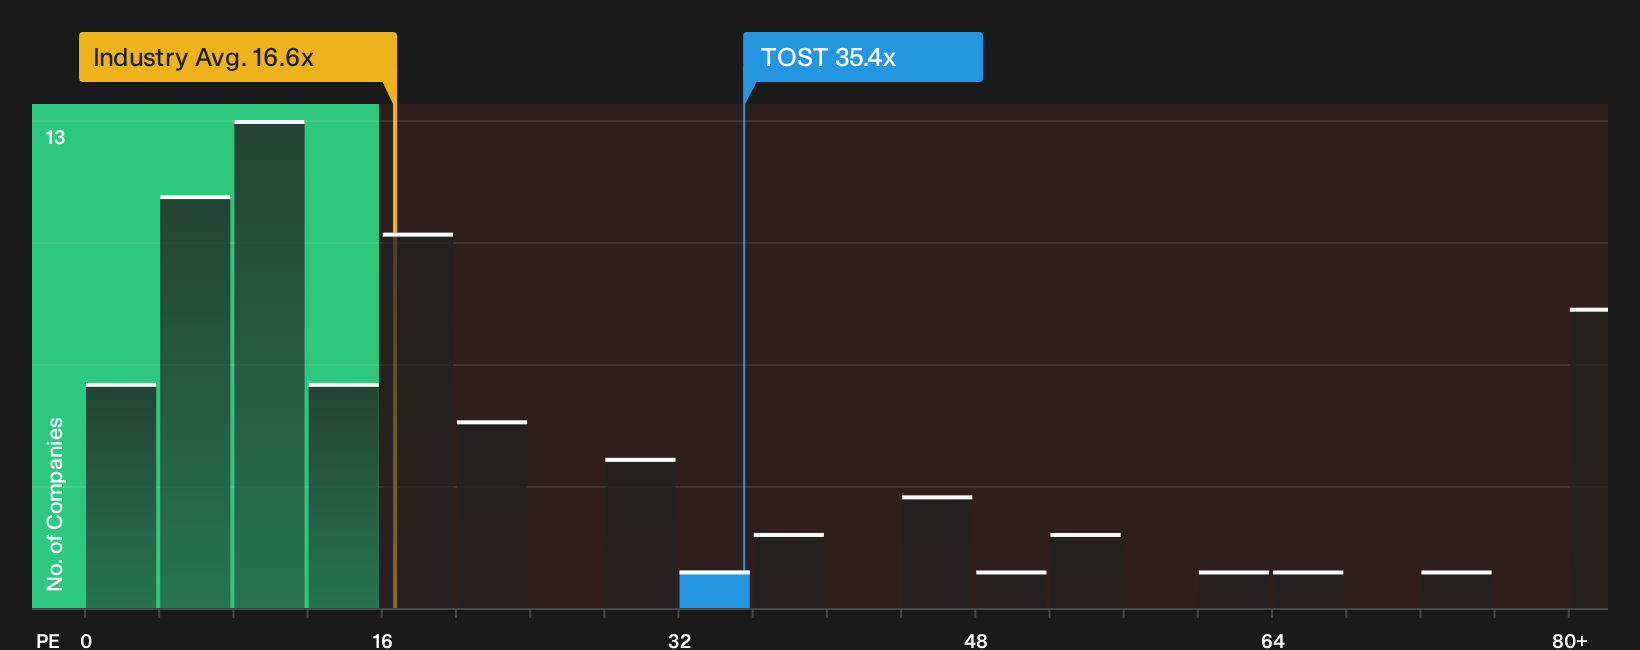
Yet the shares are not framed as cheap on every metric in the material provided. The statements and narrative both acknowledge a P/E around 35.4x to 35.5x, which is higher than peer averages around 15.9x and the US Diversified Financial industry average of 16.6x, as well as above an estimated fair P/E of 19.3x. The P/B ratio of about 9.5x also sits ahead of sector ranges cited around 4.2x to 5.0x. That mix suggests the narrative fair value rests on earnings quality, high return on equity of 23.8%, and projected profit expansion rather than on low headline multiples.
For investors weighing Toast Fuel and other product expansions, the takeaway is a split picture. Price and recent returns reflect a pullback, while the most followed narrative and supporting statements frame Toast as trading below both intrinsic value estimates and analyst targets, with high profitability metrics and strong cash backing that need to be weighed against richer P/E and P/B multiples.
Result: Fair Value of $46.44 (UNDERVALUED)
Still, Toast faces pressure if restaurant clients resist further price increases or new modules, and if future earnings progress falls short of the premium P/E and P/B already in place.
Find out about the key risks to this Toast narrative.
Another View on Toast Using Earnings Multiples
There is a different read when you look at Toast through its earnings ratio. The stock trades on a P/E of 35.4x, while the peer group sits closer to 15.9x and the fair ratio points to 19.3x. That gap suggests investors are paying a premium that only strong execution can justify. Is that premium a cushion for you, or does it represent compression risk?
See what the numbers say about this price in more detail with our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Toast has been mixed so far, so move quickly from reading to testing the story against the underlying numbers yourself. To see what optimistic investors are focusing on, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond Toast?
If Toast has sharpened your thinking, do not stop here. Broader context from other opportunities can help you judge whether this story truly earns a spot in your portfolio.
- Start with potential mispricings by scanning the 31 high quality undervalued stocks that pair robust fundamentals with what could be discounted valuations.
- Strengthen your income watchlist by reviewing the 7 dividend fortresses that focus on higher yielding payouts with supporting cash flows.
- Dial down potential volatility by examining the 31 resilient stocks with low risk scores that filter for companies with more resilient risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com