
OPKO Health (OPK) Sharpens Its Focus, Is It Still A Bargain?
OPKO Health (OPK) has been drawing attention after recent trading moves around its US$1.56 share price, with investors weighing its mixed return profile over the past year against longer term performance trends.
For context, OPKO Health’s recent pullback, with a 7 day share price return of down 4.29% and a 30 day share price return of down 4.88% from US$1.56, comes after a stronger 90 day share price return of 4.70% and year to date share price return of 22.83%. The 1 year total shareholder return is down 1.27% and the 5 year total shareholder return is down 58.40%, indicating that momentum has improved in the short term but remains weak over a longer horizon.
Compare OPKO Health’s recent rebound with a curated set of other healthcare names showing stronger momentum and balance sheet support via the list of solid balance sheet and fundamentals (25 results).
Given OPKO Health’s sharp long term drawdown and more recent uptick, the live question is whether most of the easy upside has already played out or whether valuation still leaves meaningful room ahead.
Most Popular Narrative: 64% Undervalued
Against OPKO Health’s last close of $1.56, the most followed valuation narrative points to a fair value of $4.38, which frames the recent share price weakness as a discount rather than a peak.
The sale of BioReference's oncology and related clinical testing assets to Labcorp is expected to sharpen OPKO Health's focus on its core testing business, drive significant cost savings, and support the Diagnostics segment's transition to cash flow positive and profitability in 2025, providing margin expansion and stabilizing earnings. FDA approval expanding the indication for the 4Kscore prostate cancer risk test (removing the requirement for digital rectal exam input) significantly broadens its addressable market especially among primary care providers supporting continued test volume growth and higher-margin revenues for the Diagnostics business.
See why 15 investors see OPKO Health as 64% undervalued.
This framework applies a 7.33% discount rate and assumes OPKO Health can grow revenue by around 2% a year while lifting profit margins toward 6.1%, which is in line with the wider US healthcare sector used as a reference point in the narrative.
Those same assumptions feed through to a future P/E of roughly 92.8x on the projected $37.8 million of earnings by around 2029, a multiple that is much higher than the 26.0x industry level cited in the narrative and signals how much earnings power the market would need to price in for the thesis to hold.
The gap between the $1.56 trading price and the $4.38 narrative fair value therefore hinges on whether investors think OPKO Health can move from current losses of $72.9 million toward those margin and earnings targets while absorbing the risks around competition, funding, and execution that the narrative flags.
Result: Fair Value of $4.38 (UNDERVALUED)
Still, OPKO Health’s ongoing net loss of US$72.89 million and reliance on a narrow set of key products and partnerships could quickly weaken that undervaluation story.
Find out about the key risks to this OPKO Health narrative.
Another View: OPKO Health Looks Expensive On Sales
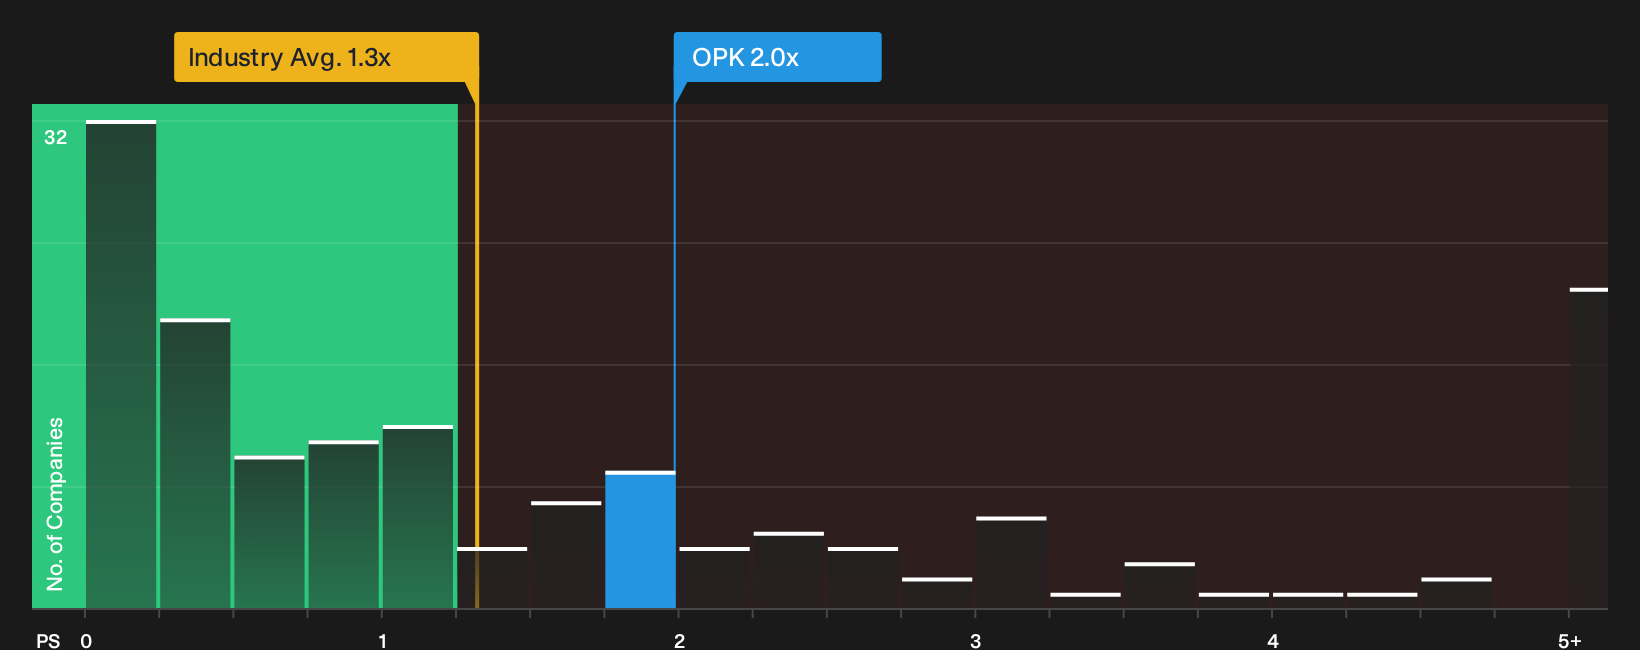
The story shifts once you stop looking at fair value models and focus on what the market is already paying for OPKO Health’s revenue. On a P/S of roughly 2x, the stock trades richer than the US healthcare sector at 1.3x and above close peers at 1.7x, while the fair ratio sits even lower at 0.5x.
That gap suggests investors are already accepting a premium price for each dollar of OPKO Health’s sales, even though the business is still loss making. This raises a simple question for anyone considering the shares: What would need to change in the actual financials to justify that premium staying in place over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of upside potential and clear hurdles around OPKO Health leaves you on the fence, move quickly from headline impressions to the underlying figures and risk flags. For a sharper view of what could go wrong before you commit fresh capital, start with these 3 important warning signs.
Looking for more investment ideas beyond OPKO Health?
If OPKO Health has your attention, do not stop here. Fresh ideas often come from comparing it with other stocks that show different strengths and risk profiles.
- Target value opportunities by scanning a curated set of 31 high quality undervalued stocks that pair solid fundamentals with prices that still look restrained.
- Prioritize resilience by reviewing 31 resilient stocks with low risk scores that focus on steadier balance sheets and more measured risk scores when markets turn choppy.
- Hunt for future standouts by checking 19 high quality undiscovered gems before the wider market pays attention and potential upside becomes crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com