
European Insider-Favored Growth Stocks To Watch
European markets have recently experienced volatility, driven by rising oil prices and sovereign bond yields, which have affected investor sentiment. Amid these conditions, growth companies with high insider ownership can be particularly appealing as they often indicate strong confidence from those within the company.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 60.3% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Envipco Holding (ENXTAM:ENVI) | 15.2% | 99% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
Here's a peek at a few of the choices from the screener.
Envipco Holding (ENXTAM:ENVI)
Simply Wall St Growth Rating: ★★★★★★
Overview: Envipco Holding N.V. develops, manufactures, assembles, leases, sells, markets, and services reverse vending machines (RVMs) in North America and Europe with a market cap of €237.26 million.
Operations: Envipco Holding N.V.'s revenue primarily comes from its operations involving the development, manufacturing, assembly, leasing, sales, marketing, and servicing of reverse vending machines in North America and Europe.
Insider Ownership: 15.2%
Envipco Holding is positioned for significant growth, with expected annual revenue growth of 30.4%, surpassing the Dutch market average. Despite recent losses, it is forecast to become profitable within three years and achieve a high return on equity of 29.5%. The company has secured substantial contracts in the UK and Romania for reverse vending machines, which could enhance its market presence as the UK's Deposit Return Scheme rolls out in 2027. However, its share price remains highly volatile.
- Take a closer look at Envipco Holding's potential here in our earnings growth report.
- Upon reviewing our latest valuation report, Envipco Holding's share price might be too pessimistic.
Bohus (OB:BOHUS)
Simply Wall St Growth Rating: ★★★★★☆
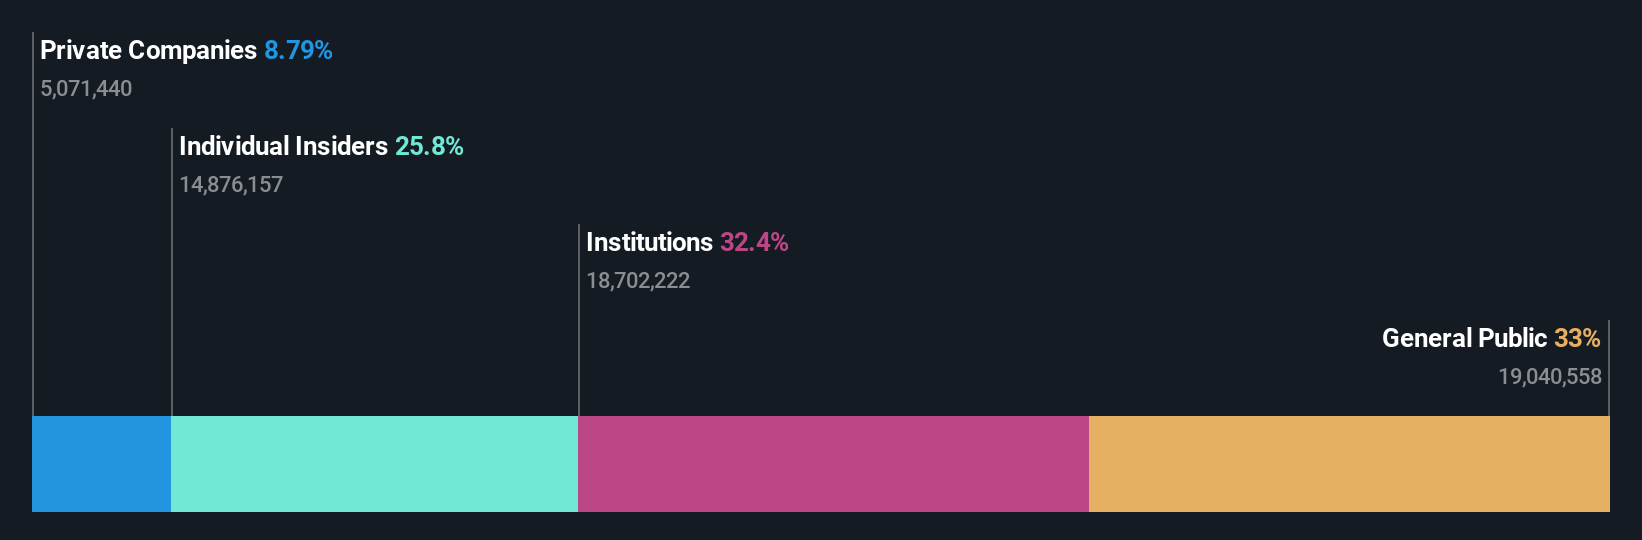
Overview: Bohus ASA operates a mid-market furniture retail chain in Norway and has a market capitalization of NOK3.71 billion.
Operations: The company's revenue primarily comes from its retail segment in home furnishing, amounting to NOK3.76 billion.
Insider Ownership: 31.8%
Bohus ASA demonstrates strong growth potential with earnings expected to grow significantly at 35.4% annually, outpacing the Norwegian market. Recent results show substantial profit increases, with net income rising to NOK 71.4 million in Q2 2026 from NOK 6.6 million a year earlier, and revenue reaching NOK 963.8 million. The stock trades at a notable discount of 36.9% below estimated fair value, though insider trading activity remains unreported over the past three months.
- Click to explore a detailed breakdown of our findings in Bohus' earnings growth report.
- Our valuation report unveils the possibility Bohus' shares may be trading at a discount.

Medistim (OB:MEDI)
Simply Wall St Growth Rating: ★★★★☆☆
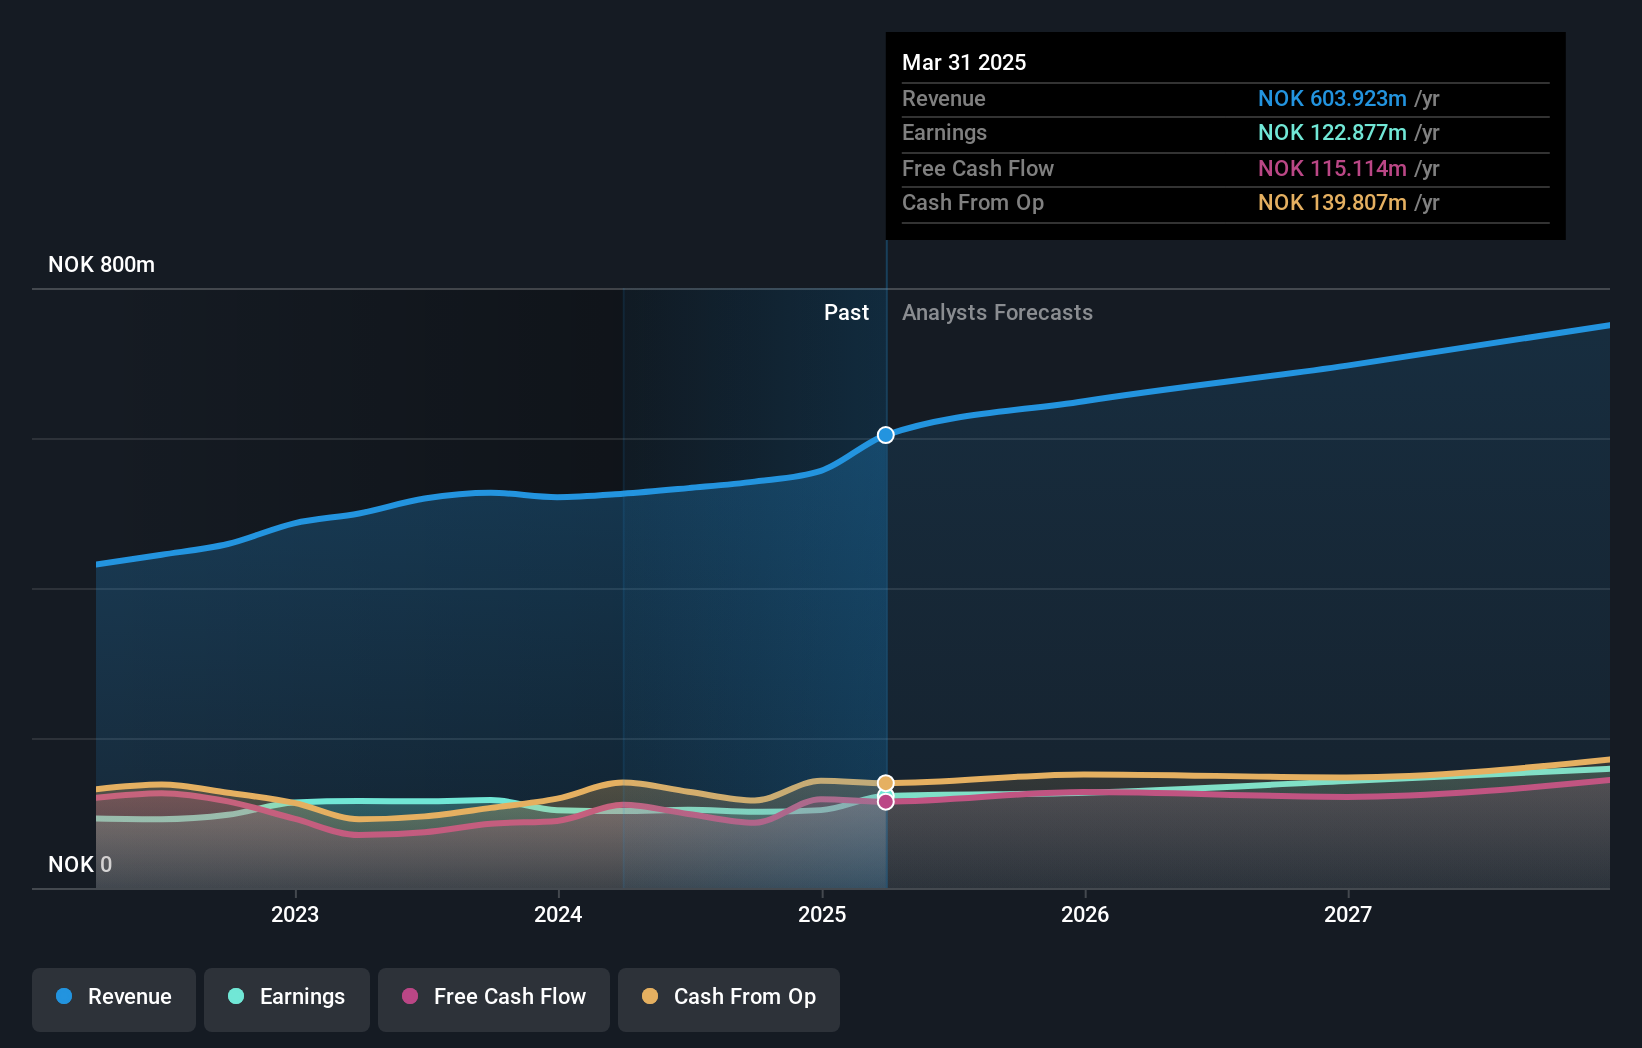
Overview: Medistim ASA is a company that focuses on developing, producing, servicing, leasing, and distributing medical devices for cardiac and vascular surgery across the United States, Asia, Europe, and other international markets; it has a market cap of NOK4.57 billion.
Operations: The company's revenue segments consist of NOK662.92 million from its own products and NOK89.92 million from third-party products.
Insider Ownership: 18.2%
Medistim shows promising growth with earnings projected to increase by 11.8% annually, outpacing the Norwegian market. Recent Q2 results highlight a revenue rise to NOK 202.03 million from NOK 169.08 million year-over-year, and net income increased to NOK 52.2 million from NOK 42.98 million. Trading at a discount of 17.1% below estimated fair value, Medistim benefits from high insider ownership without recent substantial insider trading activity reported over three months.
- Click here to discover the nuances of Medistim with our detailed analytical future growth report.
- Upon reviewing our latest valuation report, Medistim's share price might be too optimistic.
Where To Now?
- Unlock more gems! Our Fast Growing European Companies With High Insider Ownership screener has unearthed 193 more companies for you to explore.Click here to unveil our expertly curated list of 196 Fast Growing European Companies With High Insider Ownership.
- Want To Explore Some Alternatives? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com