
Exploring Three Undiscovered Gems in Asia's Stock Market
As global markets grapple with mixed signals from economic indicators and fluctuating indices, Asia's stock market presents a unique landscape where small-cap stocks are gaining attention amid broader market volatility. In this dynamic environment, identifying promising stocks requires a keen eye for potential growth opportunities and resilience in the face of economic shifts.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
Here's a peek at a few of the choices from the screener.
Huishang Bank (SEHK:3698)
Simply Wall St Value Rating: ★★★★★★
Overview: Huishang Bank Corporation Limited, along with its subsidiaries, offers a range of commercial banking products and services in Anhui, Jiangsu, and internationally, with a market cap of HK$64.24 billion.
Operations: The bank generates revenue primarily through its Corporate Banking segment, contributing CN¥16.57 billion, followed by Treasury at CN¥10.03 billion and Personal Banking at CN¥4.42 billion.
Huishang Bank, with total assets of CN¥2,490.2 billion and equity of CN¥179.5 billion, stands out for its robust financial health in the banking sector. Total deposits amount to CN¥1,486.8 billion against loans of CN¥1,251.2 billion, indicating a solid deposit base that comprises 64% low-risk funding sources like customer deposits. The bank's allowance for bad loans is commendably low at 0.1%, showcasing prudent risk management practices in place despite earnings growth over the past year (6.4%) not matching the industry average of 8%. Trading at a significant discount to its estimated fair value enhances its appeal among peers and industry players alike.

OKP Holdings (SGX:5CF)
Simply Wall St Value Rating: ★★★★★★
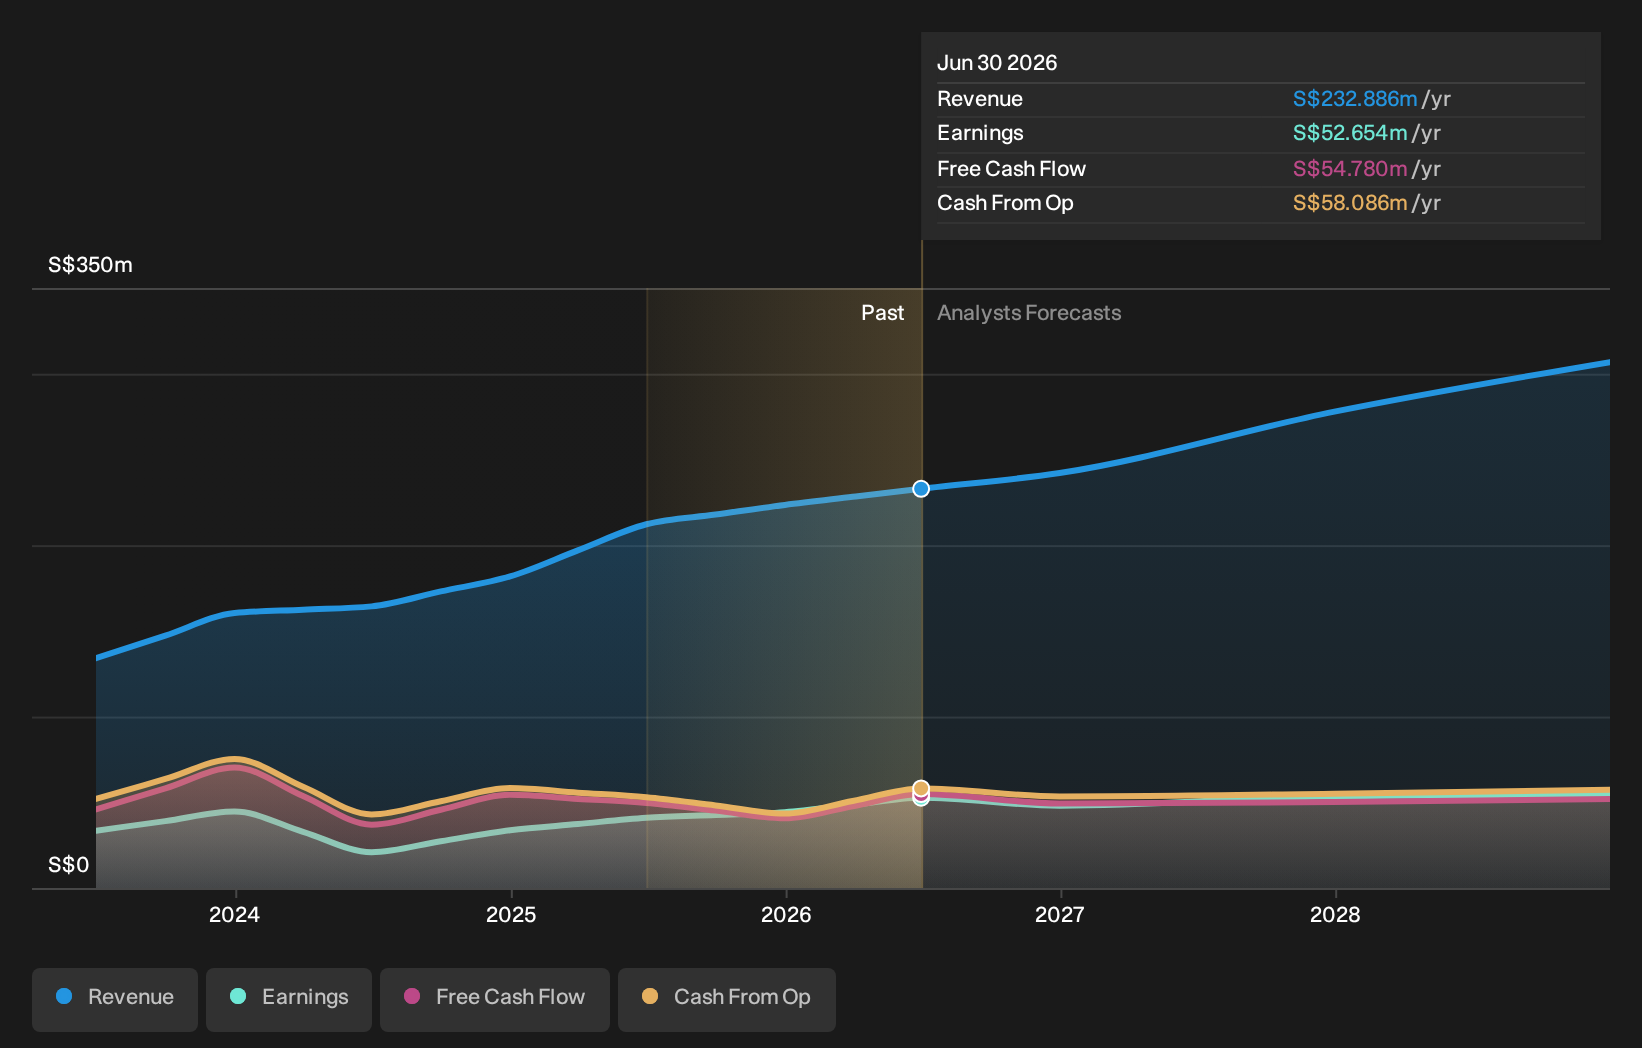
Overview: OKP Holdings Limited operates as a transport infrastructure and civil engineering company in Singapore and Australia, with a market capitalization of SGD370.66 million.
Operations: The company generates revenue primarily from construction (SGD163.64 million) and maintenance (SGD68.87 million) services, with additional income from rental activities (SGD2.65 million).
OKP Holdings, a nimble player in the construction sector, has been making strides with a recent SGD 90.6 million contract from the Land Transport Authority for road enhancements. Their net income for the first half of 2026 hit SGD 27.53 million, up from SGD 19.13 million last year, showcasing robust growth. The company is trading at an attractive value, sitting at 56% below its estimated fair value and boasts high-quality earnings with a debt-to-equity ratio reduced to 8.5% over five years. With an order book worth SGD 797.9 million extending till 2031, OKP seems well-positioned for future projects and expansion opportunities in infrastructure development across Singapore's dynamic landscape.
- Navigate through the intricacies of OKP Holdings with our comprehensive health report here.
Evaluate OKP Holdings' historical performance by accessing our past performance report.
Zhongtong Bus HoldingLTD (SZSE:000957)
Simply Wall St Value Rating: ★★★★★★
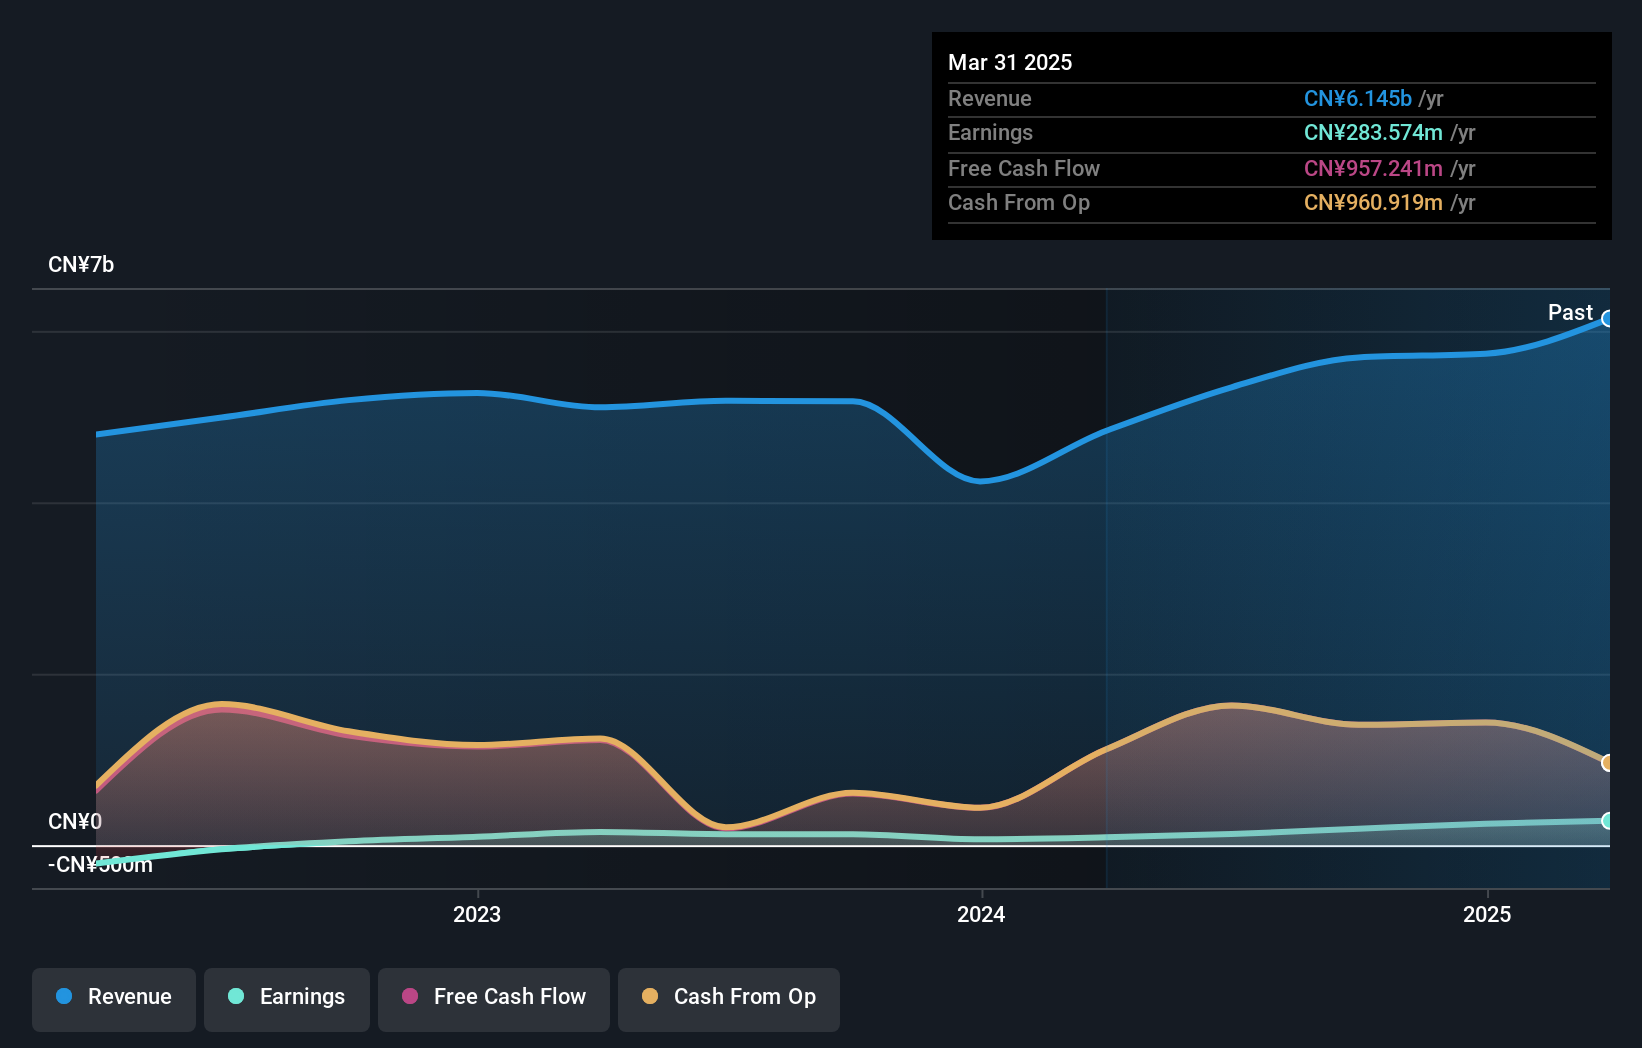
Overview: Zhongtong Bus Holding Co., LTD is involved in the manufacture and sale of buses in China, with a market capitalization of approximately CN¥5.75 billion.
Operations: Zhongtong Bus Holding Co., LTD generates revenue primarily through its bus manufacturing segment, which recorded CN¥7.40 billion. The company's financial performance includes a focus on optimizing production costs to enhance profitability.
Zhongtong Bus Holding Co., a relatively small player in the bus manufacturing sector, has recently showcased impressive financial metrics. Its debt to equity ratio has significantly decreased from 81.5% to 2.7% over five years, reflecting improved financial health. The company reported net income of CN¥282.73 million for the half-year ending June 2026, up from CN¥190.39 million a year earlier, indicating robust earnings growth of 37.4%. Trading at 93% below its estimated fair value and with positive free cash flow, Zhongtong appears undervalued compared to industry peers while maintaining profitability despite one-off gains impacting recent results.
- Click here and access our complete health analysis report to understand the dynamics of Zhongtong Bus HoldingLTD.
Gain insights into Zhongtong Bus HoldingLTD's past trends and performance with our Past report.
Next Steps
- Get an in-depth perspective on all 116 Asian Undiscovered Gems With Strong Fundamentals by using our screener here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com