
AI Memory Stocks to Watch Beyond Micron Stock
Micron’s blowout quarter, with revenue jumping by about $43b year over year and operating margins above 80% in some lines, has refocused attention on who supplies the tools, materials, and services behind that AI memory surge. Investors watching tight supply, strong pricing, and a single digit forward P/E on Micron may see more than one way to consider this story. This article walks through three stocks exposed to that same earnings shock and explains how each could either sharpen or dull your portfolio’s exposure to the AI memory build out.
The three stocks below are just a starting sample. The full screen surfaced 62 more companies with equally detailed business stories that also touch the AI memory supply chain but are not covered here.
To go straight to the broader opportunity set, analyze, compare, and identify your highest conviction angles on this theme inside the Semiconductor Equipment & Materials Suppliers to Memory and AI Chip Fabs screener.
SUSS MicroTec (XTRA:SMHN)
SUSS MicroTec plugs directly into the Semiconductor Equipment & Materials Suppliers to Memory and AI Chip Fabs theme. It supplies lithography, bonding, and packaging gear that memory fabs rely on while pairing that exposure with a broader toolkit for microelectronics and MEMS customers worldwide.
SUSS MicroTec generates about €329 million from Advanced Backend Solutions and roughly €110 million from Photomask Solutions, making it a key supplier of packaging and photomask equipment to global fabs. The stock is valued at about €1.47 billion today.
Accelerated facility expansion, margin improvement, and rising output position SUSS MicroTec for outsized growth and potential dominance in advanced packaging as industry demand intensifies.
What matters next is how one shifting demand pattern in high end memory and packaging equipment feeds through to pricing power and profitability.
That pricing power question is exactly what the full narrative for SUSS MicroTec tackles, revealing where margins could be more cyclical, resilient, or quietly accelerating.

Powertech Technology (TWSE:6239)
Powertech Technology is an outsourced semiconductor assembly and test specialist that packages and tests memory and AI related chips for global fabs, putting it squarely inside the Semiconductor Equipment & Materials Suppliers to Memory and AI Chip Fabs theme. It generates about NT$85.8b from semiconductors and carries a roughly NT$227.5b market value.
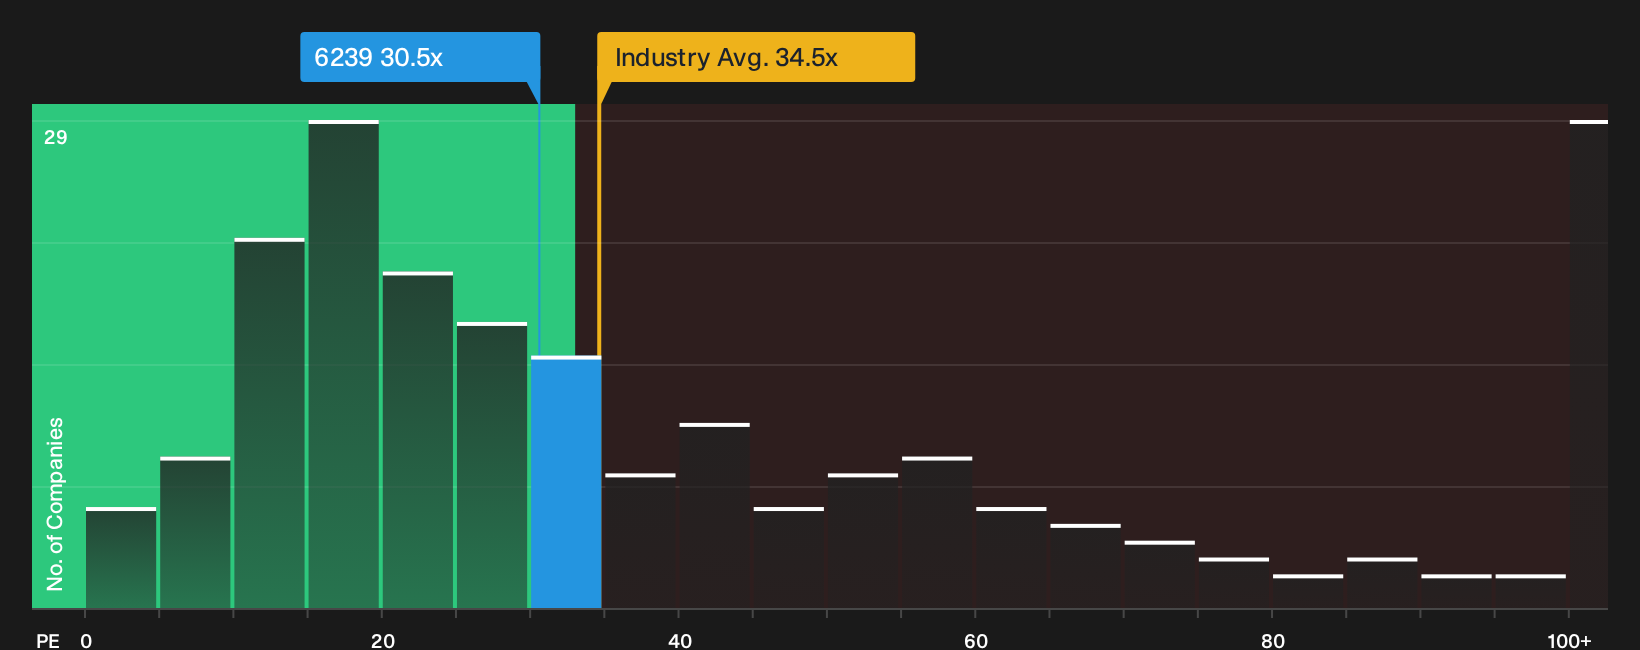
Powertech Technology provides exposure to advanced DRAM, NAND and HBM packages that require complex testing as AI servers ramp. Earnings and revenue for 2026 so far are higher than last year, and the stock trades on a P/E below many local peers. This makes the outlook hinge on how one pressure point in its funding model shapes future expansion costs.
Those expansion costs are the hinge, so check the 3 key rewards and 3 important warning signs (1 is major!) to see how Powertech Technology’s upside and pressure points line up before the next leg of AI build out.
Kulicke and Soffa Industries (KLIC)
Kulicke and Soffa Industries operates on the assembly and packaging side of the AI memory build out, supplying the bonding tools and consumables that turn DRAM, NAND and high bandwidth chips into usable parts on production lines worldwide.
Kulicke and Soffa Industries sells capital equipment and consumables for semiconductor assembly and packaging, with around US$588 million from Ball Bonding Equipment, US$171 million from Aftermarket Products & Services, US$87 million from Advanced Solutions, US$80 million from Wedge Bonding Equipment, and US$24 million from other sources. This supports a business valued at about US$5.3 billion.
Accelerating adoption of advanced packaging, including fluxless thermocompression for heterogeneous logic and HBM, is expected to drive a mix shift toward higher value systems and support structurally higher revenue and gross margins as fiscal 2026 ramps.
What happens to those higher margin expectations if one less visible constraint on future AI focused packaging capacity tightens instead of easing?
If that constraint matters to your thesis, read the full narrative for Kulicke and Soffa Industries to see how capacity, capital intensity, and AI demand could be quietly reshaping the upside profile of Kulicke and Soffa Industries.

Seeking Fresh Alternatives Beyond AI Memory
Fresh breakouts and early momentum often get caught quickly once the crowd shows up. Scan these under the radar ideas before the signal fades and consider them while interest remains limited.
- Target resilient compounding by tracking a curated 168 dividend fortresses that aim to keep distributions flying while prices move around them.
- Ride structural demand shifts by scanning the 40 power grid technology and infrastructure stocks powering electrification, data centers, and grid upgrades while the market is still waking up.
- Spot early secular winners through a focused 89 robotics and automation stocks built around automation, precision hardware, and software that could quietly reshape entire industries.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com