
Could Orezone Gold (TSX:ORE) Be 69% Undervalued After The CEO Growth Plan?
Event-driven interest in Orezone Gold after CEO production plan
Orezone Gold (TSX:ORE) drew fresh attention after President and CEO Patrick Downey outlined a plan to lift annual gold output to about 500,000 ounces using Bomboré, Casa Berardi, and its permitted projects.
At a share price of about CA$3.32, Orezone Gold has recorded a strong 30-day share price return of 20.29% and an 88.64% year-to-date share price gain. The 1-year total shareholder return of 127.40% suggests that momentum has been building rather than fading as investors respond to the production growth plan and the perceived value in assets such as Heva-Hosco.
Scan beyond Orezone Gold and size up other hand-picked producers riding similar momentum with the 36 elite gold producer stocks.
Orezone Gold has already delivered a powerful rerating, yet the recent production blueprint and implied asset value suggest the market may still be catching up. Does the current share price already capture that, or not yet?
Most Popular Narrative: 69% Undervalued
Orezone Gold’s widely followed narrative pegs fair value at about CA$10.68 per share, far above the recent CA$3.32 close. The valuation debate is now about whether the multi mine plan can justify that kind of gap.
The strongest upside comes from four things: higher gold prices, the Bomboré hard rock expansion, the new Casa Berardi platform in Quebec, and a possible market re-rating if Orezone proves it can operate as a diversified multi-mine producer.
Bomboré is ramping hard rock production, Casa Berardi adds Canadian exposure, and the company should generate strong cash flow if gold prices remain elevated.
See why 19 investors see Orezone Gold as 69% undervalued.
Result: Fair Value of CA$10.68 (UNDERVALUED)
Still, Orezone Gold’s story leans heavily on high AISC at Bomboré and successful Casa Berardi integration; any stumble here could quickly challenge that 69% undervalued narrative.
Find out about the key risks to this Orezone Gold narrative.
Another View on Orezone Gold’s valuation
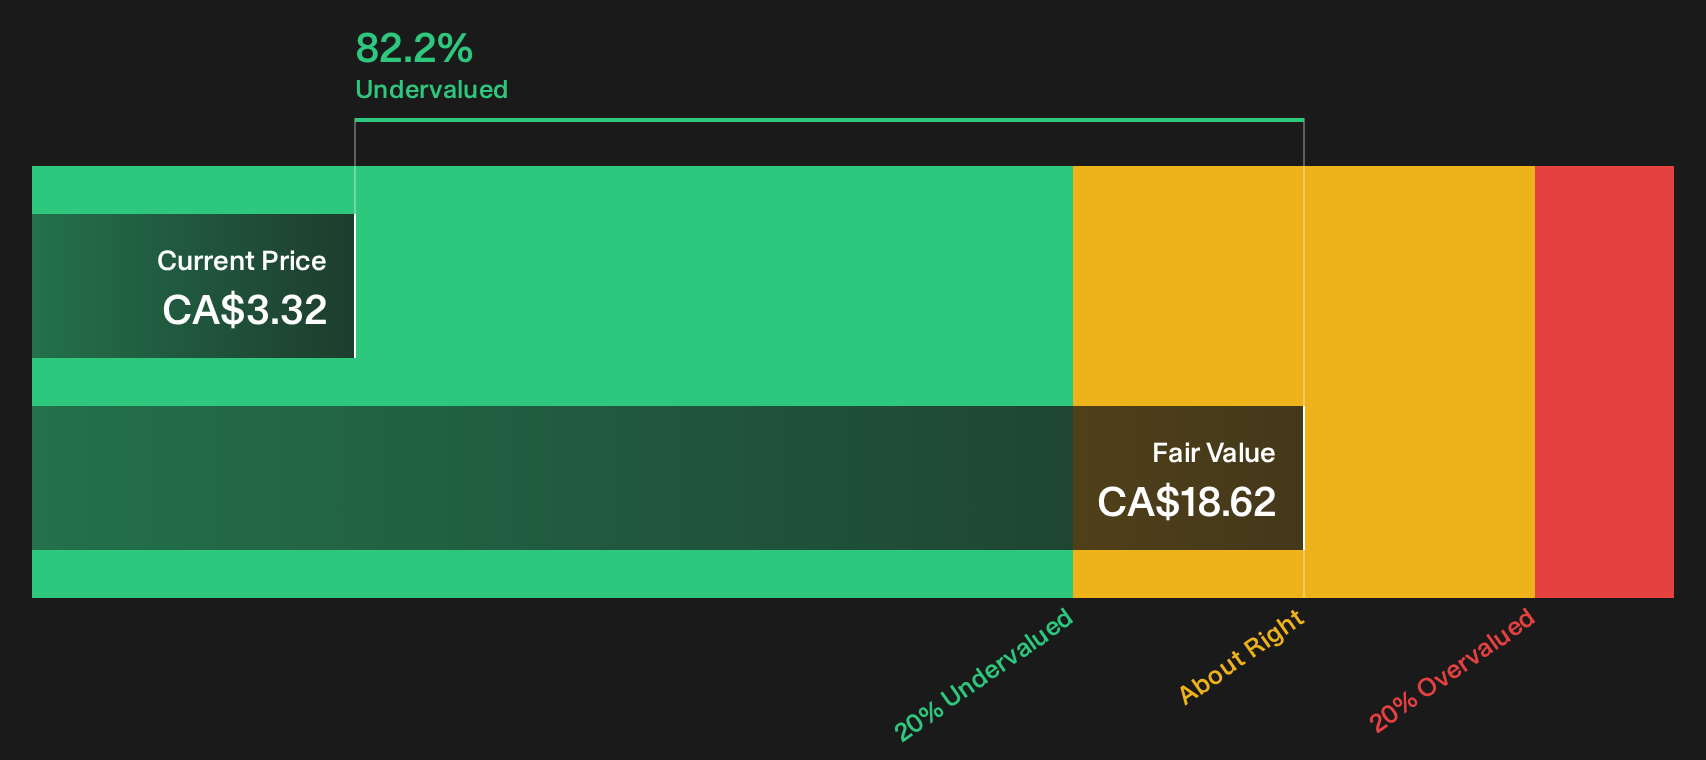
That CA$10.68 fair value narrative is not the only lens on Orezone Gold. Our DCF model points to a future cash flow value of CA$18.62 per share, which can be compared with a recent price of CA$3.32. If both signals point to undervaluation, what risk is the market still pricing in?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Big upside narrative or just selective optimism around Orezone Gold? If you want to move past the headlines and weigh it yourself, start with a clear view of the balance between 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Orezone Gold?
Do not stop with one opportunity. Broaden your watchlist with focused stock ideas that match different investing styles and risk levels using the Simply Wall St Screener.
- Target potential mispricings across sectors by scanning a curated pool of 6 high quality undervalued stocks that combine quality fundamentals with pricing that may interest value driven investors.
- Pinpoint companies focused on income by reviewing a concentrated group of 1 dividend fortresses that aim to deliver higher yields with support from their financial profiles.
- Prioritise resilience by assessing a hand picked set of 8 resilient stocks with low risk scores where balance sheet strength and risk scores take centre stage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com