
Is AT&T Fiber Deal Altering The Investment Case For Corning (GLW)?
- AT&T announced a multi year agreement valued at more than US$3b for Corning to supply U.S. made fiber and cable for its nationwide broadband buildout as data demand from AI grows.
- Corning is also supplying multimode fiber connectivity for a Lumentum and Qualcomm optical interconnect demonstration for AI hardware, linking its broadband footprint to data center build activity.
- This article examines how Corning's investment narrative is influenced by the AT&T fiber agreement and its AI focused optical partnerships.
Corning Investment Narrative Recap
To own Corning, you need to believe its Springboard plan and long duration fiber and solar agreements can translate into higher quality earnings rather than just bigger headline numbers. The recent US$3b AT&T deal supports that narrative by extending visibility in Optical Communications, which ties directly into AI driven bandwidth needs and Corning’s U.S. manufacturing footprint.
The short term swing factor is execution on these large programs without relying heavily on fresh equity after the prior US$2b at the market funding move. The biggest risk remains any hit to confidence in earnings quality or solar execution, which could matter more than incremental wins in optical contracts.
The AT&T agreement looks most relevant because it reinforces one of Corning’s key catalysts: multi year, multi billion supply deals that help underpin the Springboard 20 30 40 targets. This contract adds to existing long duration commitments with large customers and supports the idea of a growing base of contracted fiber and connectivity revenue.
For you as a shareholder, the operational question is whether Corning can turn that contracted optical demand into margins at or above the 20% level targeted in Springboard, while managing debt and avoiding further dilution. Any stumble in converting this backlog into consistent cash generation or any repeat of solar outages would cut into that thesis.
What The Current Corning Forecasts Assume
Corning's narrative projects US$29.4b revenue and US$5.7b earnings by 2029. That outcome lines up with analyst models that incorporate 20.1% yearly revenue growth and an earnings increase of about US$3.8b from US$1.9b today.
Uncover how Corning's fair value indicates a 16% potential upside to its current price, which could narrow quickly if sentiment catches up.
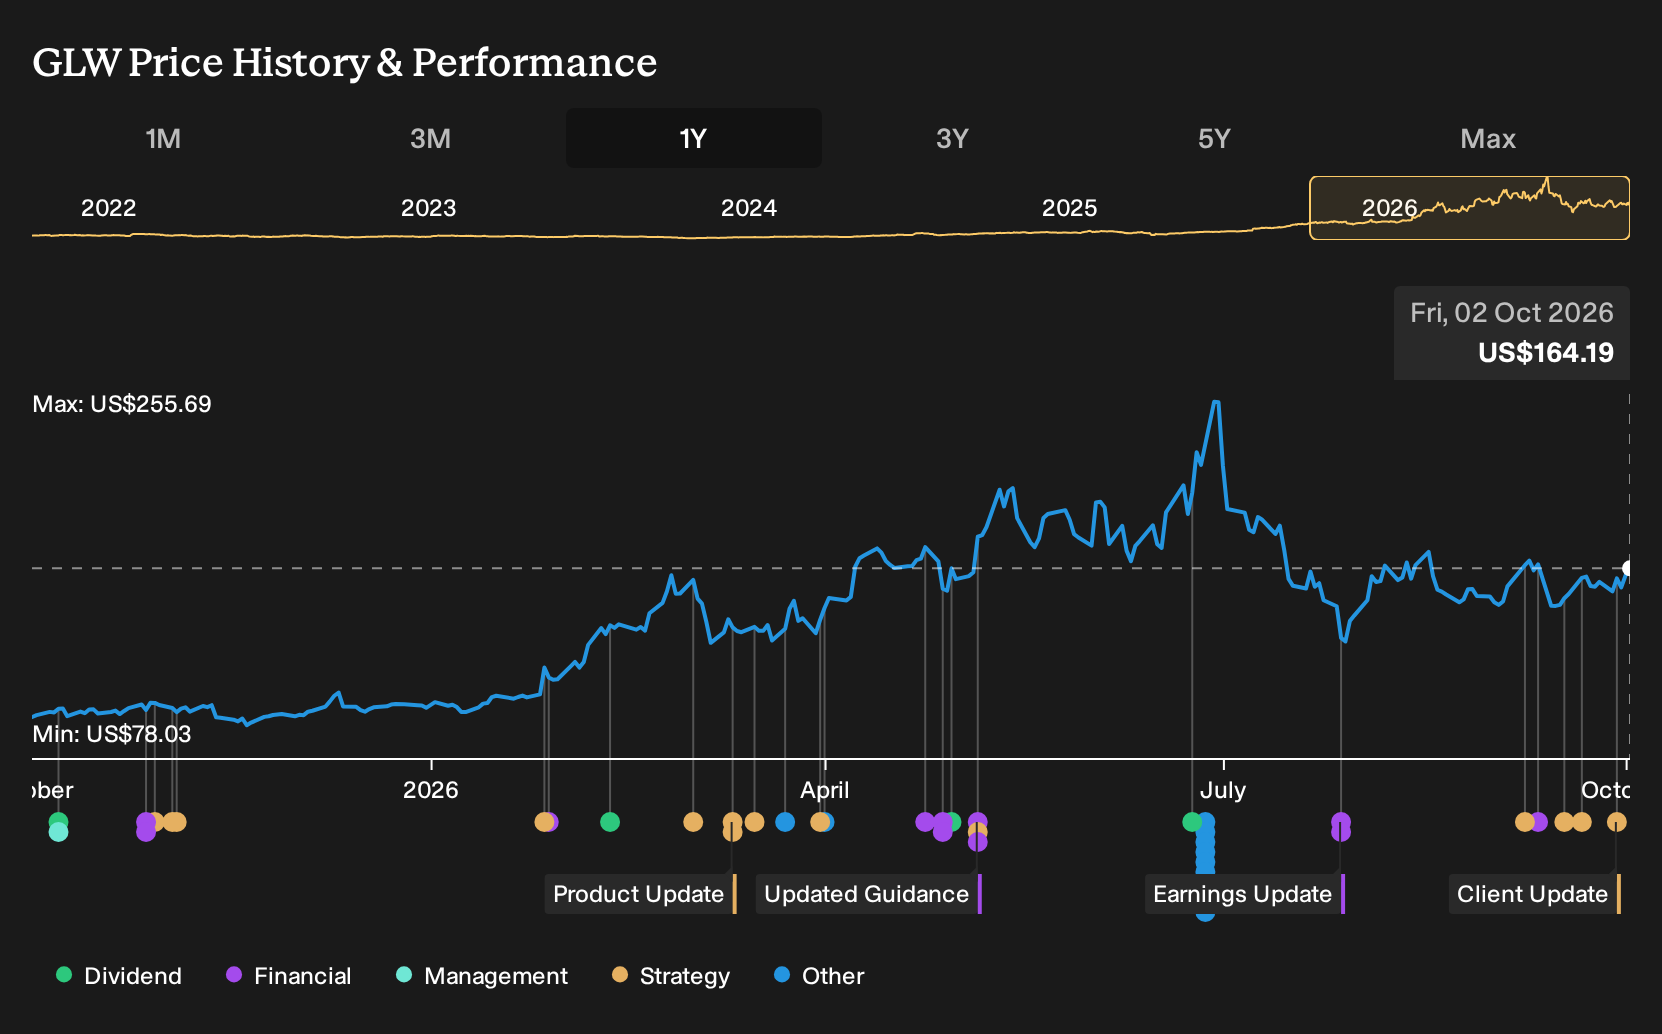
Exploring Other Perspectives
One alternate storyline for Corning puts the spotlight on slower profit expansion rather than contract wins. The most cautious analysts were working off 2029 earnings of about US$4.9b and a margin path that tops out near 16.7%, compared with consensus at US$5.7b. That is a much more conservative lens. It shows how views can diverge widely, so it makes sense to weigh both sets of pre news assumptions and decide which feels closer to your own expectations as these new fiber and AI related deals filter into future models.
Explore 7 other Corning fair value estimates, including one that suggests as much as 19% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corning research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
Once you have a view on Corning, it can help to widen the lens and compare it with other businesses that have different risk profiles, income potential, or valuation setups. The Simply Wall St Screener lets you line up those options quickly using the same consistent data set.
- If you care most about valuation and quality, start with a focused set of 31 high quality undervalued stocks that already combine stronger fundamentals with more modest pricing.
- For income focused investing, you can zero in on steady payers through a curated group of 7 dividend fortresses that target higher yield and resilience.
- If capital protection ranks higher on your list, compare Corning with a 31 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com