
Phillips 66 (PSX) Faces Bayway Strike Risk, Is The Stock Fully Priced?
Phillips 66 (PSX) is back in focus after workers at its Bayway Refinery in New Jersey voted by a 92% margin to authorize a strike ahead of an October 1 contract expiry.
Despite the labor dispute, Phillips 66’s share price has climbed to US$264.58, with a 90-day share price return of 49.20% and a year-to-date share price return of 102.63%, while the 1-year total shareholder return of 104.81% indicates strong recent performance rather than a short-lived spike.
Scan how Phillips 66 compares to other refinery and energy operators facing their own operational and labor pressures with a curated list of list of solid balance sheet and fundamentals (25 results)
After a move that leaves Phillips 66 trading just above the average analyst target and far below some intrinsic value estimates, the gap between sticker price and implied worth is hard to ignore. The key question is where fair value realistically lands.
Most Popular Narrative: 5% Overvalued
At a last close of $264.58 against a narrative fair value of $251.95, Phillips 66 is framed as slightly ahead of where that widely followed thesis would place it, leaving investors to judge whether current execution justifies the premium.
Midstream and marketing activities built around over 1 million barrels per day of NGL fractionation capacity at full or above full utilization and record LPG exports are expected to keep generating largely fee based cash flow. This can underpin earnings stability and the ability to fund dividends and sustaining capex. Selective growth in renewables and chemicals, including the Rodeo renewable diesel facility targeting mid cycle EBITDA of about 700 million and U.S. ethane based CPChem assets benefiting from higher global naphtha costs, is set to add incremental earnings streams that are less tied to traditional refining crack spreads.
See why 46 investors see Phillips 66 as 5% overvalued.
Result: Fair Value of $251.95 (OVERVALUED)
Still, the Phillips 66 story can shift fast if refinery labor disputes drag on or if large mark to market derivative losses absorb cash that investors currently expect elsewhere.
Find out about the key risks to this Phillips 66 narrative.
Another View on Phillips 66’s Valuation
Analysts lean toward Phillips 66 looking around 5% overvalued on a fair value of $251.95, yet Simply Wall St’s DCF model points to a future cash flow value of $497.99, which is far above the current $264.58 share price and implies a very different story for investors to weigh.
That gap between market price and modeled cash flows raises a simple question. Is the crowd overpaying for near term narrative, or is the SWS DCF catching something the market is ignoring right now, especially as labor headlines circle the Bayway Refinery?
Look into how the SWS DCF model arrives at its fair value.
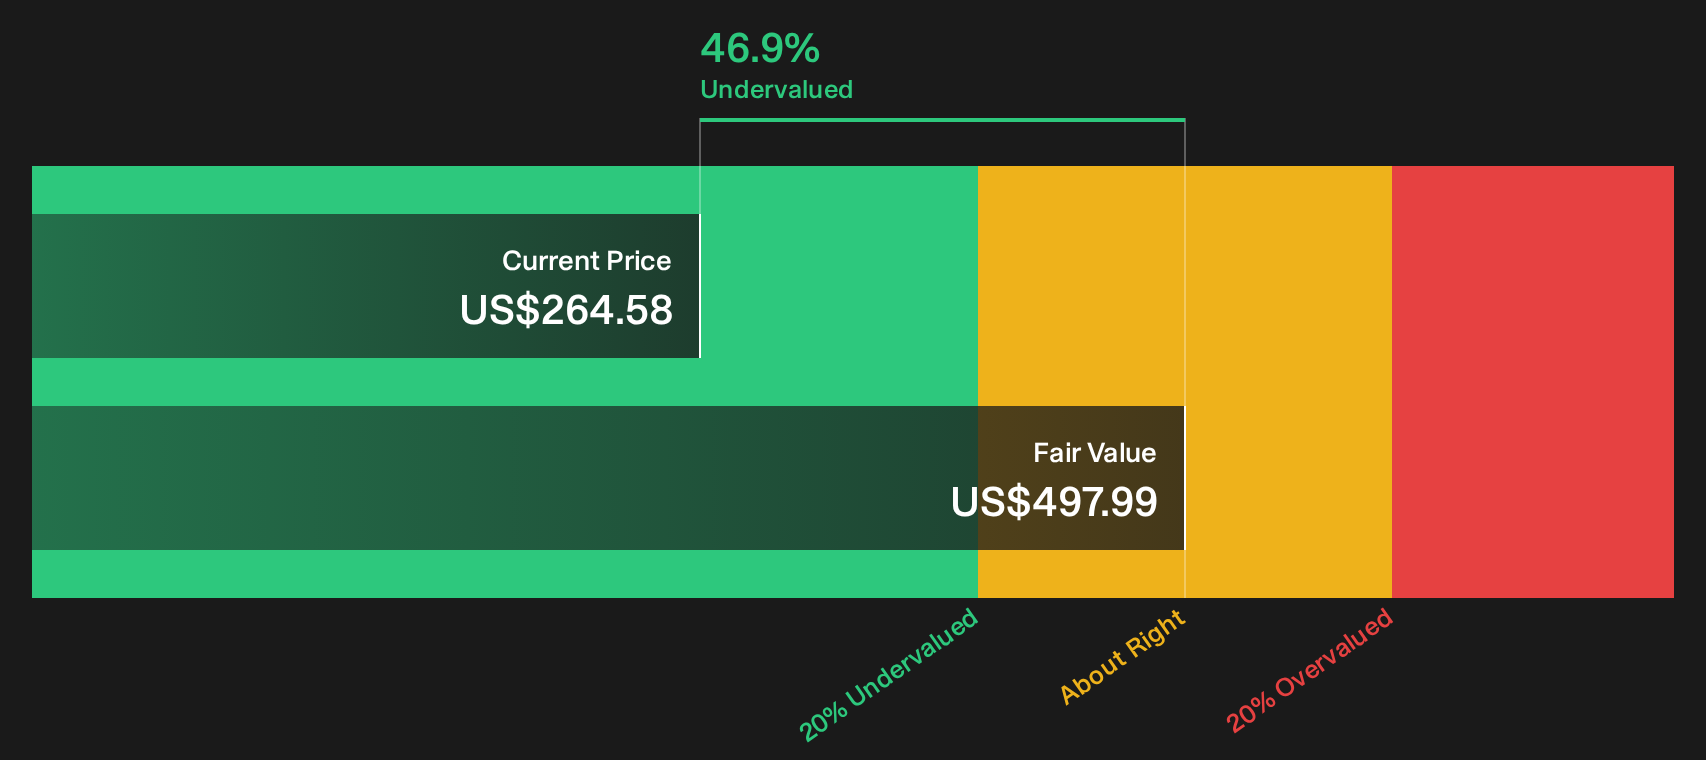
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Phillips 66 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Phillips 66 leaves you undecided, move quickly to review the numbers and form your own stance. You can weigh both sides in one place by checking out the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Phillips 66?
If Phillips 66 has your attention but you do not want to stop there, use this moment to widen your watchlist with a few focused screeners.
- Target steadier compounding by reviewing a curated set of payout focused opportunities through the 7 dividend fortresses.
- Hunt for quality at a discount by scanning companies that pair solid fundamentals with prices that look appealing using the 31 high quality undervalued stocks.
- Stack the odds in your favor by filtering for financially resilient businesses with cleaner balance sheets through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com