
Discovering Shandong Head GroupLtd And 2 Other Undiscovered Gems In Asia
As Asian markets navigate through a landscape marked by fluctuating oil prices and elevated bond yields, investors are increasingly looking towards small-cap stocks for potential opportunities. In this context, identifying companies with strong fundamentals and growth potential can be key to uncovering undiscovered gems like Shandong Head Group Ltd., which may offer unique value propositions amidst the current market dynamics.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Chengtun Mining Group | 99.24% | -6.93% | 33.44% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Shandong Head GroupLtd (SZSE:002810)
Simply Wall St Value Rating: ★★★★★☆
Overview: Shandong Head Group Co., Ltd. focuses on producing and selling water-soluble polymer compounds, food additives, and cellulose plant products both domestically in China and internationally, with a market capitalization of approximately CN¥6.95 billion.
Operations: The company's primary revenue stream comes from cellulose ether products, generating CN¥1.50 billion, followed by vegetable empty capsule products at CN¥586.24 million. Other chemical products contribute CN¥44.62 million and graphite products add CN¥32.36 million to the revenue mix. The net profit margin is a key financial metric to consider when evaluating overall profitability and efficiency in managing costs relative to its sales revenue.
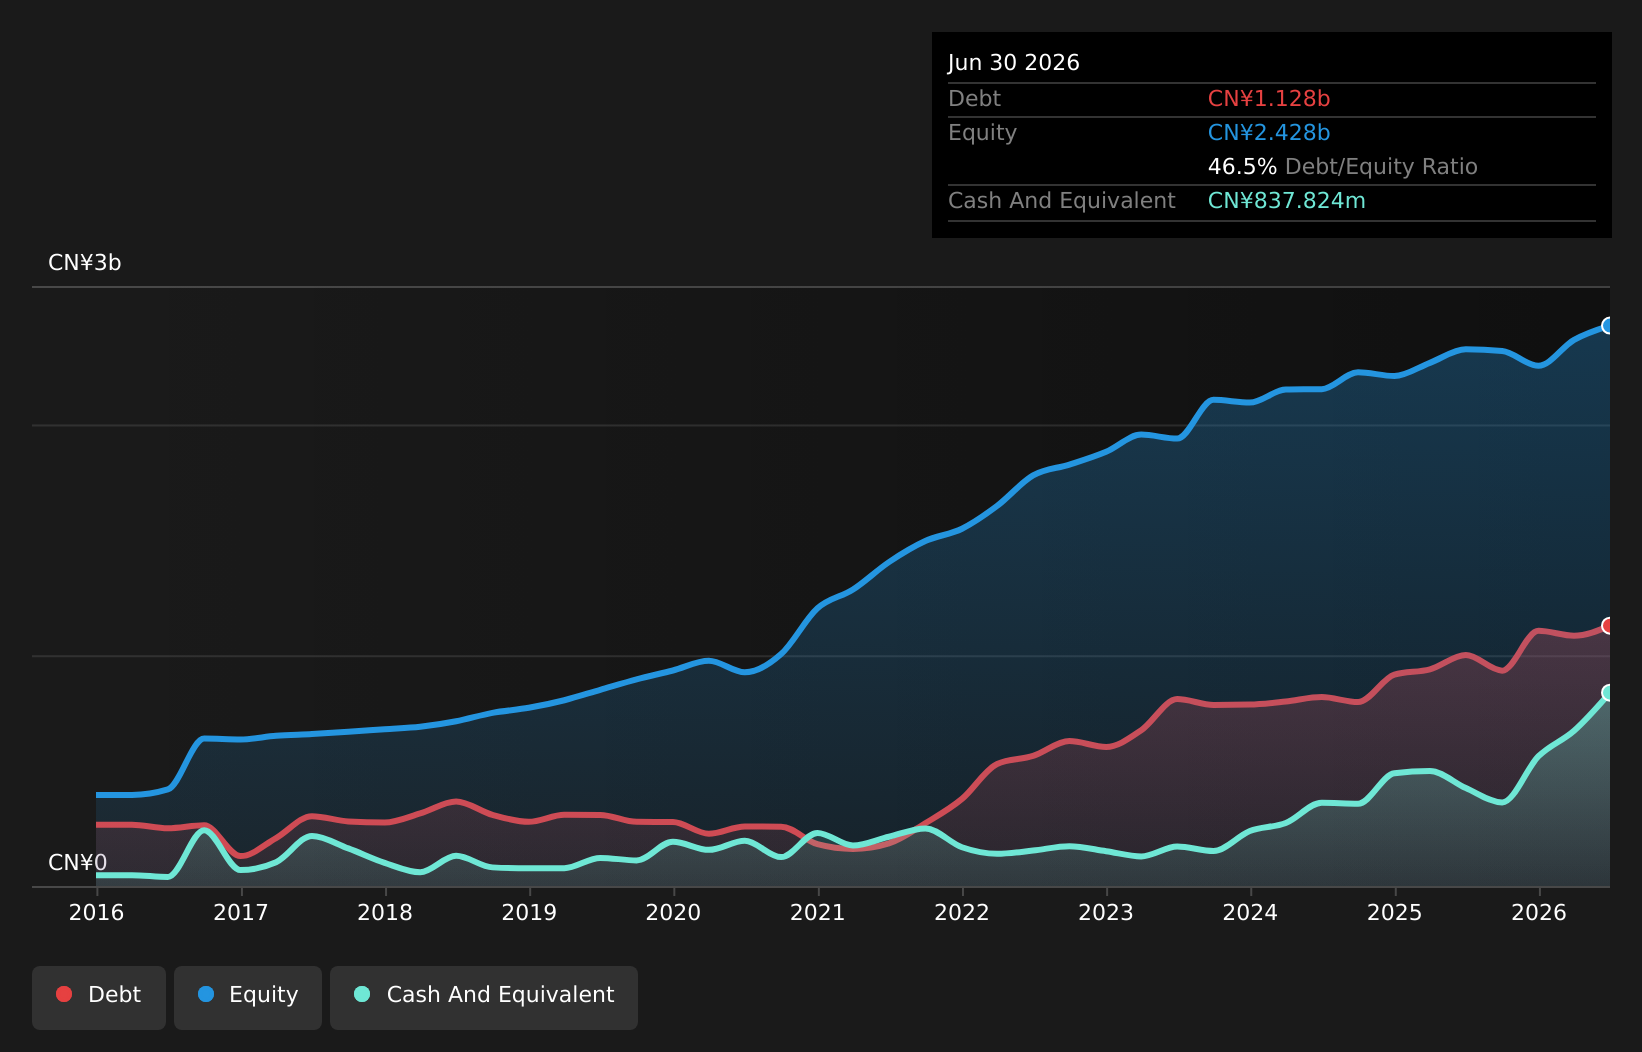
Shandong Head Group, a notable player in the chemicals sector, has demonstrated a robust performance with earnings growth of 14.6% over the past year, outpacing the industry average of 3.2%. The company seems to be trading at good value compared to peers and is currently valued at 81.3% below its estimated fair value. Its net debt to equity ratio stands at a satisfactory 12.6%, while interest payments are well covered by EBIT with a coverage ratio of 13.6x. Recent financials reveal sales reaching CNY1,223 million for H1 2026, up from CNY970 million last year, alongside net income climbing to CNY213 million from CNY113 million previously.
- Take a closer look at Shandong Head GroupLtd's potential here in our health report.
Assess Shandong Head GroupLtd's past performance with our detailed historical performance reports.
Warabeya Nichiyo Holdings (TSE:2918)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Warabeya Nichiyo Holdings Co., Ltd. operates in the manufacture and sale of food products for convenience stores across Japan, the United States, and internationally, with a market capitalization of approximately ¥45.66 billion.
Operations: Warabeya Nichiyo generates revenue primarily from its Food Products Business, which accounts for ¥210.67 billion, followed by the Logistics Business at ¥19.64 billion and the Food Materials Business contributing ¥11.57 billion.
Warabeya Nichiyo Holdings, a notable player in the food industry, is trading at 87.2% below its estimated fair value, indicating potential for investors. The company boasts high-quality earnings and satisfactory debt management with a net debt to equity ratio of 27.5%. Over the past year, earnings surged by 76.8%, outpacing the industry's growth rate of 9.1%. Recent guidance projects full-year sales of ¥241 billion (US$1.61 billion) and an operating profit of ¥7.7 billion (US$51 million). Despite lower first-quarter net income compared to last year, Warabeya's strategic positioning suggests promising prospects ahead.
- Navigate through the intricacies of Warabeya Nichiyo Holdings with our comprehensive health report here.
Evaluate Warabeya Nichiyo Holdings' historical performance by accessing our past performance report.

Eurocharm Holdings (TWSE:5288)
Simply Wall St Value Rating: ★★★★★★
Overview: Eurocharm Holdings Co., Ltd. is engaged in the manufacturing and sales of motorcycle and auto equipment parts, medical equipment, and machine parts across Taiwan, Vietnam, the United States, and internationally with a market capitalization of NT$13.14 billion.
Operations: Eurocharm generates revenue primarily from the manufacturing and sales of automobile, motorcycle parts, and medical equipment, totaling NT$7.81 billion.
Eurocharm Holdings has shown a strong financial performance recently, with second-quarter sales reaching TWD 2.41 billion, up from TWD 1.57 billion the previous year, and net income rising to TWD 308.26 million from TWD 100.81 million. Basic earnings per share increased significantly to TWD 4.44 from TWD 1.46 a year ago, indicating robust profitability despite not outpacing the Auto Components industry's growth rate of 13.2%. The company’s debt-to-equity ratio has impressively decreased over five years from 50.4% to just 2.7%, suggesting effective debt management and positioning it well below its estimated fair value by approximately 59%.
- Click here to discover the nuances of Eurocharm Holdings with our detailed analytical health report.

Taking Advantage
- Explore the 116 names from our Asian Undiscovered Gems With Strong Fundamentals screener here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com