
Aker (OB:AKER) Could Be 22% Undervalued After Executive Reshuffle
Executive reshuffle across the Aker ecosystem
Aker (OB:AKER) is back on investor screens after a cluster of leadership changes across its industrial network, including fresh executive lineups at Aker BP and Aker Solutions.
The reshaping of Aker BP’s management, effective from January 2027, focuses on organizing around the upstream value chain and using industrial data and artificial intelligence in Norwegian offshore operations.
Aker Solutions is also refreshing its leadership, with Ine Dolve stepping in as Executive Vice President for the Life Cycle segment from 12 October 2026, following Paal Eikeseth’s move to President & CEO.
Recent moves around Aker come after a powerful run, with the share price delivering a 79.2% year to date return and a 90.18% total shareholder return over the past 12 months. This comes even though the 1 month share price return is down 13.29% and the 7 day share price return is down 3.46%, hinting that enthusiasm has cooled slightly as investors weigh these leadership shifts against a 14.99% 3 month share price return and a much longer 178.51% 3 year total shareholder return that still points to strong long term sentiment.
Scan for other Aker style restructurings by reviewing the 615 high quality undiscovered gems that combine leadership change with solid fundamentals.
Aker now looks like a stronger industrial platform after this reshuffle. The harder question is whether that strength is already fully reflected in a NOK 1,396 share price and recent index inclusion.
Most Popular Narrative: 22% Undervalued
Aker last closed at NOK 1,396, while the most followed narrative on the stock pins fair value at NOK 1,800 per share, so the discussion now turns to what might justify that gap.
Key Assumptions & Valuation Logic: Net Asset Value (NAV) Revaluation: Baseline Q2 2026 NAV of NOK 1,429 per share is adjusted upward to reflect the implied market valuation of AI infrastructure provider Nscale at a target IPO valuation of $25B (~NOK 262.5B).
Nscale Ownership Contribution: Aker’s 22.7% stake in Nscale is valued at ~NOK 59.6B (~NOK 802/share). Factoring in existing carrying values, this delivers a net NAV lift of ~NOK 370 per share, establishing an updated intrinsic NAV of NOK 1,799 (~NOK 1,800).
See why 5 investors see Aker as 22% undervalued.
Result: Fair Value of NOK 1,800 (UNDERVALUED)
Still, Aker’s thesis relies heavily on a successful Nscale IPO and on investors remaining willing to value the group with only a minimal NAV discount.
Find out about the key risks to this Aker narrative.
Another View on Aker’s Value
The upbeat NOK 1,800 fair value for Aker leans heavily on a user-built net asset story around Nscale. A very different picture comes from Simply Wall St’s DCF model, which puts future cash flow value at just NOK 50.93 per share, so the stock screens as expensive on that lens. That gap raises a simple question. Which matters more for you, near term cash generation or a potential re-rating of underlying assets?
Look into how the SWS DCF model arrives at its fair value.
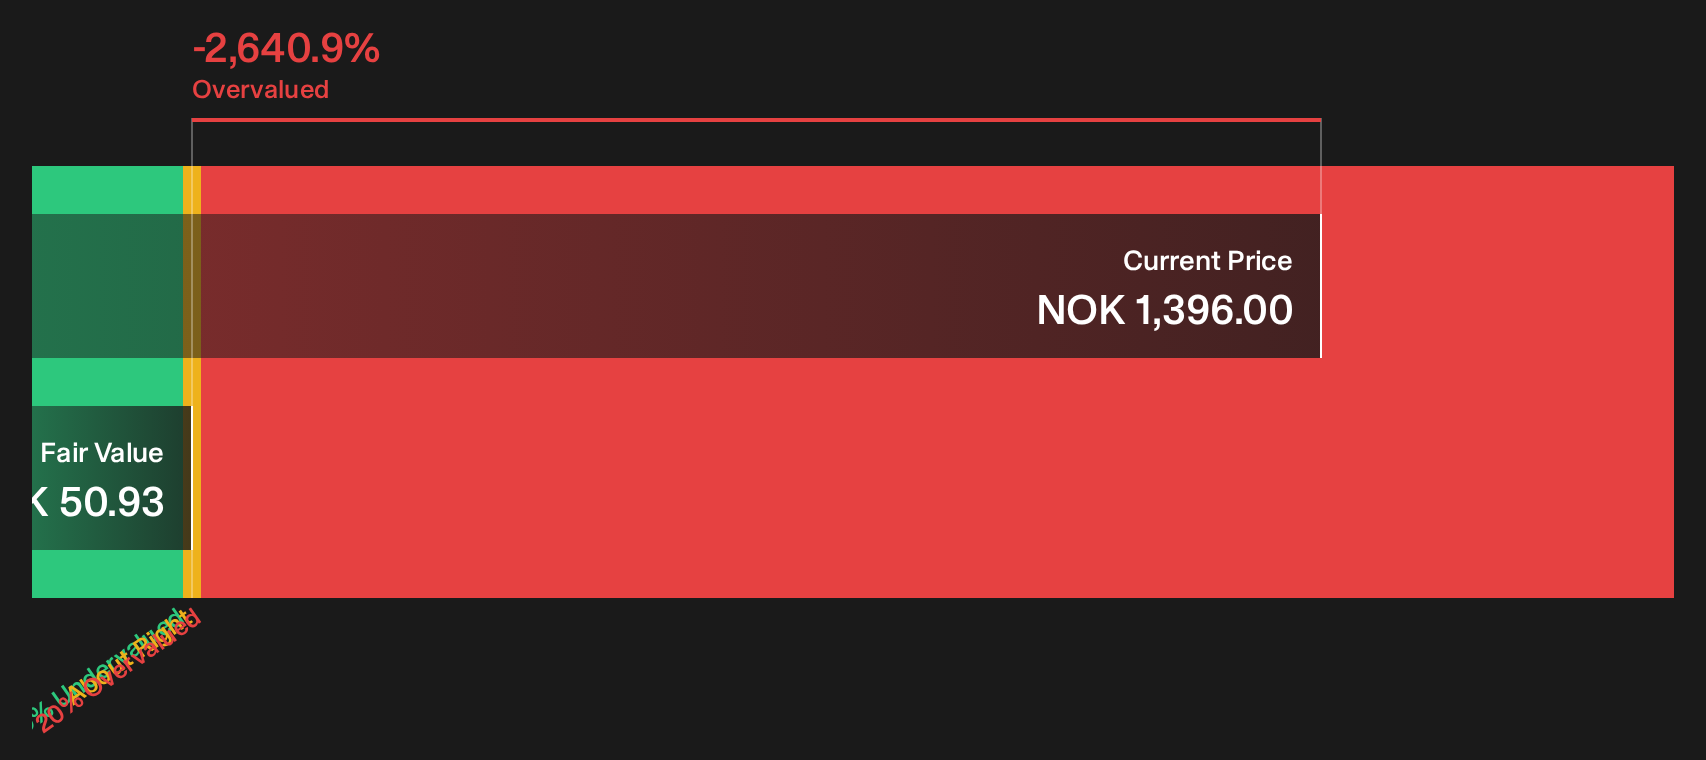
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aker for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Aker feels familiar, consider taking the opportunity while sentiment is still split and review the details yourself using the 3 key rewards and 3 important warning signs.
Looking for more Aker style investment ideas?
Do not stop with Aker. Broaden your watchlist now and consider more ways to benefit from shifts in leadership, balance sheets, and shareholder returns.
- Target sturdier portfolios by using the 227 resilient stocks with low risk scores to help you sidestep some of the more fragile businesses in the market.
- Look for stronger future potential with the 192 high quality undervalued stocks, which highlights companies where current prices sit below underlying fundamentals.
- Seek more consistent cash returns with the 168 dividend fortresses, which focuses on stocks offering higher yields with income in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com