
First Interstate BancSystem (FIBK) Stock Could Be Reasonably Priced Despite A 76% Run
First Interstate BancSystem has delivered a strong share price run over the past few years, which naturally puts the focus on what you are paying for today. The question now is whether the returns it earns on its capital are solid enough to support the current valuation.
- The stock has gained about 76.0% over the past 3 years, so a lot of investor confidence in First Interstate BancSystem is already reflected in the price.
- The business model depends heavily on how efficiently it turns deposits and equity into earning assets, which can shape both long term profitability and the justification for reinvesting capital at current rates of return.
- What if you looked at First Interstate BancSystem through its earnings instead? See why First Interstate BancSystem's 10.6x P/E tells a different valuation story.
For investors, the debate is whether the returns First Interstate BancSystem earns on its capital are strong enough to make the current share price look well supported.
If you are weighing whether First Interstate BancSystem's 76.0% three year return is justified by the returns it earns on its capital, it can help to compare that theme across 31 high quality undervalued stocks.
Does First Interstate BancSystem Look Undervalued on Excess Returns?
The Excess Returns model looks at how efficiently First Interstate BancSystem turns its equity base into profits above the required return that shareholders demand. It compares what the bank earns on its book value with the cost of that equity capital.
For First Interstate BancSystem, the inputs describe a lender expected to earn slightly more than its equity cost over time. Book Value is $34.77 per share, with a Stable Book Value estimate of $36.01 per share, while Stable EPS is $2.89 per share based on estimates from 7 analysts. The model uses a Cost of Equity of $2.61 per share and an Excess Return of $0.28 per share, supported by an Average Return on Equity of 8.03%. These projections help explain why the Excess Returns model puts the estimated intrinsic value meaningfully above the current share price of $36.00.
This type of profile tends to appeal to investors who prefer established banks where profitability on equity is expected to modestly outpace the required return. If you want to see how that compares with other stocks, it can help to check which companies the same model suggests may also be trading below their estimated intrinsic worth. Find out what First Interstate BancSystem could be worth using our Excess Returns estimate.
The First Interstate BancSystem Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for First Interstate BancSystem leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than it is today on the market. Each scenario ties its number to a clear view on how revenue expansion, margin direction and risk factors could shift, giving you something concrete to revisit as new information on the bank arrives on Simply Wall St's Community page.
Community views on First Interstate BancSystem split between those who see balanced risk and reward and those who focus on pressure from a shrinking balance sheet.
Bull case: roughly fairly valued
"Strong capital and liquidity levels provide flexibility for value creation and support for shareholder returns through multiple strategic options…"
Discover why this Narrative puts First Interstate BancSystem at roughly fairly valued.
Bear case: 9% overvalued
"Although First Interstate BancSystem continues to talk about optimizing its footprint, the faster than expected balance sheet contraction from weaker organic loan production…"
Explore why this Narrative puts First Interstate BancSystem at 9% overvalued.
One more unresolved piece for First Interstate BancSystem
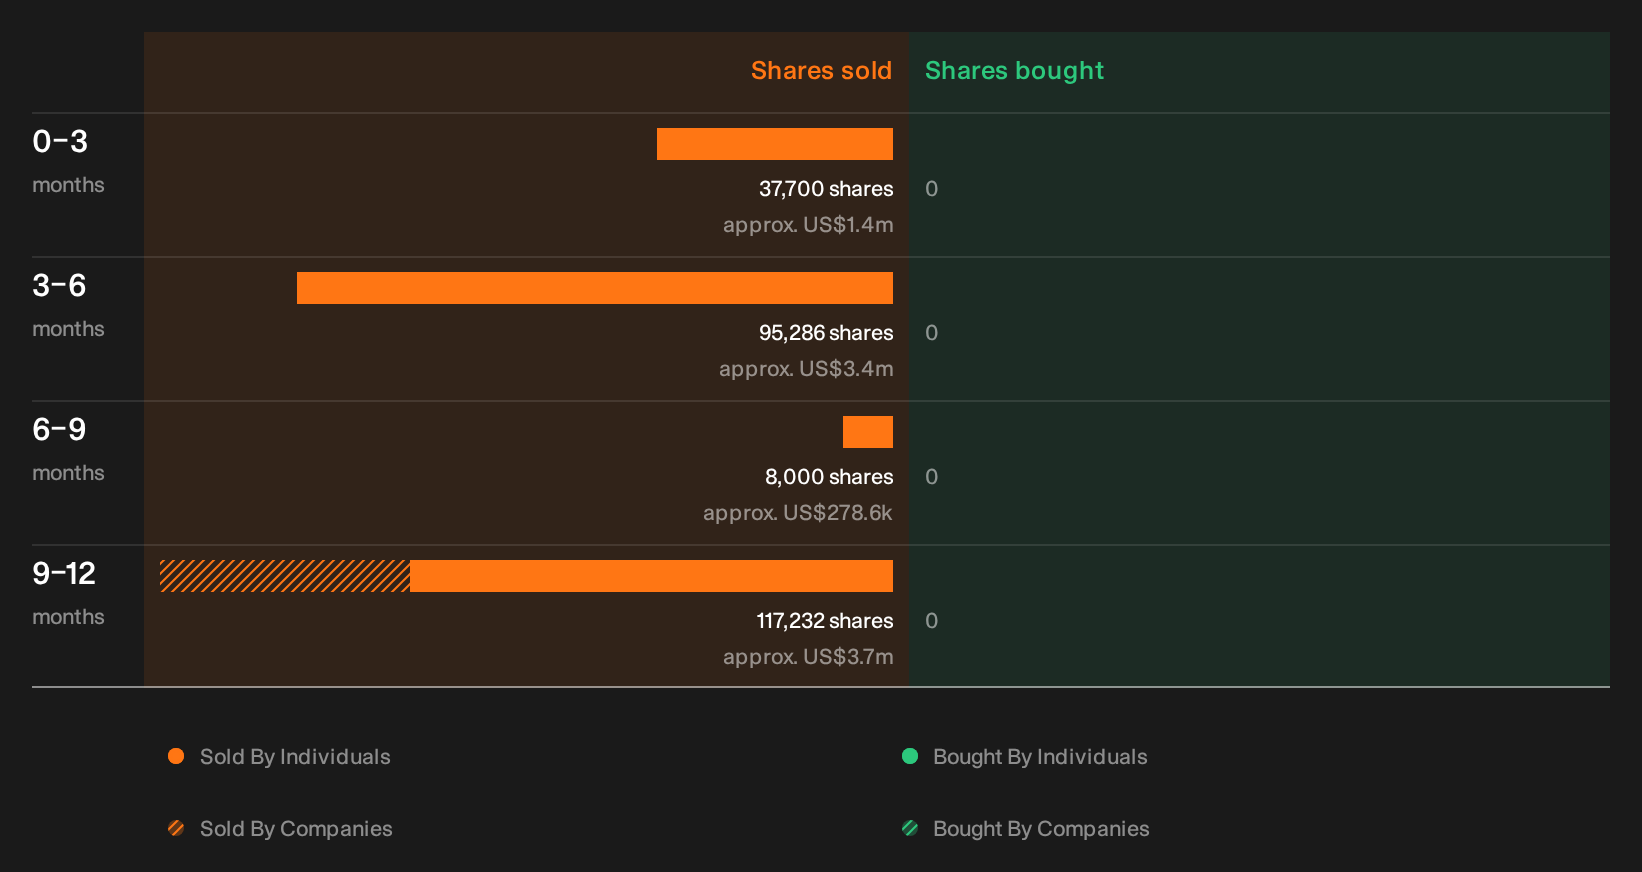
Valuation only answers part of the story for First Interstate BancSystem, because recent trading disclosures suggest insiders have been selling and the who, how much and why could reshape how you read everything else. See the recent insider selling flagged for First Interstate BancSystem.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com