
Mitchell Services And 2 Australian Penny Stocks To Watch
Fresh from the Federal Reserve’s latest interest rate hike, investors are again reminded that borrowing costs can change quickly while smaller Australian companies still have to keep their balance sheets tight. That is where financially resilient penny stocks can catch the eye. They can offer exposure to early stage growth stories, backed by relatively healthier finances. This article walks through three such picks from our screen and what sets each apart.
The three stocks highlighted below are just a small sample, with our full Financially Fit Penny Stocks screen surfacing 397 more companies with similarly grounded stories that are not covered here.
If you want to focus on the ideas that best match your risk and return preferences, head straight to the Financially Fit Penny Stocks screener to filter, analyze, and identify the targets that align most closely with your views.
Mitchell Services (ASX:MSV)
Overview: Mitchell Services provides surface and underground drilling for exploration, resource definition and mine development, giving miners revenue-critical drilling capacity across Australia.
Operations: The business generates about A$210 million from drilling services to the mining industry, entirely sourced from projects within Australia.
Market Cap: A$117 million
For the Financially Fit Penny Stocks theme, Mitchell Services matters because its drilling rigs, contracts and mine-site work tie directly to ongoing exploration and development spending rather than more speculative concept-stage projects.
"The new Loop JV, offering specialized decarbonization solutions to mining clients, opens a significant recurring growth avenue as regulatory pressures for emissions reduction increase, with early project success and strong client interest supporting the potential for higher future specialized service margins."
What could really move the needle for Mitchell Services from here may hinge on how one quiet shift in client spending preferences plays out.
That quiet shift is exactly what full narrative for Mitchell Services unpacks, revealing how the Loop JV and contract mix could accelerate or stall the next phase for Mitchell Services.

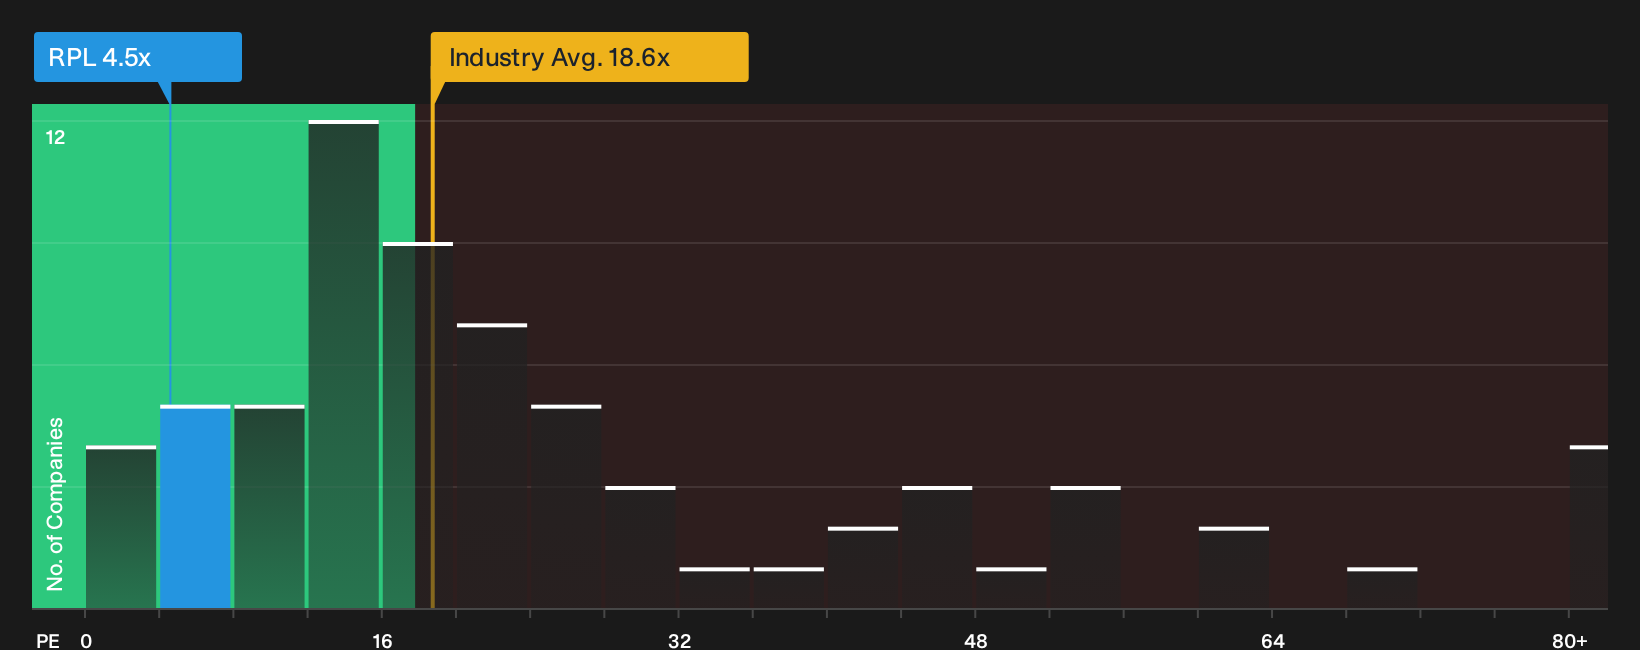
Regal Partners (ASX:RPL)
Overview: Regal Partners is a Sydney based alternative asset manager that runs hedge funds and growth equity portfolios, including strategies focused on smaller, early stage and lower priced stocks.
Operations: The group generates about A$475 million from investment management services, all sourced from clients and funds based in Australia.
Market Cap: A$892 million
Regal Partners matters for the Financially Fit Penny Stocks theme because its growth and hedge fund arms actively channel capital into smaller, financially sound listed companies that fit the same profile many readers are screening for in their own portfolios.
"Ongoing product innovation and diversification into private assets, credit, real assets, and new investment strategies (for example, hotels via Ark Capital) tap into the structural shift of global capital towards alternatives, helping sustain and increase fee-earning opportunities regardless of volatility in traditional markets. The growing dominance of passive investing strategies and ETFs globally could siphon client assets away from active alternative managers like Regal Partners, potentially reducing future assets under management (AUM) and curbing long-term management fee revenue growth."
The pressure that really matters here is how one quiet change in investor preference could reshape Regal Partners’ pricing power and earnings resilience.
That pricing power question is exactly what full narrative for Regal Partners tackles, showing how Regal Partners could see earnings resilience accelerate or stall as investor preferences keep shifting.
MaxiPARTS (ASX:MXI)
Overview: MaxiPARTS supplies commercial truck and trailer parts and workshop consumables across Australia, giving smaller-cap exposure to recurring transport maintenance spending.
Operations: MaxiPARTS generates about A$252 million from MaxiPARTS operations and A$23 million from Förch Australia, almost entirely within Australia.
Market Cap: A$104 million
For the Financially Fit Penny Stocks theme, MaxiPARTS matters because its truck parts and consumables distribution builds repeat demand around essential vehicle upkeep rather than one off big ticket projects.
"MaxiPARTS supplies commercial vehicle spare parts and workshop consumables across Australia. The business is relying on continued low double digit growth from the Japanese parts program and Forch Australia, so any slowdown in these newer categories or increased competition in higher margin niches could limit mix benefits and pressure EBITDA margin and net margin."
What really shapes the upside for MaxiPARTS now is how one quiet shift in mix between everyday parts and newer higher margin lines ultimately lands.
That mix shift is exactly what the full narrative for MaxiPARTS unpacks, highlighting where MaxiPARTS’ everyday parts engine could be quietly masking or accelerating the real earnings story.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the sharpest breakouts often come from corners most investors ignore. Spot fresh momentum while it matters, before prices get caught chasing, and act now.
- Track cash rich small caps poised for the next leg of momentum by scanning the curated list of solid balance sheet and fundamentals (12 results) before they stop looking cheap.
- Position ahead of the next wave of high quality compounders by reviewing the hand picked 15 high quality undiscovered gems while they are still flying under most radars.
- Target durable income ideas with real staying power by checking the curated 3 dividend fortresses before yields drop and the best options are gone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com