
How Product Launches Will Impact Trane Stock Investors
- Trane Technologies recently introduced advanced residential cold climate heat pumps and multiple new data center cooling solutions, including AI factory reference designs and a flexible LiquidStack CDU platform, aimed at high-efficiency thermal management across homes and large-scale computing sites.
- The cluster of launches, spanning electrified home heating and AI-focused liquid cooling, highlights Trane Technologies expanding further into two energy- and capital-intensive markets where efficiency and reliability directly influence customer operating costs.
- Next, the focus will be on how Trane Technologies’ cold climate heat pumps and AI data center cooling portfolio could reshape its investment narrative.
Trane Technologies Investment Narrative Recap
To own Trane Technologies, you need to believe the business can turn its record US$12.1b backlog, strong commercial HVAC demand in the Americas and growing services into durable earnings, without letting pricing pressure and regional mix erode margins. The cluster of new residential heat pumps and AI cooling offerings speaks to that same thesis of efficiency-led projects with hard cost paybacks for customers.
The key near-term swing factor still looks like commercial and data center project execution, since any slowdown or deferral there could feed straight into bookings conversion and earnings. Pricing versus inflation also remains a live risk. The recent launches help broaden the opportunity set but do not yet change those core catalysts or pressures in a material way.
The residential cold climate heat pump launch across the Trane and American Standard brands feels most connected to the existing story. These units are engineered to maintain 100% heating capacity down to 5°F, continue operating down to minus 20°F and have already cleared the U.S. Department of Energy’s Cold Climate Heat Pump Technology Challenge performance bar, backed by roughly 18,000 hours of field testing.
For an investor, that matters because the narrative already leans on electrification and high-efficiency products as a support for future revenue and profitability. The ability to serve colder regions with variable-speed, all-electric systems that reduce backup heat use could help Trane Technologies deepen its residential footprint, provide more recurring service potential and balance some of the reliance on non-residential projects that dominate current backlog risk.
What The Trane Technologies Consensus Is Baking In
Trane Technologies' latest product cycle only tells part of the story. Analyst models fill in the rest by tying that backlog, the heat pump push and the AI data center cooling build out to specific revenue and earnings targets.
Based on current consensus, Trane Technologies' narrative projects US$29.5b in revenue and US$4.7b in earnings by 2029. That profile assumes revenue expands by 10.0% a year and earnings rise by about US$1.7b from roughly US$3.0b today.
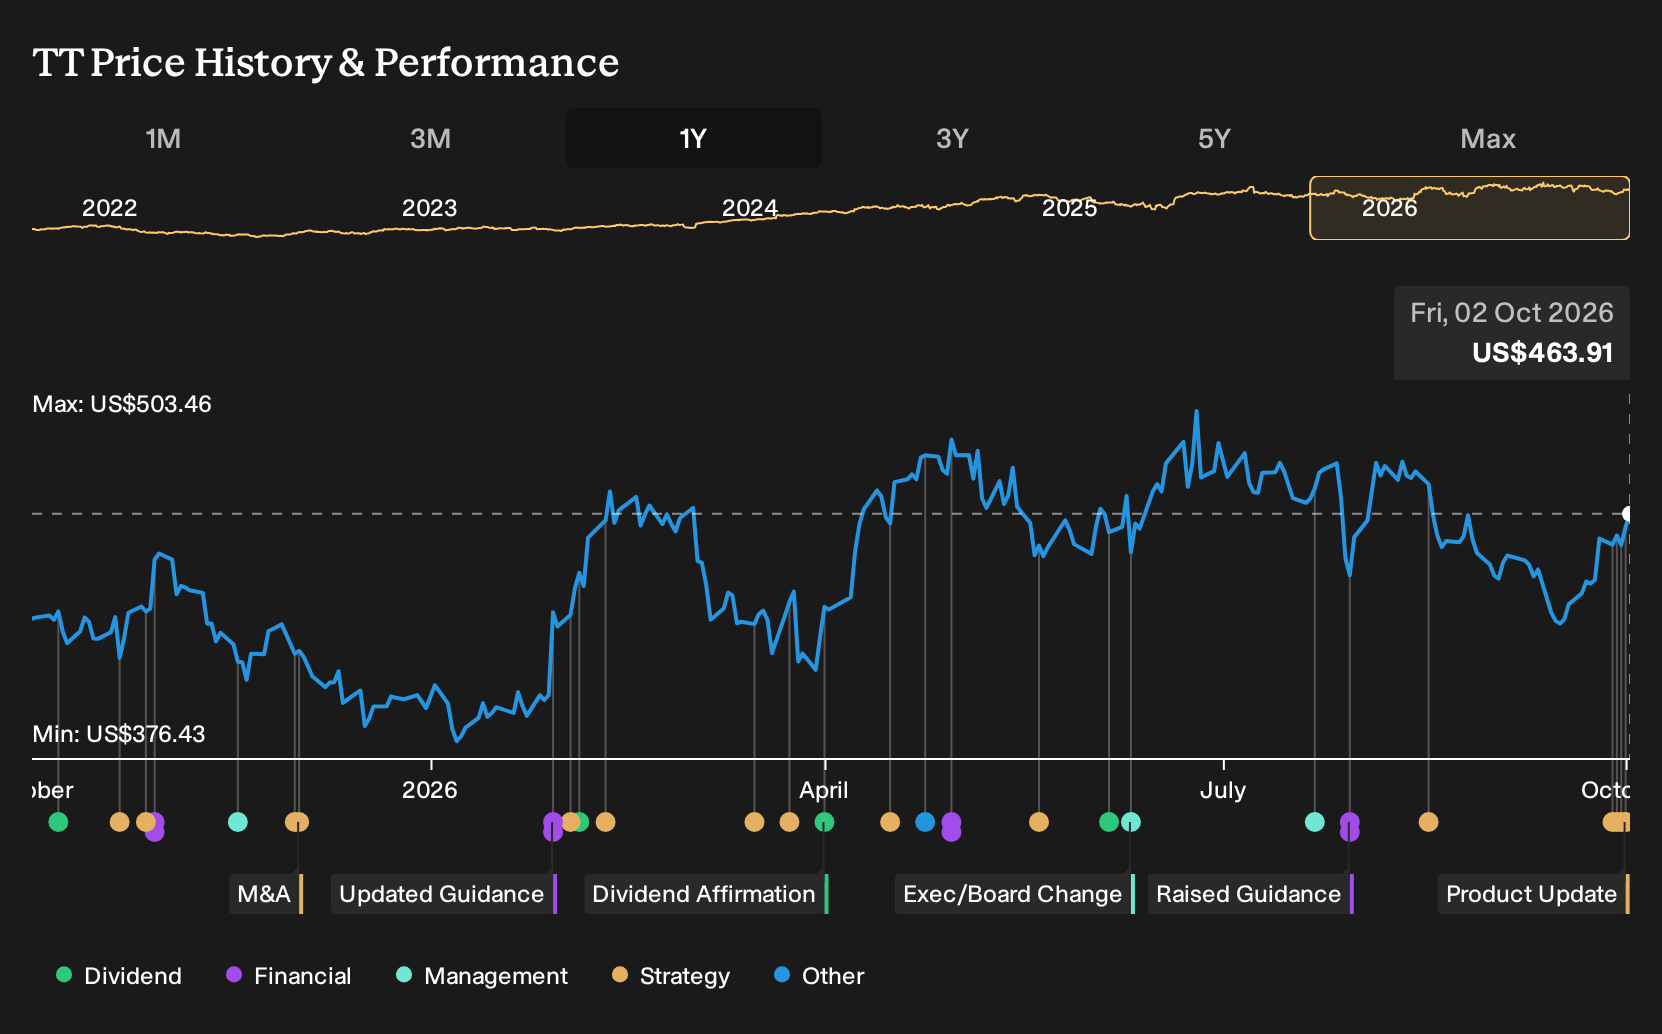
Uncover why Trane Technologies' fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Trane Technologies’ data center cooling push at the center of the story. The most optimistic analysts were already modeling revenue of US$31.7b and earnings of US$5.1b by 2029 before this AI and heat pump news. That outlook is far more upbeat than consensus and could shift again as these launches are digested.
Explore 4 other Trane Technologies fair value estimates, including one that suggests as much as 14% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Trane Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trane Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trane Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Trane Technologies?
If the Trane Technologies story has sharpened your interest in energy efficiency, balance sheet strength or reliable income, the next step is to widen the search. The Simply Wall St Screener can help you filter for stocks that match your own risk profile and return goals instead of relying on a single narrative.
- For investors who care most about quality at a sensible entry point, start with a focused set of 31 high quality undervalued stocks that combine strong fundamentals with attractive pricing.
- If capital preservation and steadier performance matter more to you than big swings, filter for 31 resilient stocks with low risk scores that score well on resilience metrics.
- For those hunting for strong balance sheets and solid underlying businesses, scan the list of solid balance sheet and fundamentals (26 results) to see which companies clear your quality bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com