
Veeco Instruments (VECO) Draws Fresh Attention After A Rally But Is It Still Undervalued
Why Veeco Instruments Is On Investors’ Radar Today
Veeco Instruments (VECO) is back in focus after fresh performance data highlighted how its compound annual return over the past 5 years has outpaced the broad market by 6.66%, sharpening interest in its long term track record.
Short term momentum around Veeco Instruments has picked up sharply, with a 1 day share price return of 7.88% and a 30 day share price return of 33.38% at a last close of $57.38. The 1 year total shareholder return of 81.52% and 5 year total shareholder return of 153.56% underline how recent gains build on a longer record rather than appearing in isolation.
Scan beyond Veeco Instruments and line up other fast moving chip and hardware plays with the curated 90 AI infrastructure stocks that fit a similar high momentum profile.
After a surge like this, the real tension for Veeco Instruments holders and would be buyers is simple: Does the current price still leave enough reward for the risk now on the table?
Most Popular Narrative: 5% Undervalued
Against Veeco Instruments' last close of $57.38, the most followed narrative pegs fair value at $60.33, so the story currently leans slightly to the optimistic side and leans heavily on how future growth and margins play out.
Current investor sentiment may be overestimating the sustained demand and revenue growth from advanced semiconductor manufacturing equipment, as macroeconomic uncertainty, reduced capital expenditure from major chipmakers, and the risk of global trade tensions, including potential recurring tariffs and regulatory barriers, particularly in China, could materially slow new orders and end-market growth, leading to more volatile top-line results in coming years.
Veeco's guidance and narrative reflect optimism about growth drivers such as AI, advanced packaging, and 3D architectures, but industry consolidation and increased bargaining power among large customers could put downward pressure on average selling prices and squeeze net and operating margins, particularly as competition intensifies both in legacy and emerging technologies.
Find out how 11 investors see Veeco Instruments as 5% undervalued.
Result: Fair Value of $60.33 (UNDERVALUED)
Still, the core risk around Veeco Instruments is clear, with concentrated exposure to China and a small group of major customers that could amplify any policy or spending shock.
Find out about the key risks to this Veeco Instruments narrative.
Another View On Veeco Instruments’ Valuation
The earlier fair value of $60.33 paints Veeco Instruments as modestly undervalued. A different lens tells a cooler story. The SWS DCF model estimates the value of future cash flows at $30.07 per share, which sits well below the current $57.38 price. Which signal do you trust more: sentiment or cash flows?
For readers who want to see how those cash flow assumptions are built and stress tested over time, Look into how the SWS DCF model arrives at its fair value.
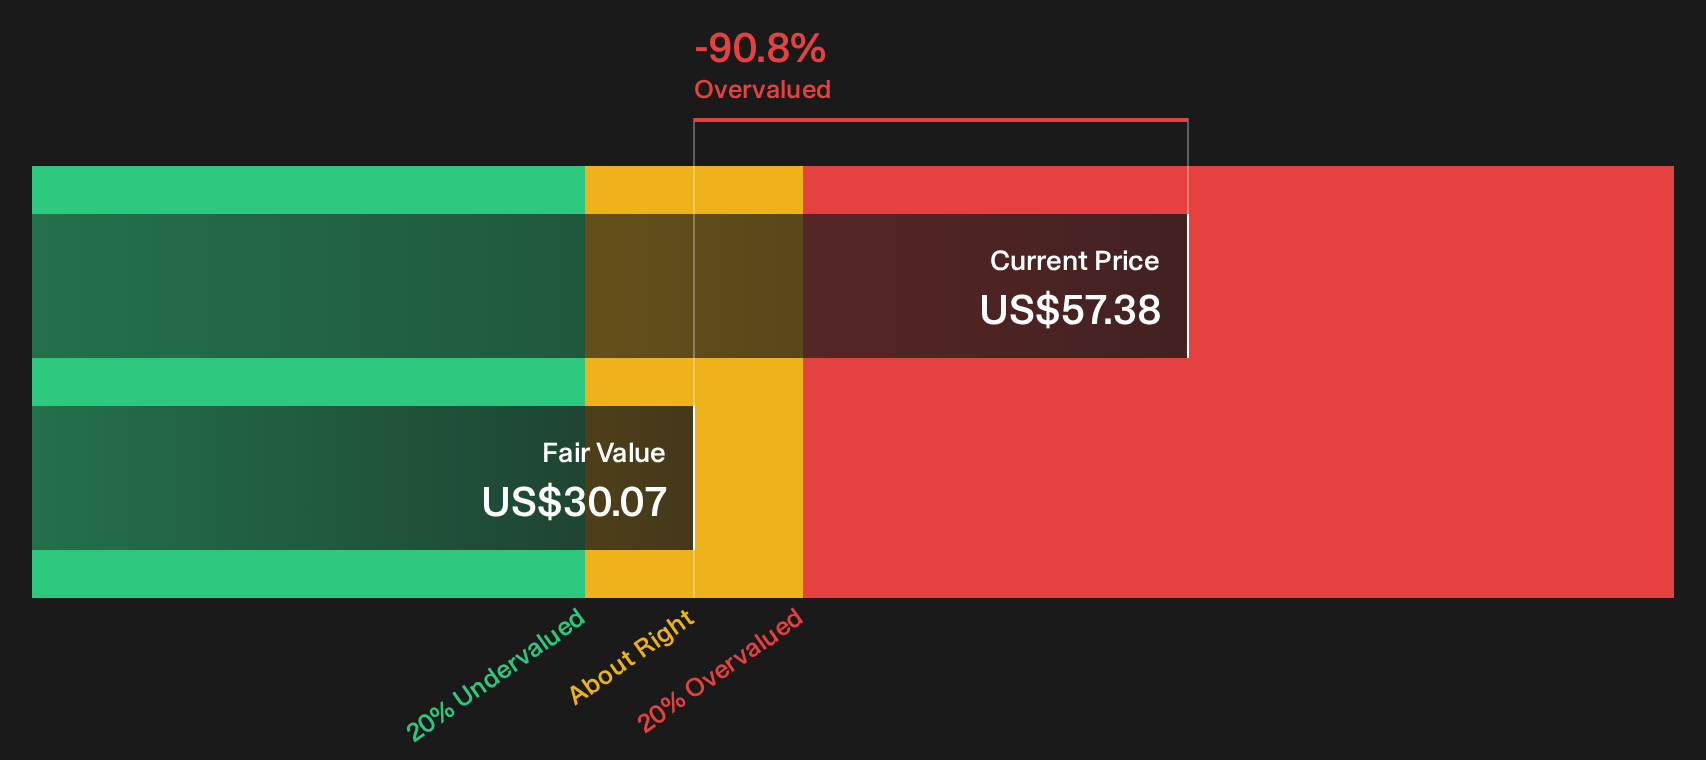
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Veeco Instruments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Veeco Instruments so far, or just a complex story waiting to be unpacked? Act while the data is fresh and weigh both sides through the 1 key reward and 3 important warning signs.
Looking for more ideas beyond Veeco Instruments?
Consider looking beyond Veeco Instruments, as the same data driven tools can surface other opportunities that might fit your goals even better.
- Target resilience by scanning a 31 resilient stocks with low risk scores that filters for stocks with steadier risk profiles and fewer nasty surprises.
- Hunt for quality at a discount with the 19 high quality undiscovered gems and spot strong fundamentals before the crowd pays attention.
- Strengthen your core holdings by running a list of solid balance sheet and fundamentals (26 results) to focus on companies backed by cleaner balance sheets and healthier finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com