
3 British Cash Flow Stocks For October 2026
The recent warning from Energy UK about rising domestic gas prices and higher winter bills has pushed cash generation to the top of the agenda for many British companies. When energy and borrowing costs bite, businesses with solid cash inflows yet subdued share prices can draw more interest from patient investors. This article highlights three UK listed stocks that screen as undervalued on future cash flows.
The three stocks below are just a starting sample, as the same cash flow screen surfaced 26 more companies with equally detailed stories that are not covered here.
If you want to quickly identify and analyze potential opportunities that look undervalued on discounted cash flow metrics, head straight into the Undervalued Stocks Based On Cash Flows screener.
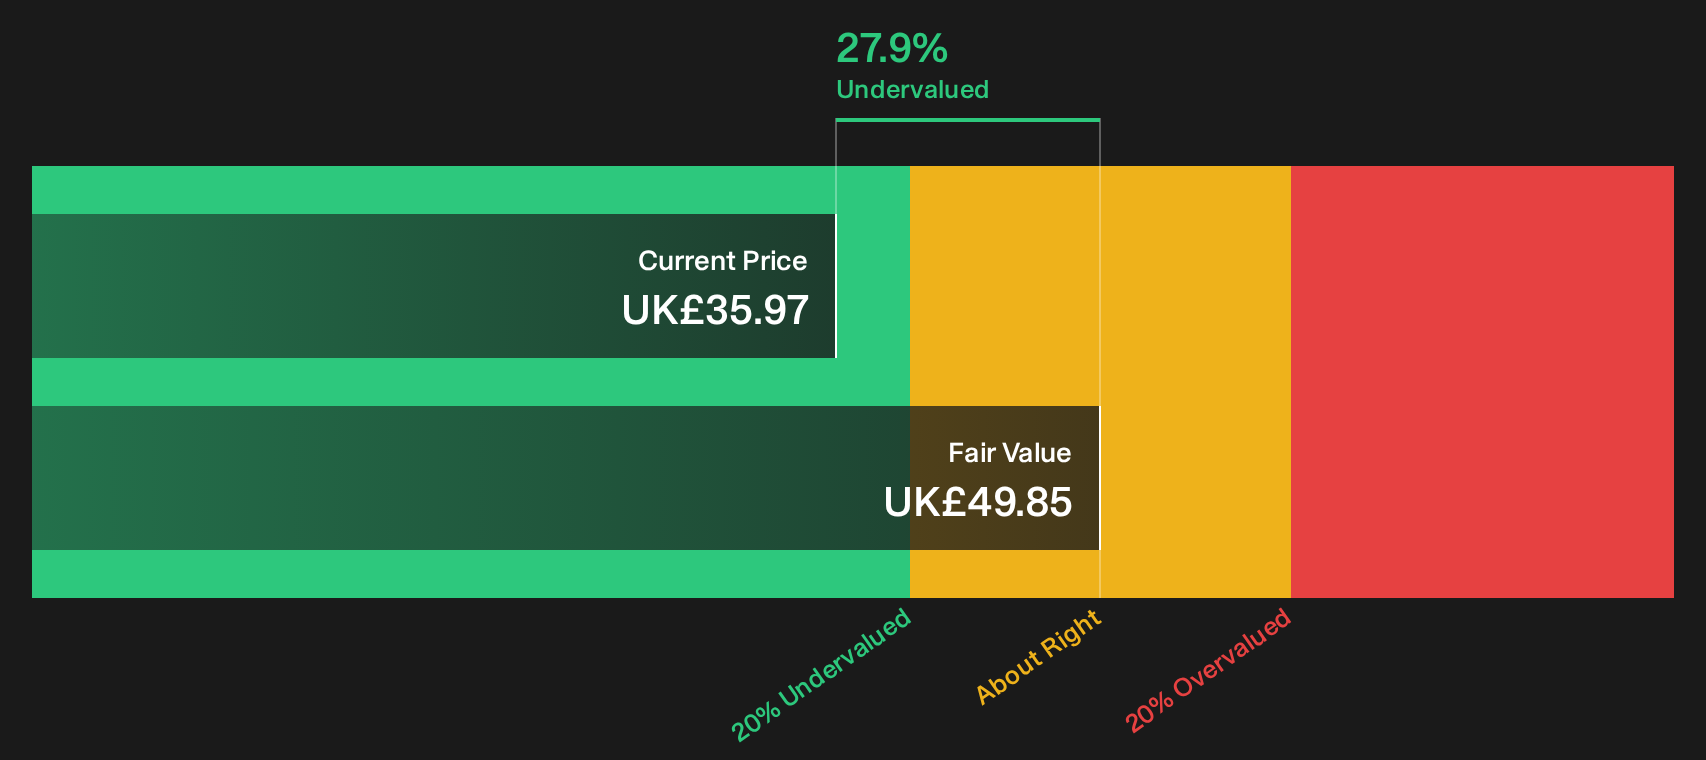
Shell (LSE:SHEL)
Overview: Shell is a global energy group that produces and trades oil, gas, chemicals and low carbon solutions, including biofuels and EV charging.
Operations: Shell generates most of its revenue from Marketing at about US$135b, Chemicals and Products at roughly US$132b, and Renewables and Energy Solutions at around US$42b, with additional contributions from Integrated Gas and Upstream.
Market Cap: £206.1b
Shell matters for this cash flow focused screen because its traditional oil and gas engine now funds a growing portfolio of energy transition assets that still price in some scepticism.
"With an LNG portfolio exceeding 60 million tons and unparalleled trading capabilities, Shell is the company that benefits most from the volatility in the global gas market."
What happens to Shell’s valuation if a single pressure point around future cash returns shifts in either direction?
If that pressure eases or accelerates, the full narrative for Shell shows how Shell’s cash engine, transition spend and valuation expectations could decouple in surprising ways.
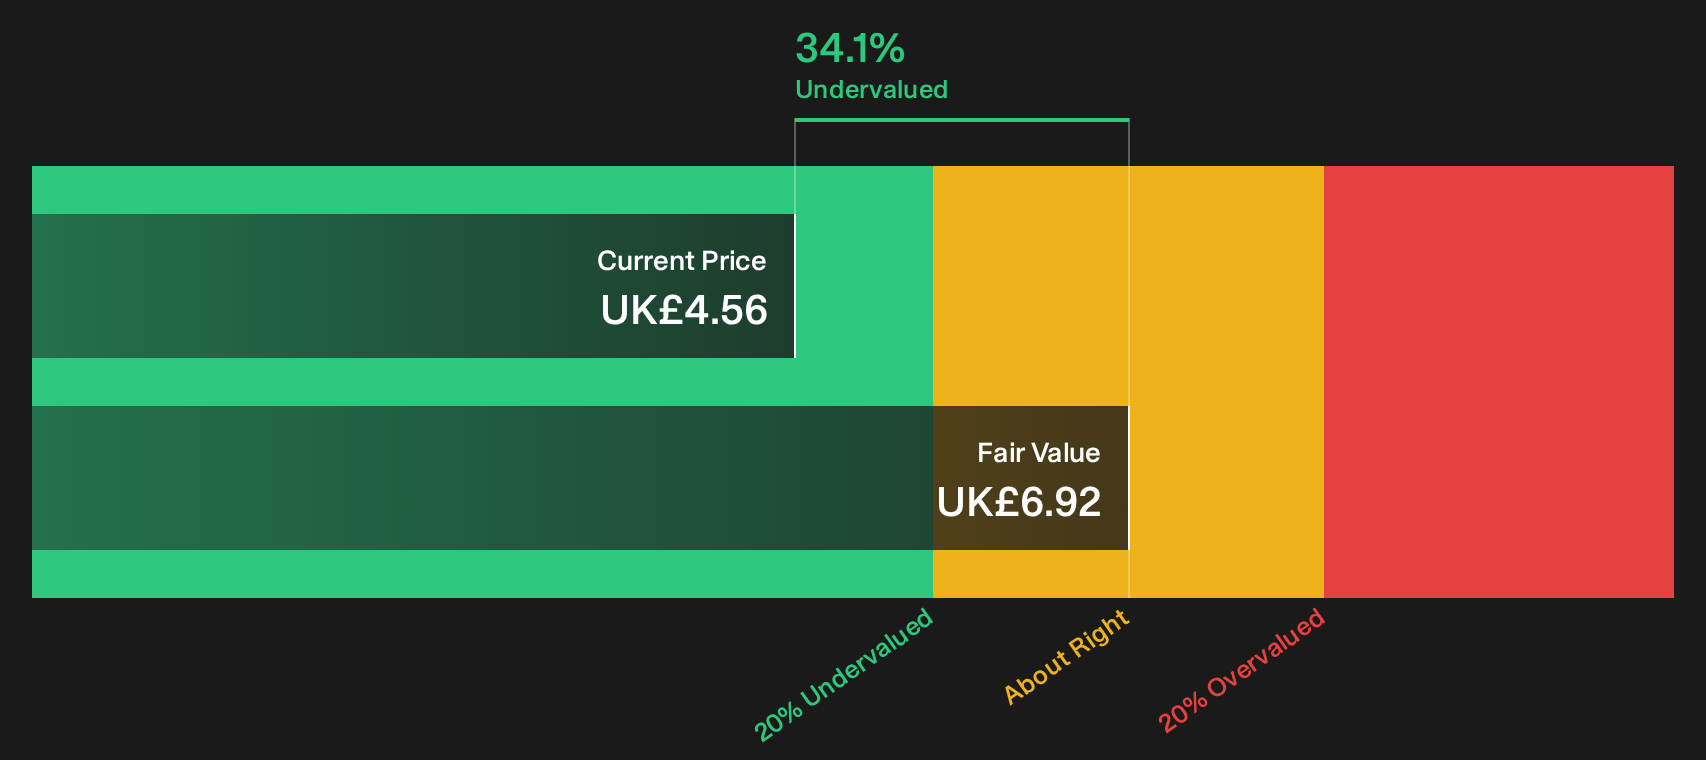
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is an investment manager whose renewable infrastructure platforms generate recurring cash flows alongside wider private equity, venture and listed real asset strategies.
Operations: Foresight earns about £114.8 million from Real Assets and £50.1 million from Private Equity, with most income coming from the United Kingdom.
Market Cap: £503.7 million
Foresight Group Holdings taps directly into the cash-flow theme through its renewable energy infrastructure funds, where long-term contracts can turn sun, wind and storage assets into relatively predictable fee streams for shareholders.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
The real test is how one shifting assumption about future fundraising momentum ultimately shapes those cash yields and equity returns per share.
That fundraising hinge is exactly what the full narrative for Foresight Group Holdings unpacks, spelling out how accelerating or stalling inflows could reshape Foresight Group Holdings’ fee engine and payout capacity.
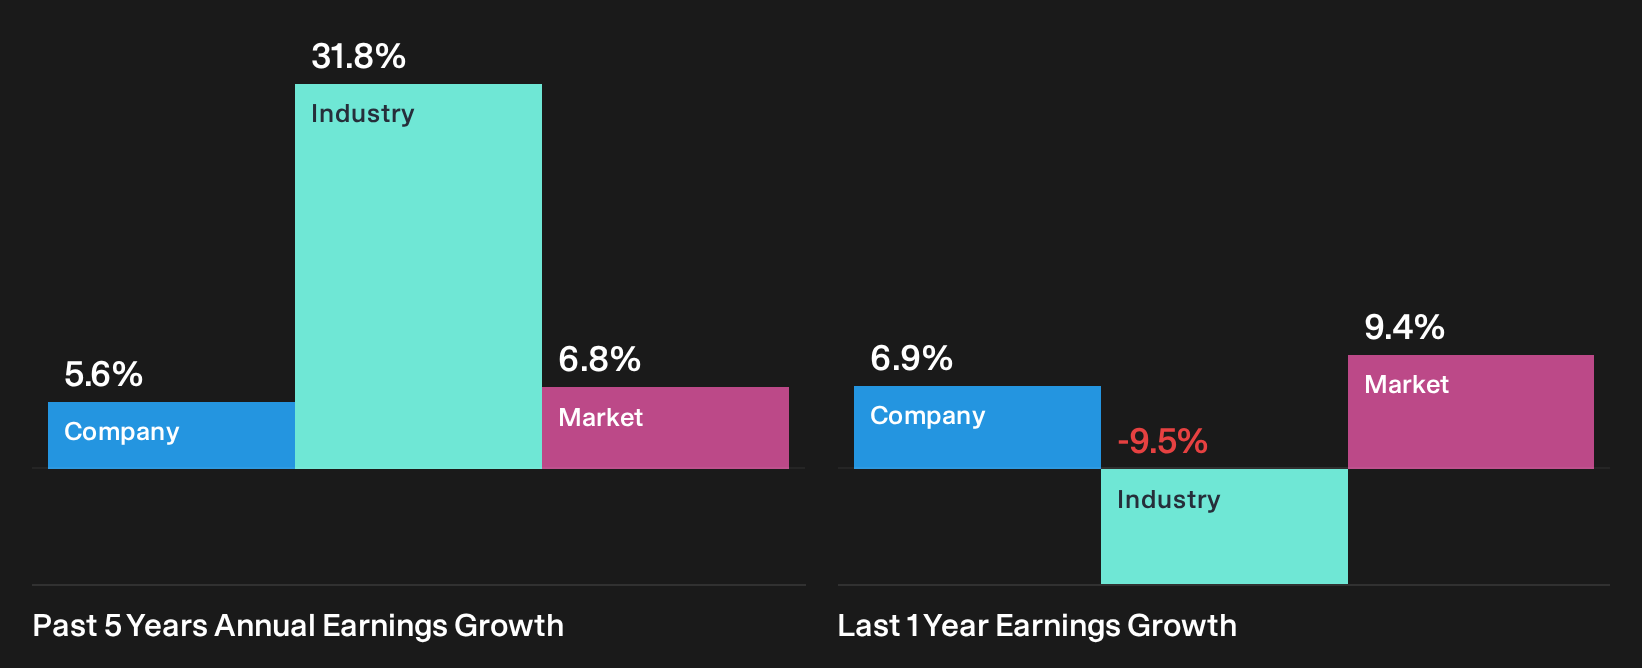
BAE Systems (LSE:BA.)
Overview: BAE Systems is a global defence and aerospace contractor supplying combat vehicles, munitions, naval support and security systems under long-term government contracts that underpin recurring cash flows.
Operations: BAE Systems generates most of its revenue from Electronic Systems at £7.8b, Air at £7.7b, Maritime at £6.7b, and Platforms & Services at £5.3b, supported by Cyber & Intelligence and headquartered functions.
Market Cap: £54.3b
BAE Systems fits the cash flow focused theme through its Platforms & Services work, where long-term combat vehicle and naval support contracts can translate large defence commitments into more predictable income streams for investors.
"The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific. This provides visibility on future revenues and supports the potential for sustained topline growth over multiple years."
The real swing factor is what happens if a single assumption about future defence procurement cycles shifts, up or down.
If that procurement cycle swing is what you are focused on, the full narrative for BAE Systems explains how shifting orders, cash generation and valuation expectations could rapidly decouple.
Seeking Fresh Alternatives Before They Fly
Some of the most interesting shares move from quiet to breakout before most investors even notice. Scan these fresh shortlists while they are still under the radar for now and consider your options promptly.
- Spot cash rich compounders early and track the curated list of solid balance sheet and fundamentals (9 results) before momentum traders start chasing the same resilient balance sheets.
- Ride structural themes in real assets and infrastructure by checking the hand picked 40 power grid technology and infrastructure stocks while valuations still reflect earlier cycle expectations.
- Target potential high yield anchors for your portfolio and review the focused 1 dividend fortresses before payout ratios and share prices get fully caught up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com