
Synopsys (SNPS) Signs AI Deals With OpenAI And Amazon, Is The Upside Already Priced In?
Synopsys (SNPS) just signed multi year collaborations with OpenAI and Amazon focused on AI driven chip design workflows, a cluster of events that pushed the stock up about 4.8% on the day.
The Synopsys share price has picked up momentum recently, with a 7 day share price return of 15.06% and a 30 day gain of 17.77%. However, year to date the share price return is 1.97% and the 1 year total shareholder return is 4.42%, pointing to stronger short term enthusiasm than longer term results.
Spot fresh AI-fuelled opportunities around Synopsys by scanning our hand picked 90 AI infrastructure stocks, which features companies that are building the chips, tools, and grid behind next generation models.Synopsys is suddenly priced for big AI expectations after a sharp 30 day run, so the next step is simple. Are investors still early, or did most of the easy upside already get used up?
Most Popular Narrative: 10% Undervalued
Against a last close of $489.90, the most followed Synopsys narrative pins fair value at $545.93 using a 9.0% discount rate. This points to investors paying below that story driven estimate today.
The acquisition and integration of Ansys positions Synopsys as the global leader in engineering solutions from silicon to systems, and new data showing Q3 FY26 Ansys revenue of about US$711 million and an expected FY26 contribution of about US$2.98 billion supports the view that this expanded portfolio can continue to influence top line growth and operating earnings as cross sell opportunities scale.
See why 162 investors see Synopsys as 10% undervalued.
Result: Fair Value of $545.93 (UNDERVALUED)
Still, the Synopsys story can break if Ansys integration drags on costs, or if muted Design IP momentum undercuts the AI heavy growth narrative.
Find out about the key risks to this Synopsys narrative.
Another View: Synopsys Through The P/E Lens
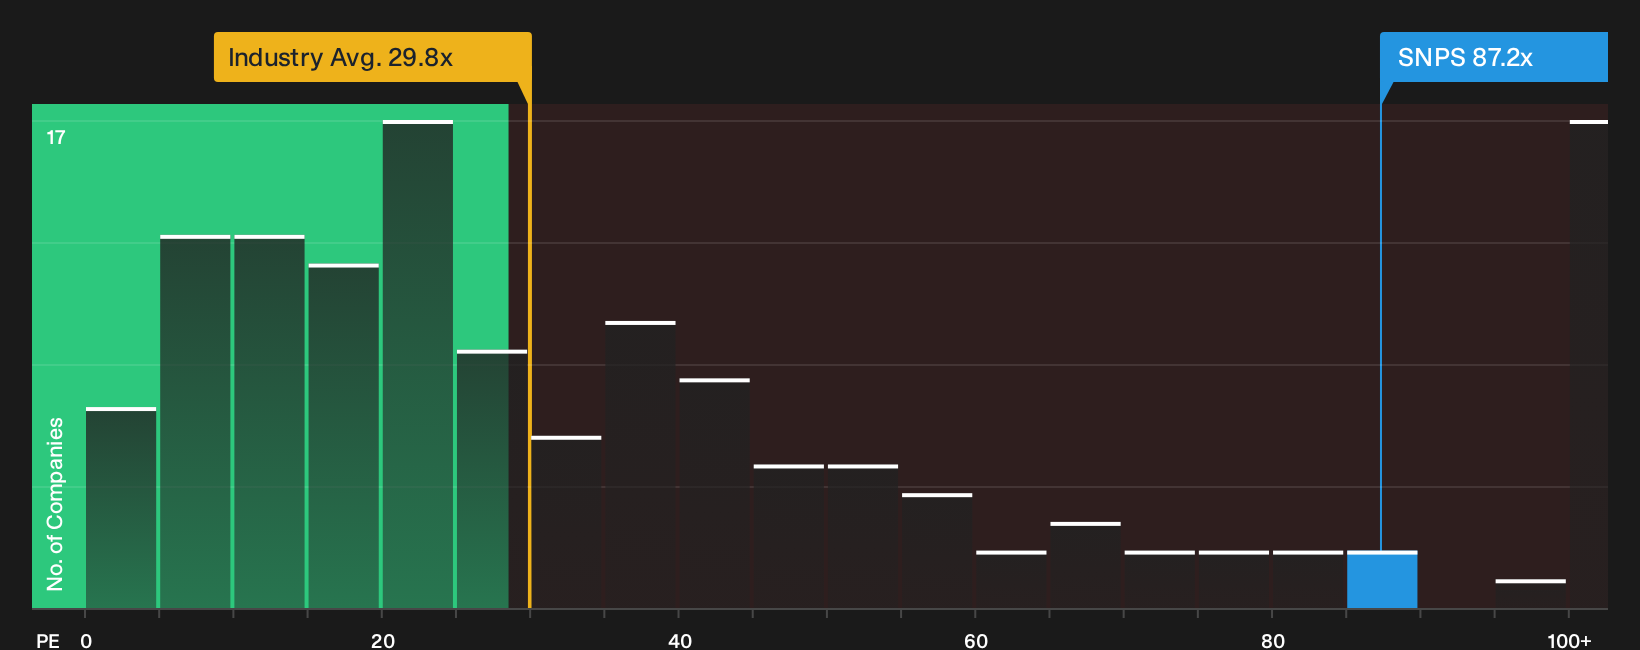
On the other side of the ledger, Synopsys trades on a P/E of 87.2x, compared with 29.8x for the wider US Software group and a peer average of 33.8x. The fair ratio sits at 47.8x, which signals a wide valuation gap that could either compress sharply or stay elevated for longer.
That kind of premium can reward investors if earnings keep meeting high expectations, but it also raises the risk that a bump in execution or sentiment hits the share price harder than the fundamentals alone might suggest. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Synopsys now carries both excitement and caution in the story. If you want to move fast and rely on your own judgment, start with the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Synopsys?
If Synopsys has sharpened your focus on where capital could work harder, do not stop here. A wider watchlist often reveals opportunities others miss.
- Target potential mispricings by scanning companies on our 31 high quality undervalued stocks, where solid fundamentals meet prices that may not fully reflect them yet.
- Build a steadier income stream by reviewing the 7 dividend fortresses, focusing on businesses offering higher yields alongside resilience.
- Strengthen your downside protection by running through the 31 resilient stocks with low risk scores, which highlights stocks with more robust risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com