
Is Texas Roadhouse (TXRH) Undervalued As Its Shares Slide And Fair Value Debate Builds?
Texas Roadhouse (TXRH) has drawn fresh attention after a sharp pullback, with the share price down about 18% over the past month and roughly 20% over the past 3 months.
For context, Texas Roadhouse shares are now at $156.14, with momentum fading over the past quarter. The 1 year total shareholder return is modestly negative, while the 3 and 5 year total shareholder returns remain strongly positive.
Scan how Texas Roadhouse compares with other consumer stocks under pressure and see which ones still screen well on quality using the 31 high quality undervalued stocks.
The recent slide now leaves Texas Roadhouse trading at a sizeable discount to both analyst targets and intrinsic estimates. Is that a cautious market correctly re-pricing risk, or a valuation gap worth studying closely?
Most Popular Narrative: 28% Undervalued
On the most followed view of Texas Roadhouse, the implied fair value of about $217.54 sits well above the recent $156.14 close. This puts the recent pullback into sharper context for anyone weighing the risk reward trade off.
The current valuation implies the market may be underestimating the long term earnings power of Texas Roadhouse if its traffic, unit growth plans, and cash returns to shareholders persist while margin pressures ease over time.
Robust operating cash flow of more than US$730 million in 2025 funding capex of US$388 million, franchise acquisitions, a rising dividend of US$0.75 per share each quarter, and buybacks shows Texas Roadhouse has capacity to keep investing in growth while returning cash. This can support future earnings per share through both higher profits and a potentially lower share count.
See why 55 investors see Texas Roadhouse as 28% undervalued.
Result: Fair Value of $217.54 (UNDERVALUED)
Still, the Texas Roadhouse narrative can crack if beef inflation keeps squeezing restaurant margins or if heavy unit expansion spending fails to generate the expected cash returns.
Find out about the key risks to this Texas Roadhouse narrative.
Another View: Texas Roadhouse Through A P/E Lens
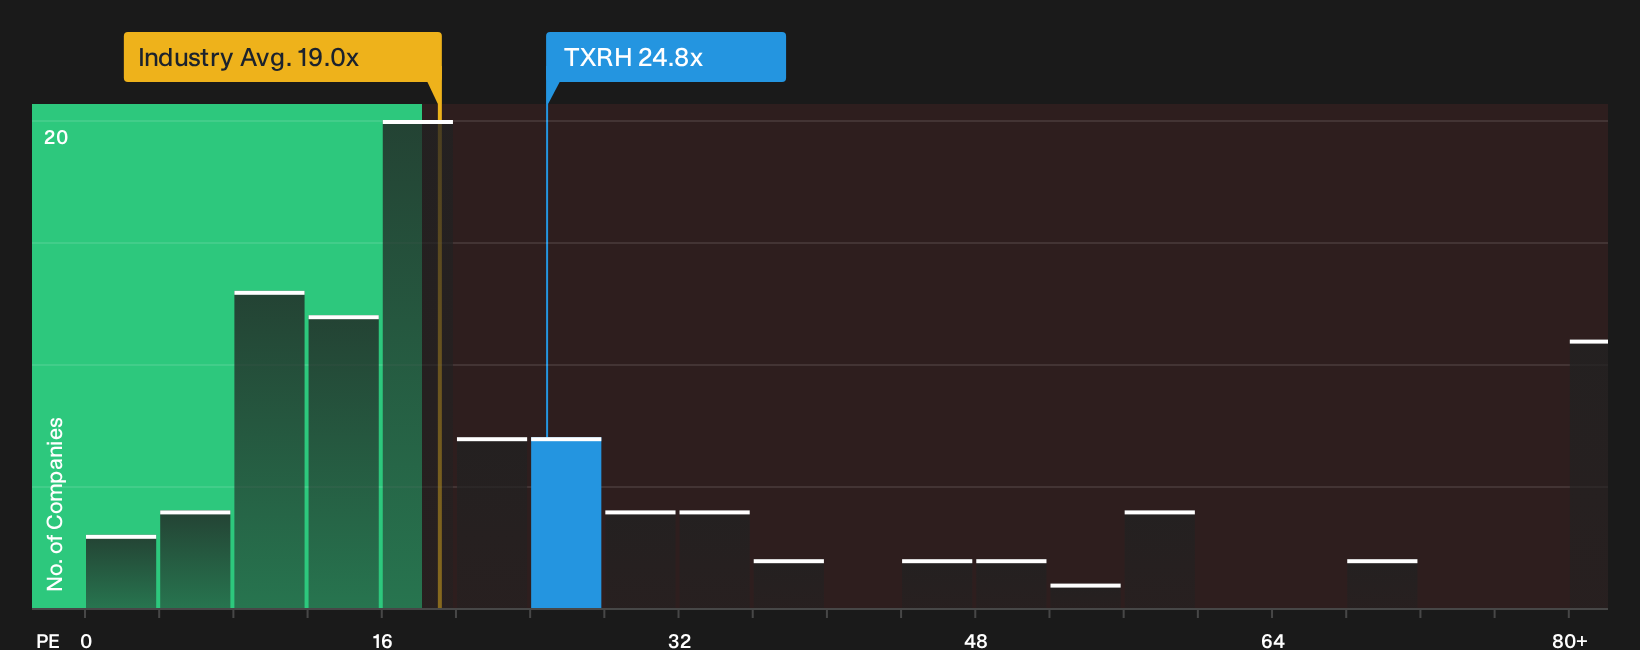
The story looks different once Texas Roadhouse is viewed through its P/E ratio. The shares trade around 24.8x earnings, which is higher than the US Hospitality industry on 19x and above a fair ratio estimate of 21.4x. That richer tag can matter if sentiment cools again.
For anyone weighing what that premium multiple might signal about risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Texas Roadhouse so far, with clear concerns alongside real optimism about future rewards, mean you should move fast and weigh both sides using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Texas Roadhouse?
If Texas Roadhouse has your attention, you owe it to yourself to scan a wider field of opportunities that fit your risk level and income goals.
- Target resilient income by reviewing a curated set of high yield opportunities through the 7 dividend fortresses that already clear strict financial filters.
- Hunt for sturdier balance sheets by running through the list of solid balance sheet and fundamentals (26 results) so you are not relying on leverage to power returns.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems that combine strong fundamentals with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com