
Biofrontera Inc. (NASDAQ:BFRI): Are Analysts Optimistic?
We feel now is a pretty good time to analyse Biofrontera Inc.'s (NASDAQ:BFRI) business as it appears the company may be on the cusp of a considerable accomplishment. Biofrontera Inc., a biopharmaceutical company, engages in the commercialization of pharmaceutical products for the treatment of dermatological conditions in the United States. The US$15m market-cap company posted a loss in its most recent financial year of US$11m and a latest trailing-twelve-month loss of US$6.4m shrinking the gap between loss and breakeven. The most pressing concern for investors is Biofrontera's path to profitability – when will it breakeven? Below we will provide a high-level summary of the industry analysts’ expectations for the company.
Biofrontera is bordering on breakeven, according to the 2 American Pharmaceuticals analysts. They expect the company to post a final loss in 2026, before turning a profit of US$2.6m in 2027. The company is therefore projected to breakeven just over a year from today. In order to meet this breakeven date, we calculated the rate at which the company must grow year-on-year. It turns out an average annual growth rate of 66% is expected, which is extremely buoyant. Should the business grow at a slower rate, it will become profitable at a later date than expected.
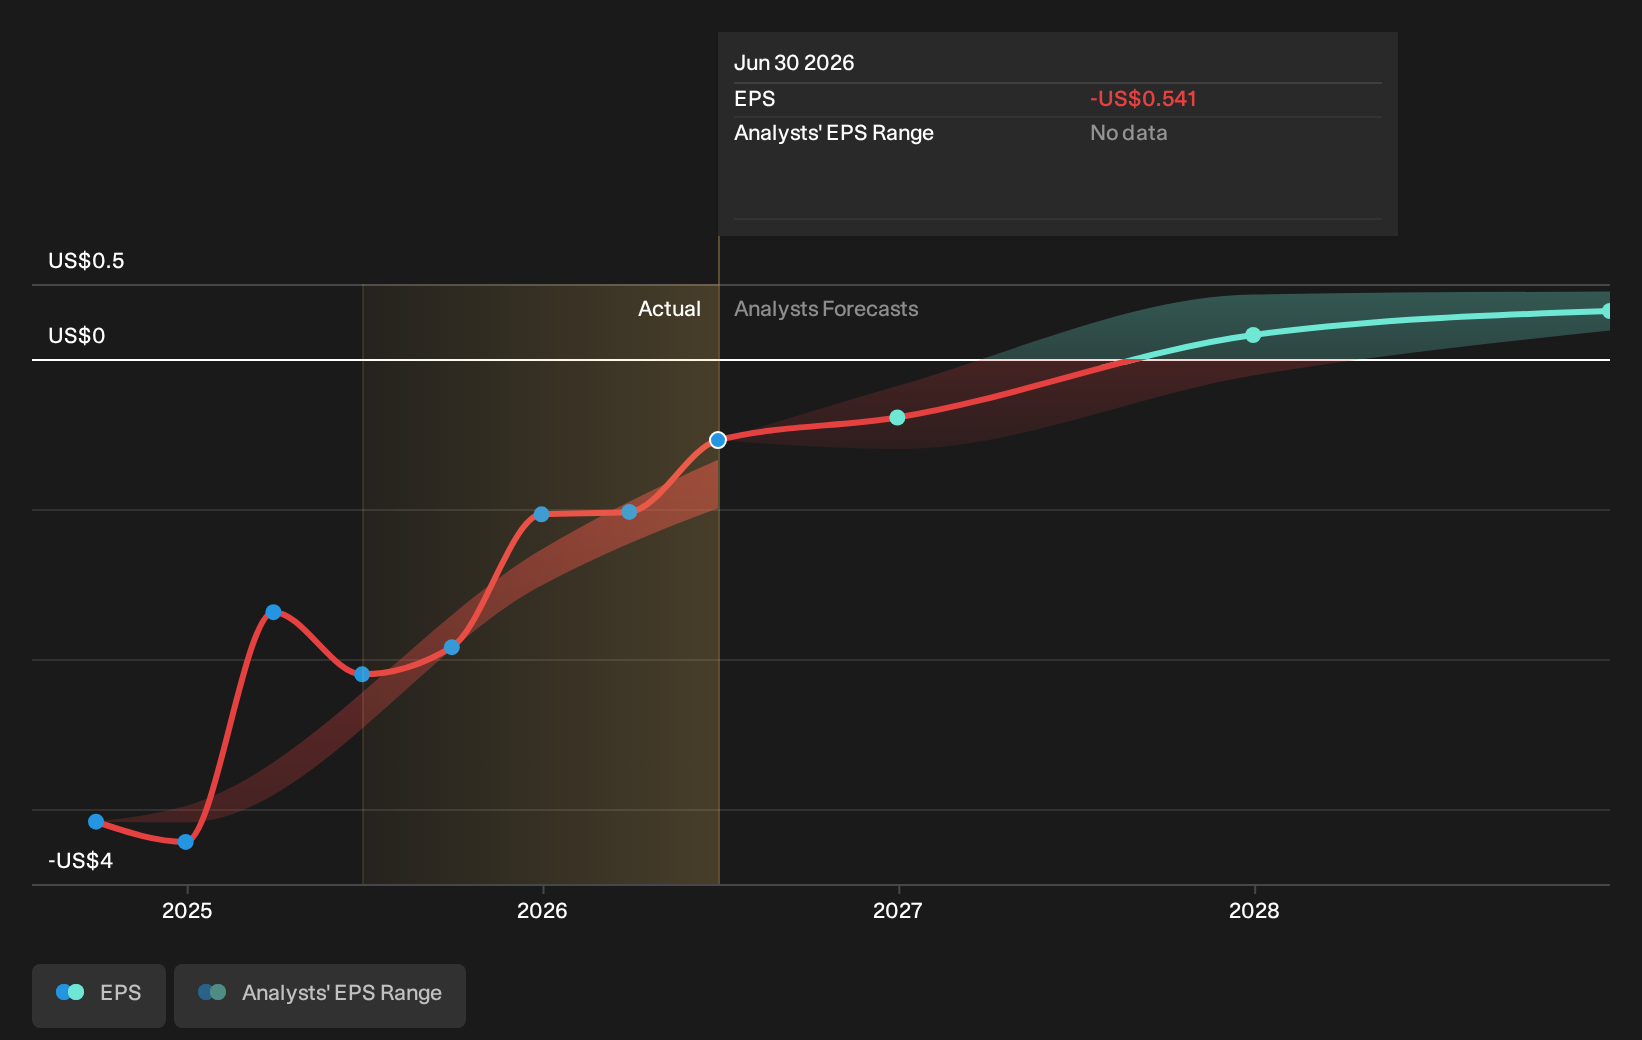
We're not going to go through company-specific developments for Biofrontera given that this is a high-level summary, though, take into account that generally a pharma company has lumpy cash flows which are contingent on the drug and stage of product development the business is in. This means, large upcoming growth rates are not abnormal as the company is beginning to reap the benefits of earlier investments.
Check out our latest analysis for Biofrontera
Before we wrap up, there’s one issue worth mentioning. Biofrontera currently has a relatively high level of debt. Typically, debt shouldn’t exceed 40% of your equity, which in Biofrontera's case is 78%. A higher level of debt requires more stringent capital management which increases the risk in investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Biofrontera, so if you are interested in understanding the company at a deeper level, take a look at Biofrontera's company page on Simply Wall St. We've also put together a list of relevant aspects you should further examine:
- Valuation: What is Biofrontera worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Biofrontera is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Biofrontera’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.