
What You Can Learn From ON Semiconductor Holders Up 72%
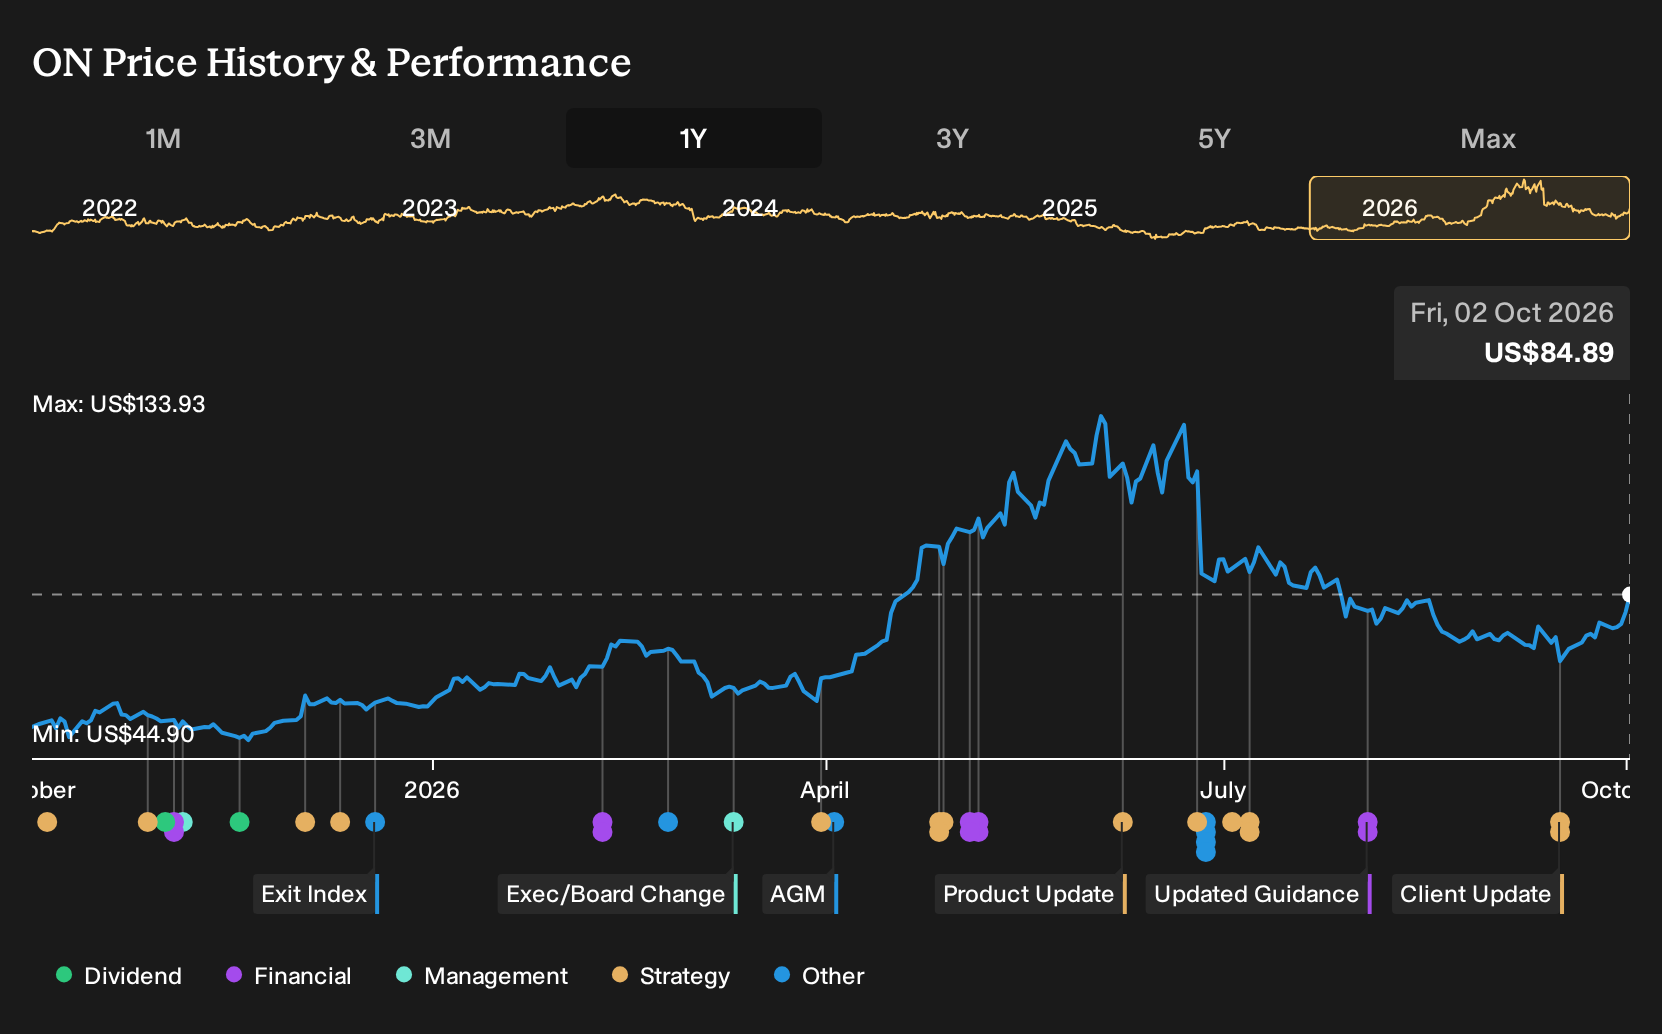
If ON Semiconductor sat on your watchlist instead of in your portfolio, the recent move may feel like a missed shot. Investors who held ON Semiconductor over the past year are up 72.3%, including dividends. That outcome invites a tougher question. Back on 2 October 2025, with bulls focused on EV and AI demand in China and bears worried about tariffs and margin pressure, what business mix assumption could have helped you judge which side of that split story mattered more?
This theme extends beyond ON Semiconductor. See which of 90 AI infrastructure stocks may still merit a closer look.
The Two ON Semiconductor Stories Investors Had To Weigh
The shares cost US$48.74 at the start of the period, and ON Semiconductor sat between two very different but plausible stories about where its mix of EV, AI and legacy products might head next.
On the upbeat side, the bull narrative pointed to a fair value of US$57.73, an implied upside level based on expectations that silicon carbide and AI data center power products would take a larger share of revenue.
The bear narrative anchored on a fair value of US$38.50, built around the risk that tariffs and supply chain localization could lift manufacturing costs in China and compress margins despite EV demand.
What The Results Changed In The ON Semiconductor Debate
ON Semiconductor’s Q2 2026 report showed revenue of US$1,603.5 million and net income of US$226.8 million, with net margin at 14.1% versus 11.6% a year earlier. That profitability shift backed the bullish focus on mix and efficiency improvements. The planned Synaptics deal, and later revision to an all cash structure, gave the cautious case fresh questions around integration risk and capital allocation. Overall, the evidence cut both ways.
The key lesson is simple. When a story leans on “better mix”, treat it as a claim you can track. Watch whether net margin and segment exposure actually move in the direction that thesis needs, and test any major acquisition against that same profit line.
What ON Semiconductor's Price Already Assumes
ON Semiconductor now trades at US$84.89, well above where it started one year ago. The selected Narrative’s Fair Value sits below the current price, built around the idea that AI data center power, automotive silicon carbide and the Synaptics deal may not fully deliver on ambitious plans.
A buyer today effectively banks on ON Semiconductor turning current design wins and capacity into the kind of utilization and cash generation implied in that gap. The question is how the Narrative’s concern about slower customer adoption and integration risk might affect that assumption if it plays out differently than hoped.
"The numbers indicate that ON Semiconductor’s share price already reflects a valuation that assumes meaningful success on AI data center growth, automotive content gains, Fab Right margin improvement and the planned Synaptics integration."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 36% below our estimate - leans on data center and mega-project awards to sustain e-infrastructure project backlog.
- Company 2 - 42% below our estimate - builds a recommerce network where trade-in subsidies support recurring device refurbishment demand.
- Company 3 - 27% below our estimate - expands high horsepower engine capacity to serve contracted data center power requirements.
That is three of the list. See all 31 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com