
How Camo Packaging Launch At Boston Beer Company (SAM) Has Changed Its Investment Story
- Boston Beer Company recently rolled out a limited-edition fall collaboration that puts Realtree APX camouflage designs on select Twisted Tea Original multi-pack wraps and a 24 oz can, supported by a matching camo-themed merchandise line.
- This tie-up targets outdoor-focused drinkers with coordinated packaging and gear, which could influence Twisted Tea brand engagement and seasonal demand patterns across Boston Beer Company's portfolio.
- The focus now shifts to how Boston Beer Company's Realtree camo Twisted Tea collaboration might influence the broader investment narrative around product innovation.
Boston Beer Company Investment Narrative Recap
To own Boston Beer Company, you need to believe that its mix of hard teas, seltzers, beer, cider and spirits can stay relevant even as parts of the alcohol category mature and moderation trends build. The key short term swing factor is whether demand across Twisted Tea, Truly and newer lines like Sun Cruiser supports the path back to profitability that analysts are modeling.
The Realtree Twisted Tea collaboration looks incremental rather than transformational. It speaks to brand heat and marketing execution more than core financial change. The bigger risk still sits in over reliance on hit driven Beyond Beer products in crowded shelves, which could keep volumes choppy and pressure marketing spend and margins.
The Realtree tie up sits next to earlier work on Twisted Tea Light and Truly Unruly high ABV extensions that analysts already highlight as important product activity for Boston Beer Company. Those moves collectively point to a portfolio skewed toward flavored, higher margin line extensions that analysts expect to support earnings growth if consumer interest holds.
For catalysts, investors are watching whether these product families scale without triggering heavy discounting or operational complexity. The Realtree run gives Boston Beer another test of how quickly it can execute limited editions across packaging, merchandising and distribution, which matters if the firm continues to depend on frequent concept refreshes to support volumes in a low top line growth backdrop.
Boston Beer Company's narrative projects US$1.9b revenue and US$107.3 million earnings by 2029. This implies revenue staying broadly flat and an earnings swing of about US$177.7 million, moving from a loss of US$70.4 million today to the forecast consensus level.
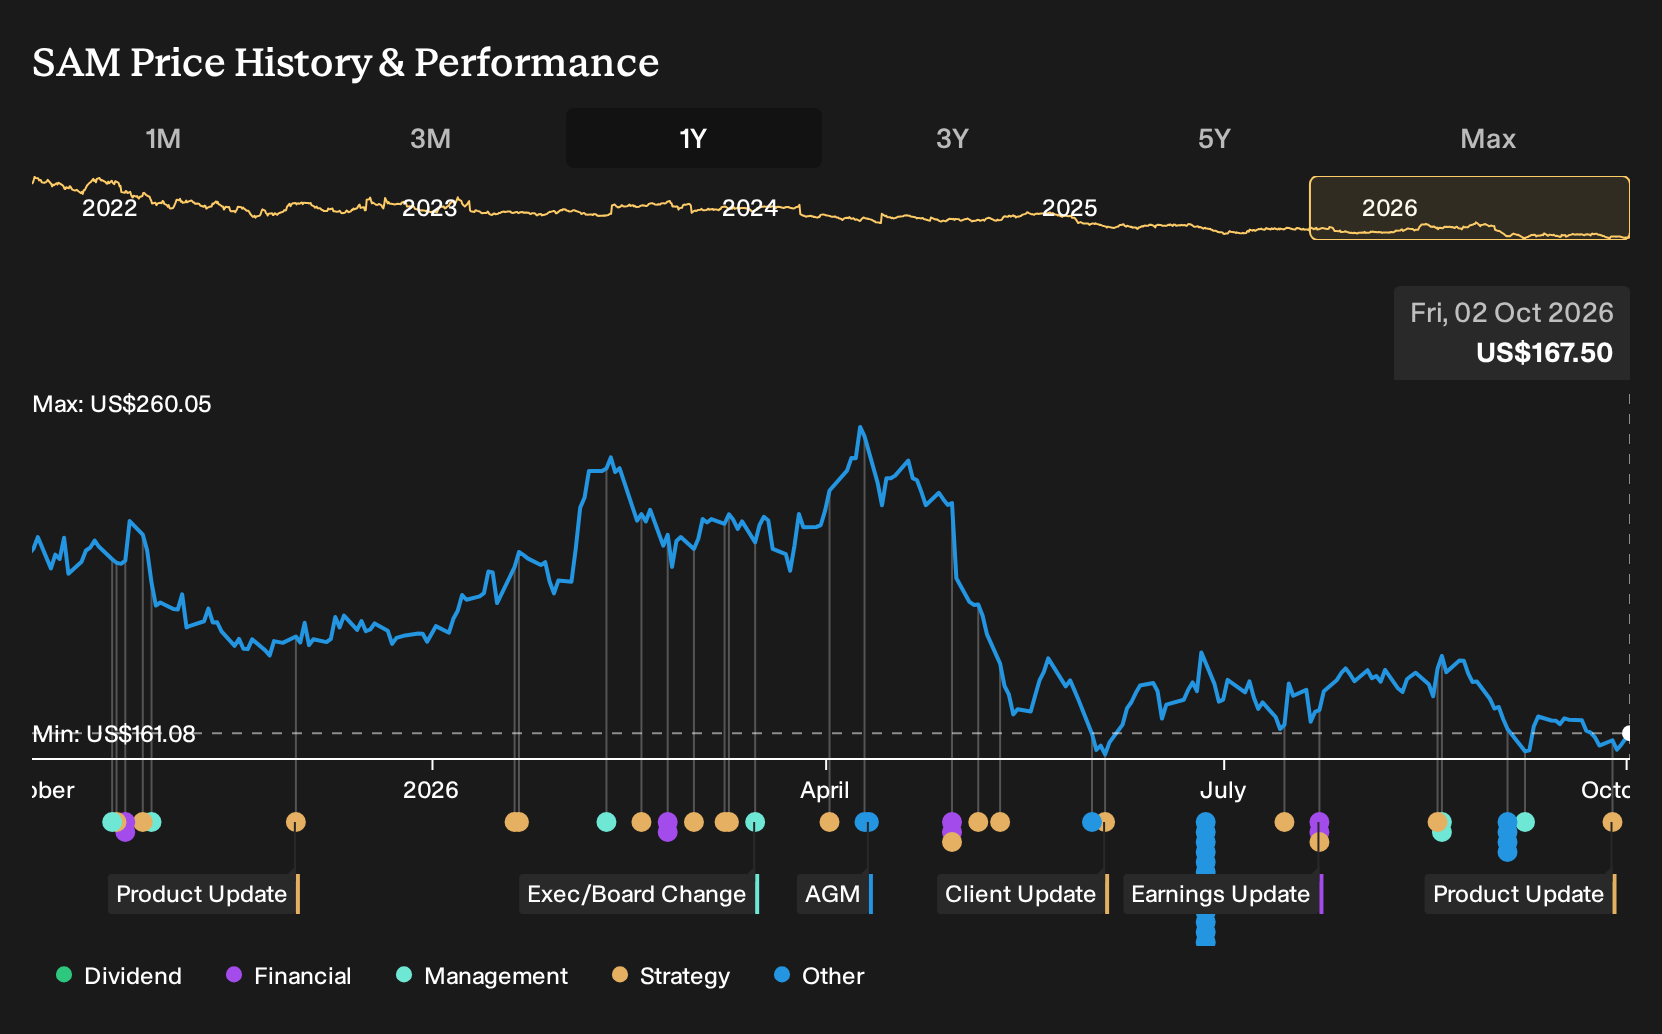
Uncover why Boston Beer Company's fair value indicates a 19% potential upside to its current price, which could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
One alternate view focuses on volume pressure rather than product buzz. Bearish analysts, looking at recent shipment and depletion data, already expected Boston Beer Company revenue to decline 1.3% a year and still only reach about US$1.8b with US$128.7 million earnings by 2029. You can see how far opinions stretch and decide whether this Realtree launch shifts your own stance.
Explore 2 other Boston Beer Company fair value estimates, including one that suggests it could be worth just $199.85.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boston Beer Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Boston Beer Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Beer Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boston Beer Company?
If the Boston Beer Company story has you thinking about what else might be hiding in plain sight, it can help to scan a wider field of candidates and compare their fundamentals side by side.
- For investors hunting for resilient balance sheets that can better absorb shocks, start with this curated list of solid balance sheet and fundamentals (26 results) and filter for businesses that match your risk profile.
- If capital preservation and steadier income matter most to you, use the 7 dividend fortresses to pinpoint companies that pair higher yields with stronger underlying financials.
- When you want new ideas that have not yet become crowded trades, tap into the 19 high quality undiscovered gems and surface under-followed stocks backed by solid numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com