
Will Exclusive Brand Launches Change Ulta Beauty's (ULTA) Narrative
- In late September 2026, partners Wavytalk and Flower Knows announced expanded US distribution through Ulta Beauty, moving from Ulta.com into hundreds of physical stores with curated assortments and Ulta exclusive products and colorways.
- This push into exclusive tools and limited run color cosmetics provides Ulta Beauty with fresh, differentiated inventory that can appeal to trend driven shoppers while supporting its focus on emerging brands and experiential in store browsing.
- We will now examine how Ulta Beauty's deeper exclusive brand partnerships could influence the broader investment narrative for the retailer.
Ulta Beauty Investment Narrative Recap
To own Ulta Beauty, you need to believe the retailer can keep using exclusive brands, wellness and loyalty to support steady earnings while absorbing higher costs and the coming loss of the Target shop in shops. The short term focus is on how effectively store traffic, e commerce and new categories can support margins that have recently softened.
The biggest risk right now is that higher payroll, rent and benefits, together with elevated SG&A from international and digital projects, squeeze profitability faster than revenue builds. The latest Wavytalk and Flower Knows news looks helpful for differentiation, although on its own it does not look large enough to change that risk balance.
The Wavytalk in store rollout is the clearest indicator for the current catalyst. Ulta Beauty is leaning hard into exclusive colorways, hero tools and curated assortments that are only found in its aisles. For you as a shareholder, the real question is whether those differentiated items translate into larger baskets and sustained store visits.
If this partnership scales well, it supports the view that Ulta can refresh its assortment with emerging brands, keep younger shoppers engaged and partially offset pressure from e commerce and the Target exit. Execution risk lies in product selection, inventory turns and how efficiently stores support these higher touch categories without pushing operating costs uncomfortably higher.
Ulta Beauty's current analyst narrative points to revenues of US$14.9b and earnings of US$1.4b by 2029, based on an assumed 5.4% yearly top line growth rate and an earnings increase of US$0.2b from US$1.2b today.
Uncover why Ulta Beauty's fair value indicates a 15% potential upside to its current price before rising expectations close that discount.
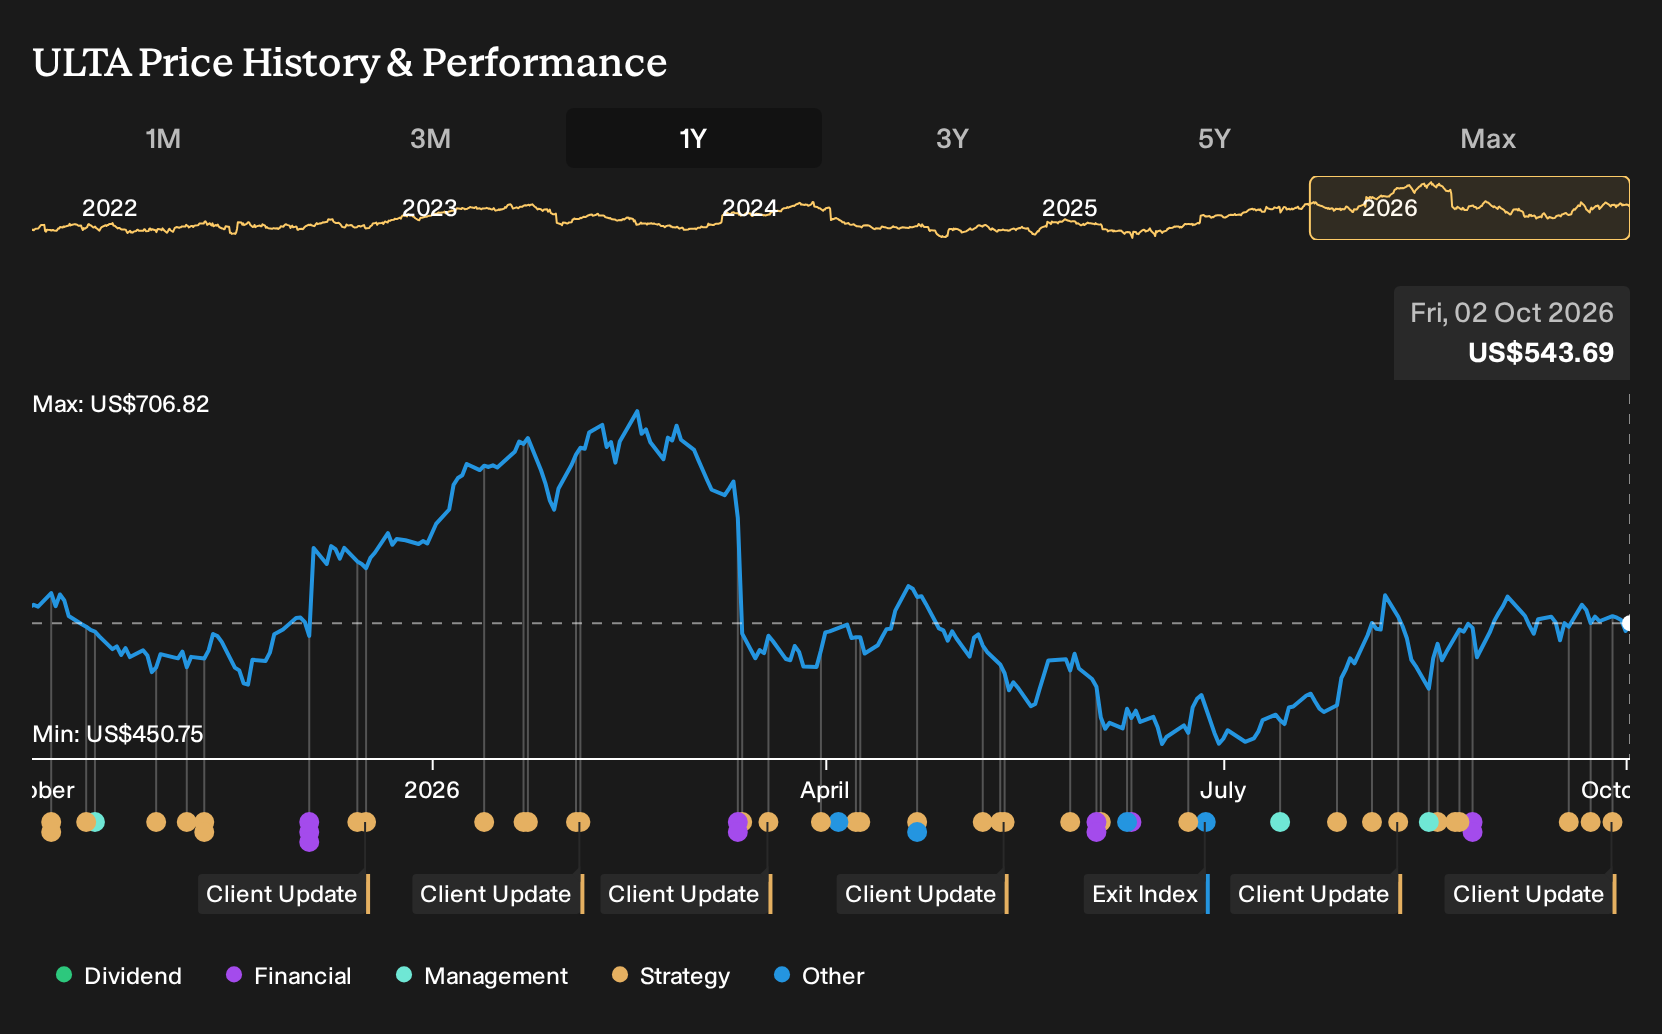
Exploring Other Perspectives
Some of the most optimistic analysts frame Ulta Beauty’s exclusive brand push as a way to deepen loyalty economics. They were already penciling in revenue of about US$15.4b and earnings of roughly US$1.5b by 2029, well above consensus, before the Wavytalk and Flower Knows news, which could prompt fresh revisions in either direction.
Explore 6 other Ulta Beauty fair value estimates, including one that suggests up to 17% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ulta Beauty research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ulta Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ulta Beauty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ulta Beauty?
Once you have a view on Ulta Beauty, it can help to scan a wider field of opportunities so your portfolio is not tied to a single retail story.
The Simply Wall St Screener lets you filter companies by fundamentals, risk profile and income focus so you can quickly spot shares that fit your own criteria.
- If you want potential mispricing backed by fundamentals, start with a curated set of 31 high quality undervalued stocks that combine quality metrics with attractive pricing signals.
- For investors who care most about resilience, you can filter for balance sheets that look robust using our focused list of solid balance sheet and fundamentals (26 results) to see which businesses may be better positioned to handle bumps in the road.
- If income is your priority, use the Screener to narrow in on income opportunities via a hand picked group of 7 dividend fortresses that clear a 5% threshold.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com