
Metrolinx Bus Order Expansion Could Be A Big Test For NFI Group Stock
- NFI Group's subsidiary Motor Coach Industries expanded its agreement with Metrolinx, adding 47 extra 45 foot D45 CRT diesel commuter coaches to an existing order, indicating stronger demand for its commuter coach lineup.
- The enlarged Metrolinx order underlines how committed public transit buyers remain to NFI Group's diesel commuter platform even as zero emission buses gain attention. This matters for fleet mix, production planning, and aftermarket revenue potential.
- We will look at how NFI Group's expanded Metrolinx commuter coach order fits, or clashes, with the existing investment narrative.
Scan how NFI Group's Metrolinx win compares with other transit and infrastructure plays by reviewing our hand picked 40 power grid technology and infrastructure stocks aligned with long term public transport and grid spending themes.
NFI Group Investment Narrative Recap
For someone holding NFI Group, the key view is that a record multiyear backlog of over $13.5 billion, normalizing operations, and growing aftermarket services can support steadier cash generation. The Metrolinx diesel coach expansion contributes to that backlog story and near-term factory utilization, but it does not reshape the investment case on its own.
The more significant near-term swing factor remains execution against that backlog while carrying high leverage, with interest costs still substantial relative to earnings. Any stumble in production efficiency, tariff recovery, or pricing could pressure margins and debt metrics more than this one incremental order can offset.
There have been no other recent announcements listed alongside the Metrolinx news, so the most relevant reference point is still the earlier disclosure of a large order book and operational improvements. The Metrolinx add-on fits within that broader narrative of contracts converting and options being exercised across North American transit agencies.
For catalysts, the focus is on how consistently NFI Group converts that $13.5 billion-plus backlog into on-time deliveries and cleaner earnings, especially after one-off gains that affected recent results. Execution against funded government programs and the mix between internal combustion and zero-emission vehicles will likely matter more for margins and leverage than any single commuter coach order.
NFI Group's current analyst narrative points to about $4.7b in revenue and $296.1m in earnings by 2029, based on an assumed 7.9% yearly revenue growth rate and an earnings move from $54.0m today to that $296.1m level, which is roughly a 5.5x increase in profit.
Discover why NFI Group's fair value indicates a 25% potential upside to its current price that may not last much longer.
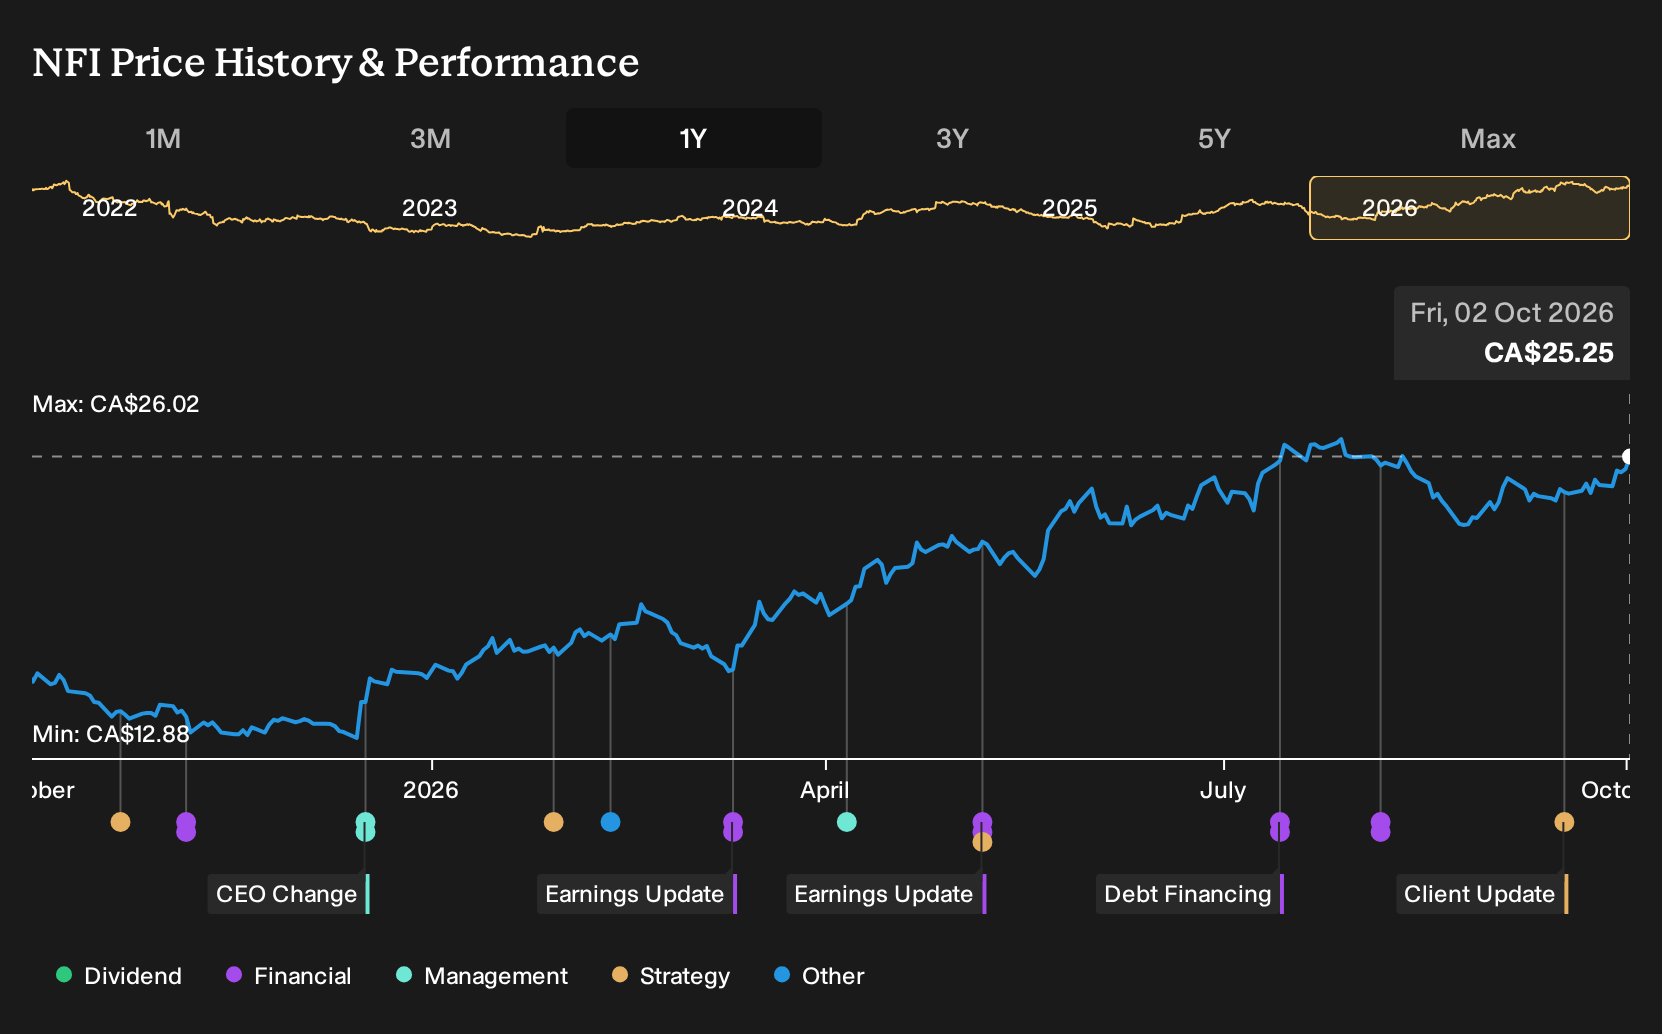
Exploring Other Perspectives
NFI Group looks very different through the more cautious lens. The lowest analysts worry that supplier bottlenecks and the US$229.9 million recall provision could keep cash tight, even if earnings eventually reach about US$286.6 million on roughly US$4.6 billion of revenue by 2029. They published those estimates before this Metrolinx expansion, so you may want to compare both narratives and decide which feels closer to your own view.
Explore 3 other NFI Group fair value estimates, including one that suggests it could be worth just CA$28.49.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NFI Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NFI Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NFI Group's overall financial health at a glance.
Looking for more investment ideas beyond NFI Group?
If the NFI Group story has sharpened your thinking and you want to widen your watchlist, the Simply Wall St Screener can help you scan for other opportunities that fit different risk and return profiles.
- For investors who want potential upside with smaller market capitalizations, consider reviewing 17 elite penny stocks with strong financials that meet tighter financial quality filters.
- If resilience and balance sheet strength matter most to you, filter for companies in the list of solid balance sheet and fundamentals (7 results) and see which ones match your preferred risk profile.
- When you want growth potential that is not already crowded, check out the 9 high quality undiscovered gems and see which ideas deserve a place on your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com