
Why The Bull Case For TFI International Was Never The Easy One
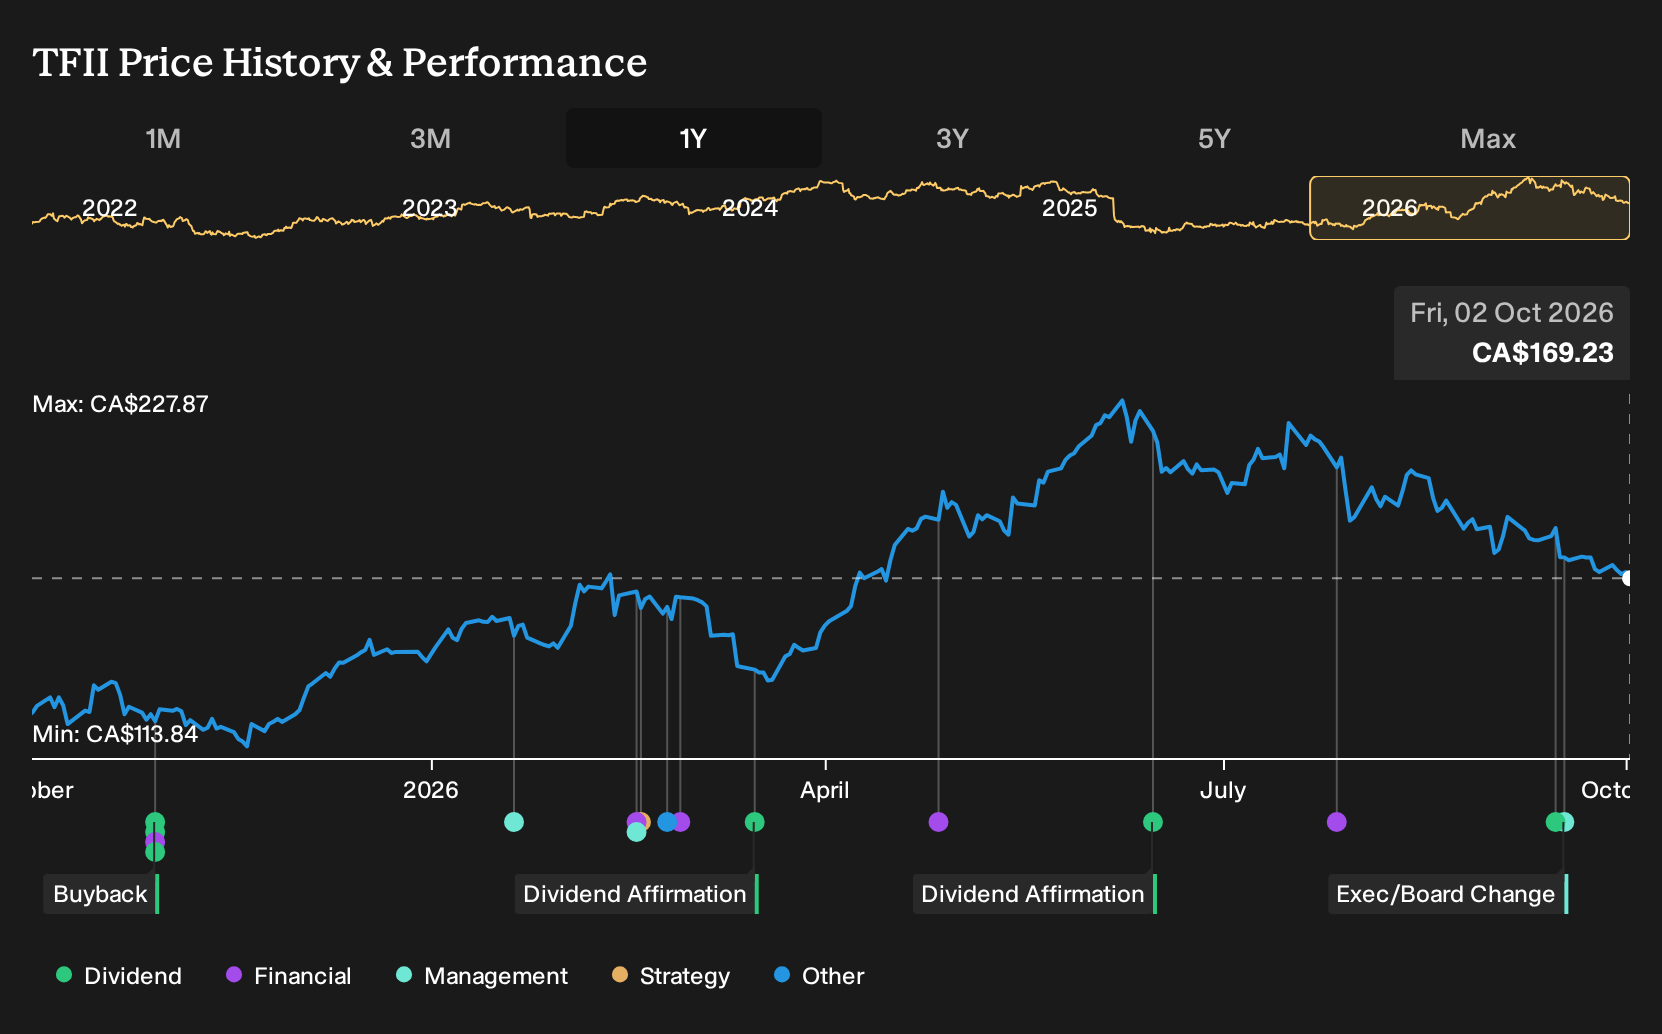
If TFI International was on your watchlist rather than in your portfolio, the recent move may feel expensive in hindsight. For TFI International shareholders, the return over the past year was 35.2%, including dividends. That outcome invites a tougher question. Back on 2 October 2025, what clues in the cross-border freight thesis and the focus on digital efficiency could have helped you judge whether those operational bets would actually translate into better earnings power?
The easy part of this move is behind TFI International. Zero in on 6 high quality undervalued stocks for companies trading below our estimates.
The Two Futures TFI International Investors Had To Price In
The shares cost CA$125 at the start of the period, so any thesis on TFI International had to answer whether that tag already reflected the big cross-border and technology story.
The bullish narrative pointed to a Fair Value of CA$141, a rough guide to what that story implied if it played out, built on 3.6% annual revenue growth and profit margins reaching 6.1% within three years.
The bearish camp argued for a Fair Value of CA$96.4, anchored in worries about autonomous delivery, decarbonization costs, and tighter regulation straining freight operations and cash generation.
What The Results Changed For The TFI International Thesis
The Q2 2026 report gave TFI International investors a clean checkpoint. Revenue was US$2.29b versus US$2.04b a year earlier, net income moved from US$98.18m to US$136.15m, and net margin shifted from 4.8% to 5.9%. That pattern supported the optimistic cross-border and efficiency case, although persistent LTL pricing and margin pressure kept the cautious story alive. Overall, the evidence cut both ways.
The lesson is simple. When a freight thesis leans on efficiency, do not only watch volume. Track net margin and segment-level operating ratios to see whether talk about digital tools and better freight mix is actually turning into earnings power.
What TFI International's Recent Run Now Asks You To Believe
TFI International now trades at CA$169 after a 35.2% gain over the past year. The selected Narrative places its Fair Value above that price and leans on truckload margins, tighter capacity, and efficiency work as the engine behind that view.
Instead of broad freight strength, the Narrative leans heavily on future benefit from reshoring trends, higher quality LTL business, and better free cash flow that today’s quote may not fully credit.
"Rising domestic and cross-border freight activity driven by North American reshoring/nearshoring and potential resolution of tariff uncertainties is expected to unlock volume growth, especially for profitable U.S.-Canada LTL trade lanes and specialized truckload; this will boost revenue and operating earnings as the macro cycle turns."
One Narrative disagrees with today's price. → See where this Narrative says TFI International should trade
Where TFI’s Freight Thesis Connects Next
Watching TFI International has you thinking about freight efficiency and cash generation. The next step is seeing who else pulls on those levers.
One large digital freight platform now turns marketplace traffic into meaningful free cash flow. It is also putting serious money into autonomous vehicles and fleet access.
The business question looks different from TFI International, yet still rhymes with it. Both depend on dense networks and smarter routing to improve cash economics.
What remains open is who keeps more value if driverless freight and ride networks spread. That answer could reshape where freight efficiency gains ultimately land.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 70% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com