
3 Rate Sensitive US Stocks Retail Investors Are Watching After Treasury Yields Jump
Rates have become the main character again. A softer September jobs report, cooler Fed hike odds, and stubbornly high Treasury yields are pulling money across the market like a strong tide. That mix creates potential mispricing in smaller, rate-sensitive U.S. stocks, where sentiment can swing faster than fundamentals. This article walks through three such stocks exposed to the latest macro shock and explains why the reaction might matter for your portfolio.
The three stocks that follow are just a starter set. The full rate-sensitive screen surfaced 15 more U.S. small and mid caps with similarly detailed stories that are not covered here. To go straight to the full universe and start to identify, analyze, and rank your own highest conviction ideas, head into the U.S. Small- and Mid-Cap Rate-Sensitive Stocks screener.
Atkore (ATKR)
Overview: Atkore manufactures electrical conduit, cable management and infrastructure products that feed directly into non-residential construction, data centers and broader U.S. infrastructure projects.
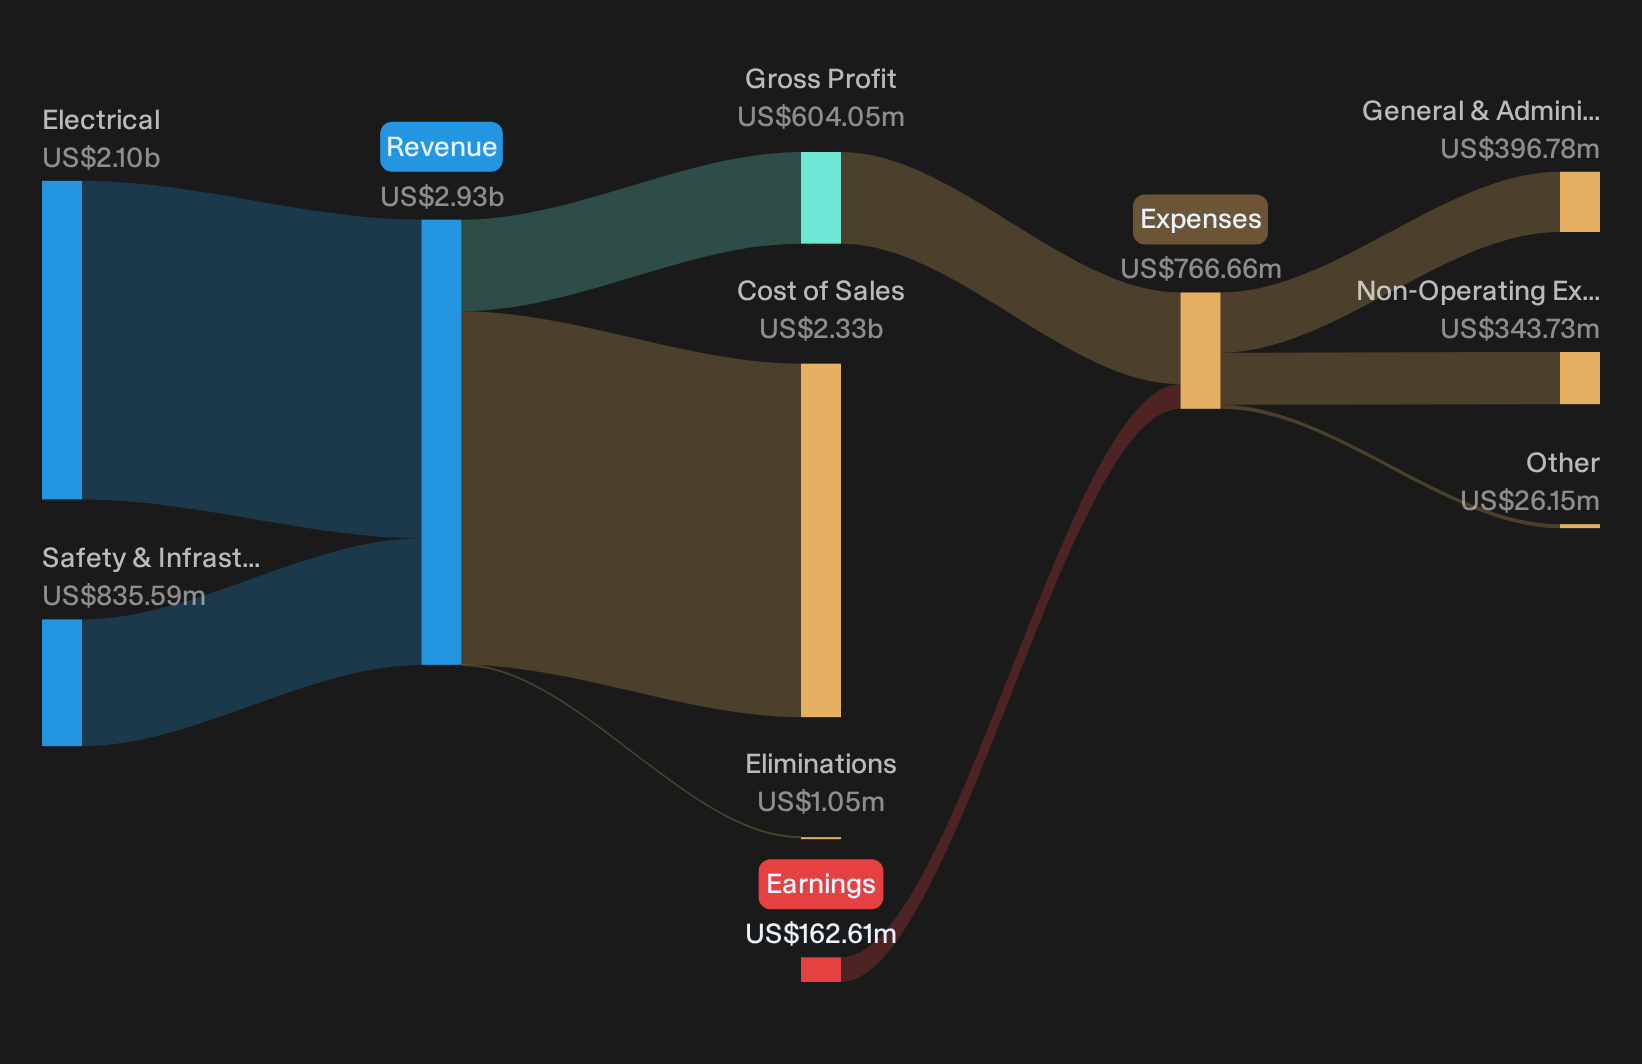
Operations: Atkore generates about US$2.1b from Electrical and US$836 million from Safety & Infrastructure, with roughly US$2.5b coming from U.S. customers.
Market Cap: US$3.2b
For a rate-sensitive industrial like Atkore, any shift in borrowing costs and construction capital budgets can quickly reshape investor expectations.
"High tariffs on imported steel and PVC conduit are reducing foreign competition and leading to significantly lower import volumes. This is positioning Atkore to recapture market share in domestically-sourced steel conduit over time."
What happens if a single pressure point in its pricing and cost equation moves against those expectations will matter a lot for margins.
If that pricing pressure reverses, you will want the full narrative for Atkore that connects tariffs, capital costs and where Atkore’s earnings power could be decoupling next.
Astec Industries (ASTE)
Overview: Astec Industries builds road and materials processing equipment that underpins U.S. infrastructure projects, placing the business squarely in the rate-sensitive capital spending camp.
Operations: Astec Industries generates about US$913.9 million from Infrastructure Solutions and US$676.8 million from Materials Solutions, with the United States contributing roughly US$1.25b in sales.
Market Cap: US$937 million
Astec Industries matters in this screener because every shift in financing costs or public works momentum can ripple quickly through big-ticket orders for its asphalt, concrete and aggregate systems.
"Passage of U.S. infrastructure bills, increased state and local transportation contract awards, and ongoing multi-year federal funding are set to drive sustained, visible demand for Astec's core road construction and materials equipment, supporting long-term revenue growth."
How a single unresolved pressure on its profitability interacts with that pipeline of funded projects will be crucial for investors watching Astec Industries.
That unresolved pressure is where things get interesting, and the full narrative for Astec Industries shows how Astec Industries’ order book, funding tailwinds and margins could be quietly decoupling.

Astronics (ATRO)
Overview: Astronics supplies high-value aerospace and defense electronics, so its earnings and financing costs can react quickly to shifting U.S. interest-rate expectations.
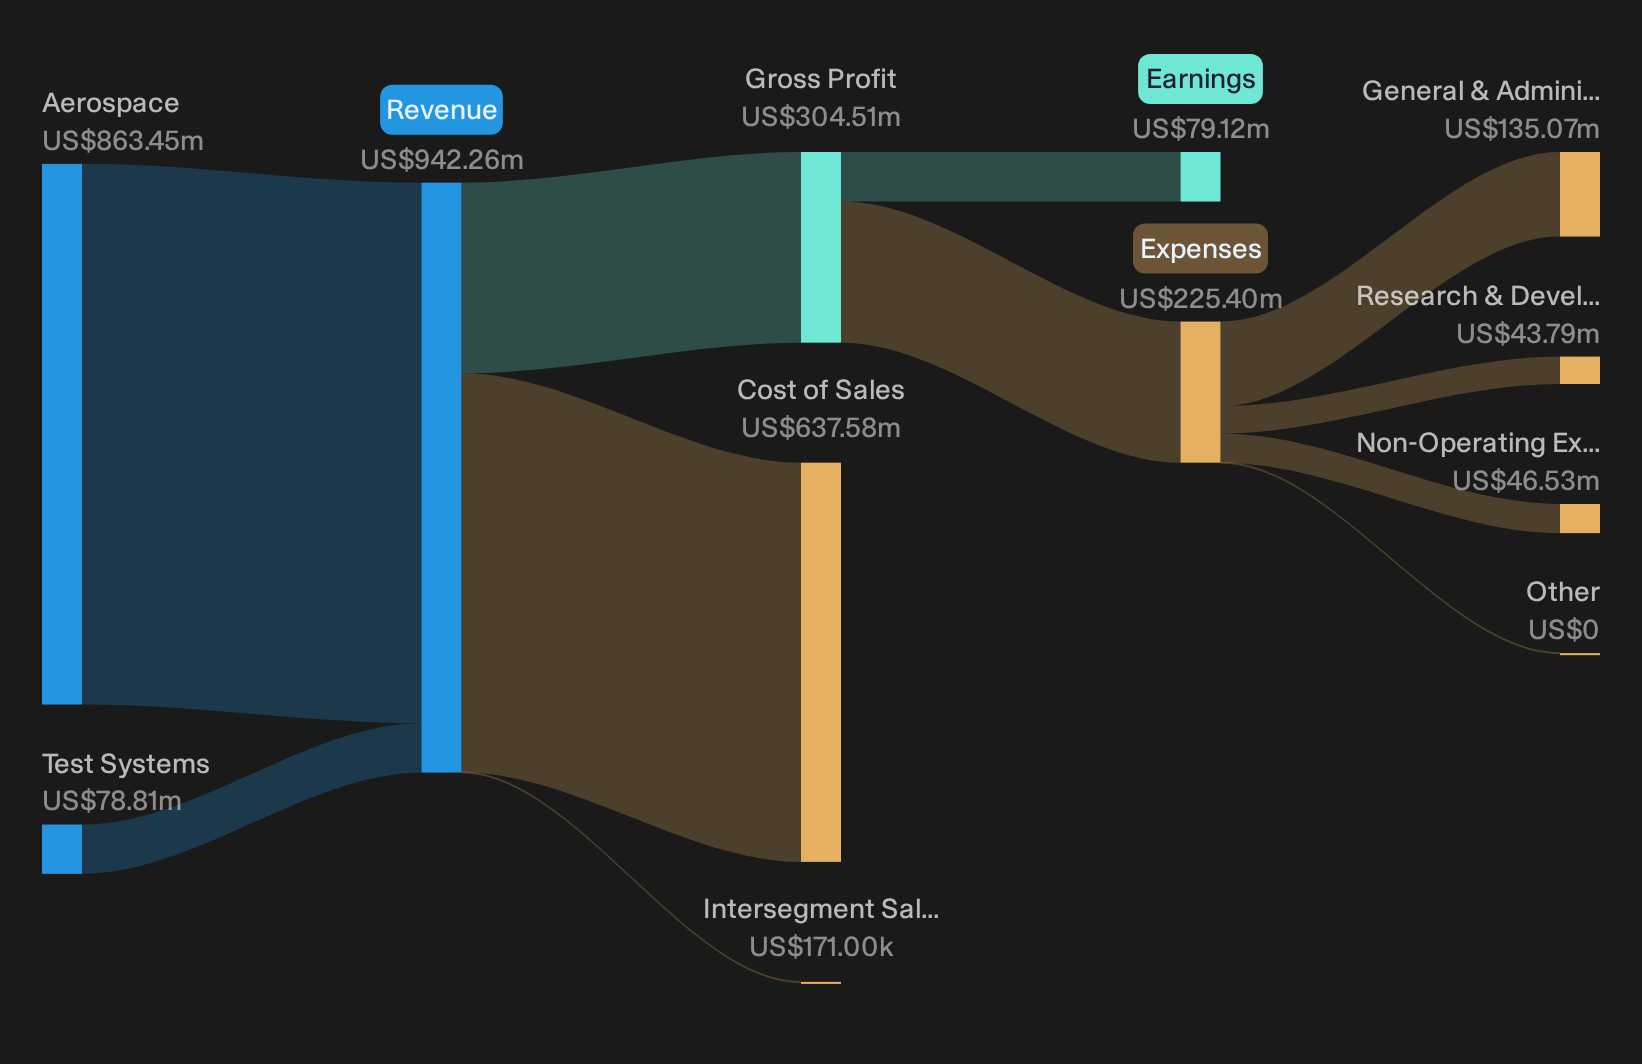
Operations: Astronics generates about US$863 million from Aerospace and US$79 million from Test Systems, with a small intersegment elimination.
Market Cap: US$2.9b
Astronics fits directly into the screener theme as a mid-cap industrial where aircraft cycles, capital spending plans and borrowing costs all influence how investors value its future cash flows.
"Rising aircraft production and global air travel demand are fueling growth in Astronics' high-margin product offerings and strengthening its recurring revenue streams."
How a single cost or financing pressure that cuts into that high-margin mix affects results will be critical for how Astronics converts demand into lasting profitability.
That margin question is exactly what the full narrative for Astronics unpacks, showing where Astronics’ earnings power could be accelerating, stalling, or quietly decoupling from headline demand.
Seeking Fresh Alternatives Before They Fly
Fresh breakouts, fading laggards, and under the radar momentum do not stay hidden for long. Spot ideas before the crowd while it matters and get in early.
- Track cash rich compounders with real staying power by scanning a curated list of solid balance sheet and fundamentals (26 results), which are built to handle shocks without scrambling for capital.
- Ride structural demand for critical metals by reviewing a focused group from the 16 top copper producer stocks, which could benefit if supply tightens while prices keep moving.
- Catch infrastructure linked momentum before it goes mainstream by searching the hand picked 40 power grid technology and infrastructure stocks now, while these grid upgraders are still priced like afterthoughts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com