
Agree Realty (ADC) Stock Looks About Right After Its 38% 3 Year Gain
Agree Realty has delivered a 3 year gain that looks very different from its more muted shorter term returns, which puts a sharper spotlight on what investors are paying for each dollar of earnings today. With the share price recently closing at US$65.88 after a softer run over the past few weeks, the key issue is how well that tag lines up with the real estate landlord's profit power.
- The stock is up 37.7% over 3 years, which makes it important to ask whether that rise is still grounded in the current earnings profile.
- The business leans on long term, triple net leases and a focus on essential retailers, which can support more predictable rental income and in turn shapes how investors think about the durability of its earnings stream.
- The analysts covering Agree Realty have run their own numbers. See what analysts think Agree Realty's shares could be worth.
The issue now is whether Agree Realty's recent share price leaves you paying a level that its earnings can reasonably support.
If you are weighing whether Agree Realty's current P/E feels fair, it can help to compare that question across a broader set of companies using the 31 high quality undervalued stocks.
Does Agree Realty Look Fairly Valued on Earnings?
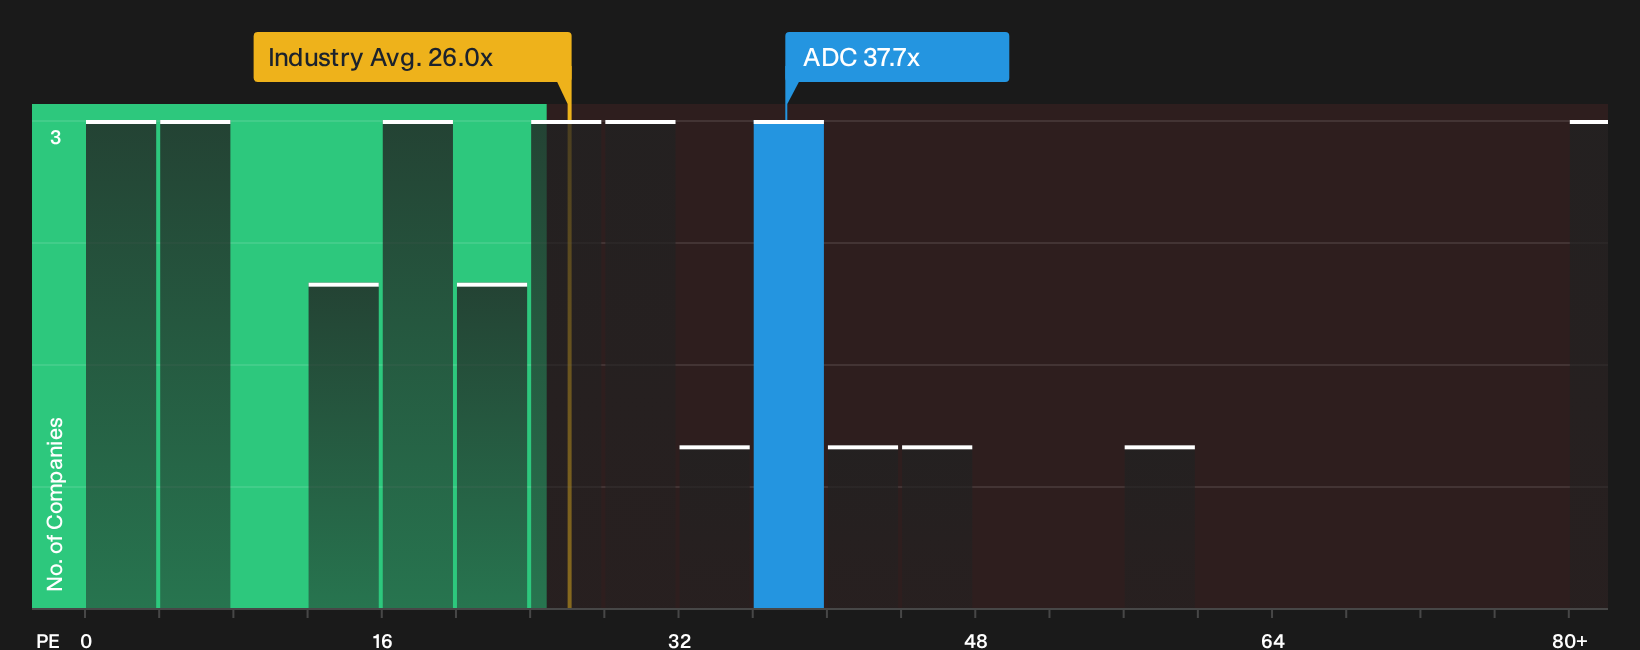
The P/E ratio suits Agree Realty because you are ultimately paying today for a stream of contracted rent that flows through to earnings. On that score, the stock trades on roughly 37.7x, which is higher than both the retail REIT industry average of about 26.0x and the broader peer set around 23.9x. That lifts the bar for what many investors might want to see from the REIT's earnings resilience before feeling comfortable with the tag.
A more tailored fair value framework that blends Agree Realty's sector, business model and risk profile points to a P/E that sits slightly below the current figure, so the shares lean towards the expensive side of that custom range rather than cheap. For anyone assessing the valuation, the question becomes whether the long term lease profile, tenant mix and balance sheet are strong enough to justify paying above sector and peer multiples for each dollar of profit. Explore the numbers behind Agree Realty's P/E valuation.
The Agree Realty Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Agree Realty valuation question leaves off by spelling out which paths for future growth, margins and earnings would need to occur for the current share price to look materially higher or lower over time on the Community page. Each scenario ties a fair value estimate to a clear storyline about Agree Realty's potential catalysts and key risks, so you can track which version appears to be unfolding.
One of the top community narratives on Agree Realty: 22% undervalued
"The main thing that has to go right is that Agree Realty continues to use its conservative balance sheet, interest rate hedging, and selective tenant mix..."
Discover why this Narrative puts Agree Realty at 22% undervalued.
Agree Realty has one more key piece to check
Balance sheets and P/E ratios only tell part of the story for Agree Realty, because the people setting priorities and how they are rewarded can strongly influence what happens next. See who runs Agree Realty and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com