
PetroChina (SEHK:857) Stake Sale Talks Put Its Valuation Back In Focus
XRG P.J.S.C is reportedly in talks with PetroChina (SEHK:857) and other LNG Canada partners about buying a stake in the export project, raising fresh questions about PetroChina’s capital allocation and long term gas exposure.
At around HK$9.52, PetroChina’s share price has slipped about 5.8% over the past month but is still up roughly 7.9% over three months. The 1 year total shareholder return of about 41% and 5 year total shareholder return near 243% point to strong longer term momentum, even as news like the potential LNG Canada stake sale reshapes perceptions of its future gas exposure and risk profile.
Scan beyond PetroChina and see how other energy producers are repositioning their portfolios with our hand picked 40 power grid technology and infrastructure stocks.
Recent swings around HK$9.52 and the LNG Canada stake chatter leave PetroChina looking either like a pullback worth leaning into or a signal to wait for a clearer margin of safety. So what do the current valuation markers really say?
Preferred P/E of 8.5x for PetroChina: Is it justified?
On current numbers, PetroChina screens as inexpensive on earnings, with the stock on a P/E of 8.5x while the last close sat at HK$9.52. For readers watching the LNG Canada headlines, that gap between the earnings multiple and many peers is where the valuation debate really starts.
The P/E ratio simply compares the share price to earnings per share, so it tells you how many dollars investors are willing to pay for each dollar of profit. In capital intensive energy groups like PetroChina, this metric matters because it blends near term profitability with expectations around future commodity cycles, capital allocation and exposure to projects like LNG Canada.
PetroChina trades on a P/E of 8.5x, while both the Asian Oil and Gas industry and peer group sit well above that level on 11.8x and 11.2x respectively. The estimated fair P/E of 12x is also materially higher than where the shares currently change hands. The market could move towards that level if sentiment and earnings expectations were to align with that implied valuation.
Explore the SWS fair ratio for PetroChina.
Result: Price-to-Earnings of 8.5x (UNDERVALUED)
Still, any extended weakness in oil and gas prices, or a decision by PetroChina to recycle capital into lower return projects, could quickly challenge this valuation story.
Find out about the key risks to this PetroChina narrative.
Another View on PetroChina’s value
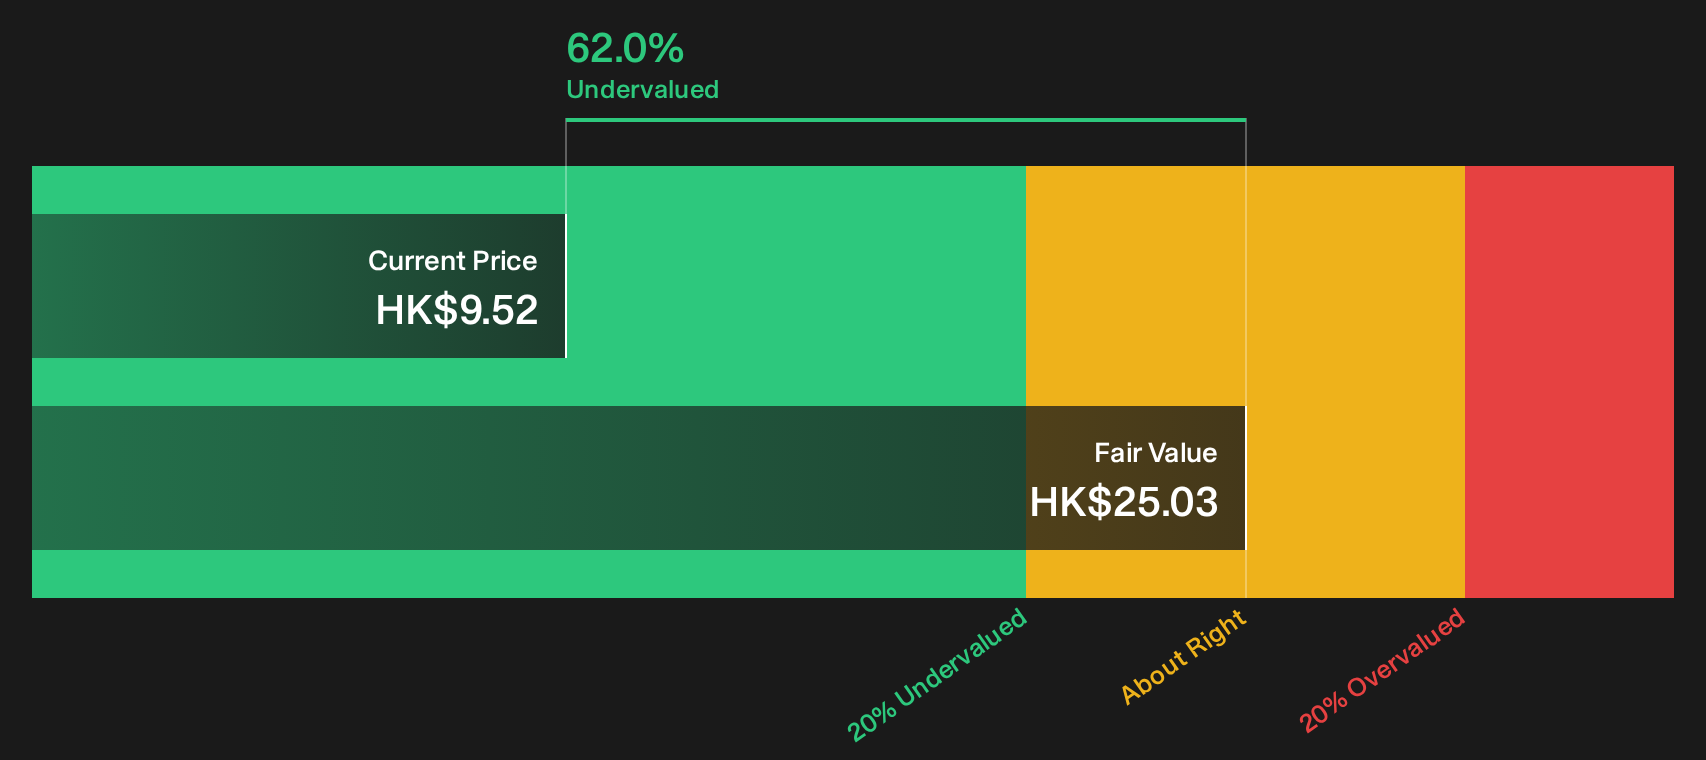
The P/E gap points in one direction, yet the SWS DCF model suggests something far more extreme. At around HK$9.52, PetroChina is described as trading below an estimated future cash flow value of HK$25.03, which implies the share price is heavily discounted on that lens.
DCF models lean on long term cash flow assumptions and discount rates. This kind of gap can signal either opportunity or miscalibration in those inputs. If the DCF is even roughly right, the bigger question is how long the market might take to close any part of that gap.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PetroChina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around PetroChina leave you torn, treat that uncertainty as a prompt to move quickly. Pressure test the numbers yourself, and weigh the 3 key rewards and 2 important warning signs through the 3 key rewards and 2 important warning signs
Looking for more PetroChina sized investment ideas?
Do not stop your research with PetroChina. Use the Simply Wall Street Screener to surface fresh opportunities that match your risk tolerance and return goals.
- Target higher income potential by focusing on companies that qualify as 169 dividend fortresses.
- Hunt for potential mispricings by scanning a curated set of 196 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- Prioritise capital resilience by reviewing a 228 resilient stocks with low risk scores that may offer a smoother ride through market swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com