
How Raised Revenue Guidance Will Impact Arista Networks Stock
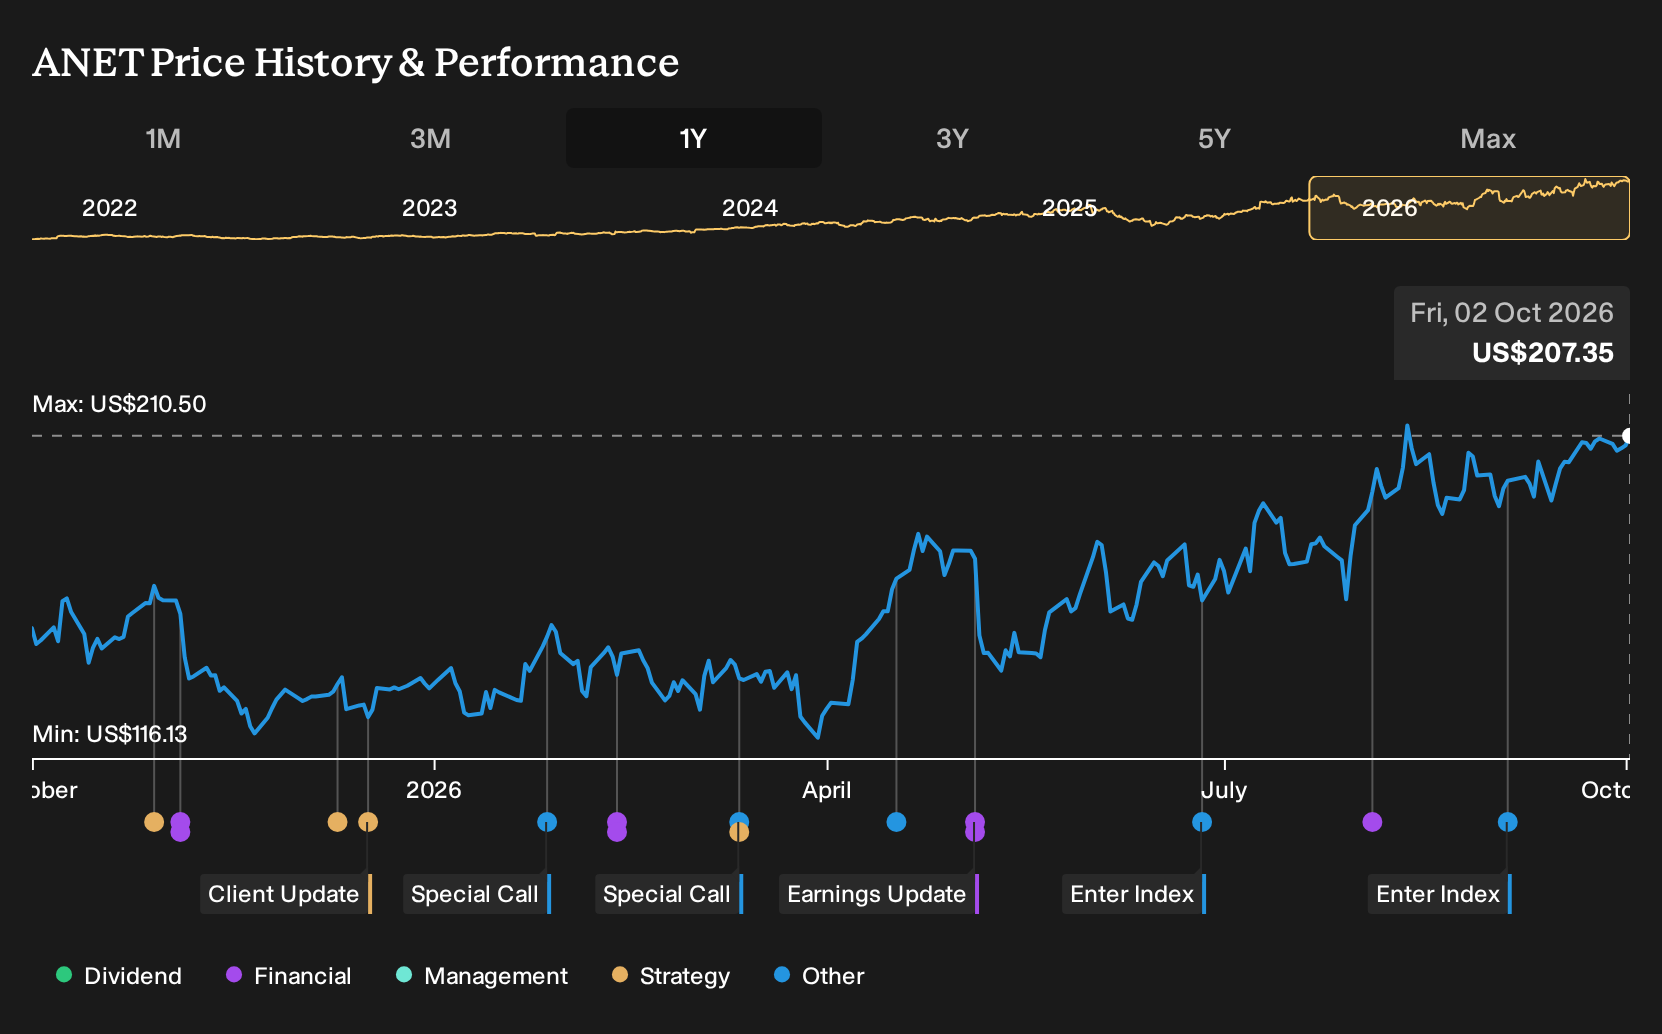
- Arista Networks recently attracted attention as investors weighed cash-secured put options on the stock alongside management’s higher revenue outlook and expectation for continued fast growth in fiscal 2026.
- The core question for readers is whether Arista Networks’ current valuation is reasonable given its focus on AI networking, software driven EOS, and exposure to supply chain and component cost pressures that could influence future cash generation.
- We will look at how Arista Networks’ investment narrative holds up against fresh valuation debate shaped by raised revenue guidance and cash-flow expectations.
Scan beyond Arista Networks by reviewing hand picked 90 AI infrastructure stocks, which could also be shaping the next leg of AI driven networking demand.
Arista Networks Investment Narrative Recap
For a shareholder in Arista Networks, the core belief is that AI driven network demand, open Ethernet adoption and EOS software can keep filling large orders from hyperscalers, neocloud providers and enterprises. The raised 2026 guidance around revenue, AI fabrics and margins points to management leaning into this cycle, although the latest options activity does not change those underlying operational goals.
The more immediate swing factor is how consistently large cloud and AI customers keep ordering high bandwidth switches while Arista manages tight supply chains and component costs. The biggest current risk remains customer concentration layered on top of multiyear chip commitments, which could bite if AI data center buildouts slow or U.S. permitting and regulatory scrutiny interrupt deployment plans.
The most relevant recent update is management’s guidance for about US$12.6b of revenue in 2026, including at least US$3.5b to US$3.6b from AI fabrics such as Etherlink. That outlook sits alongside a stated gross margin range of 62% to 64% and an operating margin target of 48% to 49%. This frames expectations for future cash generation that investors are now debating against the current DCF output.
In practical terms, this guidance makes Arista Networks a story about execution on very specific milestones. These include scaling AI fabrics across more than 100 customers, growing campus networking toward at least US$1.25b in 2026 and aligning long term chip purchases with demand so inventory, utilization and margins do not come under pressure if AI workloads or customer buildouts level off.
How Arista Networks’ Forecasts Line Up With Today’s Earnings Power
Arista Networks' current analyst story points to forecast revenue of US$21.4b and earnings of US$8.2b by 2029. That path assumes revenue expands at about 26.6% a year and that earnings roughly double from about US$4.0b today to reach those consensus profit targets by 2029.
Uncover why Arista Networks' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Arista Networks leans into supply risk rather than demand risk. The most optimistic analysts were already penciling in about US$25.2b of revenue and US$9.5b of earnings by 2029 before this options focused news. If you compare that to more cautious forecasts, the spread shows just how far opinions might shift as new information lands.
Explore 8 other Arista Networks fair value estimates, including one that suggests as much as 37% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Arista Networks research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arista Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arista Networks' overall financial health at a glance.
Looking for more investment ideas beyond Arista Networks?
Once you have a clear view on Arista Networks, it can help to widen the lens and compare it with other opportunities that match different risk, quality and income profiles using the Simply Wall St Screener.
- For investors hunting for value with quality in mind, review a focused set of companies through the 31 high quality undervalued stocks and see which ones warrant a closer look.
- If capital preservation and steadier profiles matter most to you, scan a curated group of resilient businesses using the 31 resilient stocks with low risk scores to see what fits your comfort level.
- When you want to uncover less crowded stories backed by solid fundamentals, check out a hand picked collection of potential sleepers via the 19 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com