
Why DHT Holdings (DHT) Is Getting Attention Today
Unrest in the Middle East has pushed voyage rates higher through the Strait of Hormuz, and DHT Holdings (DHT) is directly exposed through its very large crude carrier, DHT Tiger.
DHT Holdings has been firmly in the spotlight, with unrest linked voyage rates feeding into a 1-month share price return of 18% and a 90-day move of 37.8%, contributing to a 101.7% year-to-date gain. That short-term momentum sits on top of a 1-year total shareholder return of 129.5% and a 5-year total shareholder return of about 4.6x, which indicates that recent trading is being viewed in the context of a longer period of strong value creation for investors.
Scan other energy shippers riding similar route volatility with our curated list of list of solid balance sheet and fundamentals (26 results) to see how DHT Holdings compares on fundamentals.
DHT Holdings now trades above consensus price targets, while one valuation estimate still flags a small discount. Where does fair value actually sit after a run like this?
Most Popular Narrative: 8% Overvalued
DHT Holdings closed at $23.68 against a widely followed fair value estimate of $21.85. The narrative framework currently points to a rich price that leans on strong tanker conditions and capital discipline.
Strong balance sheet, low leverage, competitive financing, and a disciplined capital allocation strategy (including dividend payouts and buybacks) enhance DHT's ability to invest in growth and navigate market cycles, supporting long-term EPS and shareholder returns.
See why 102 investors see DHT Holdings as 8% overvalued.
Result: Fair Value of $21.85 (OVERVALUED)
Still, the DHT Holdings story is exposed if crude transport demand weakens, or if its high dividend payout limits future spending on newer, compliant vessels.
Find out about the key risks to this DHT Holdings narrative.
Another View: SWS DCF Model Says Undervalued
The analyst narrative calls DHT Holdings about 8% overvalued at $23.68 versus a $21.85 target. A different lens tells a tighter story. The SWS DCF model estimates future cash flow value at $24.67, which puts the current quote roughly 4% below that mark. Which signal do you treat as more important?
For a closer look at the assumptions behind that cash flow view, review how the model handles rates, margins, and discounting through the full cycle, then weigh how comfortable you are with those inputs relative to tanker volatility. Look into how the SWS DCF model arrives at its fair value.
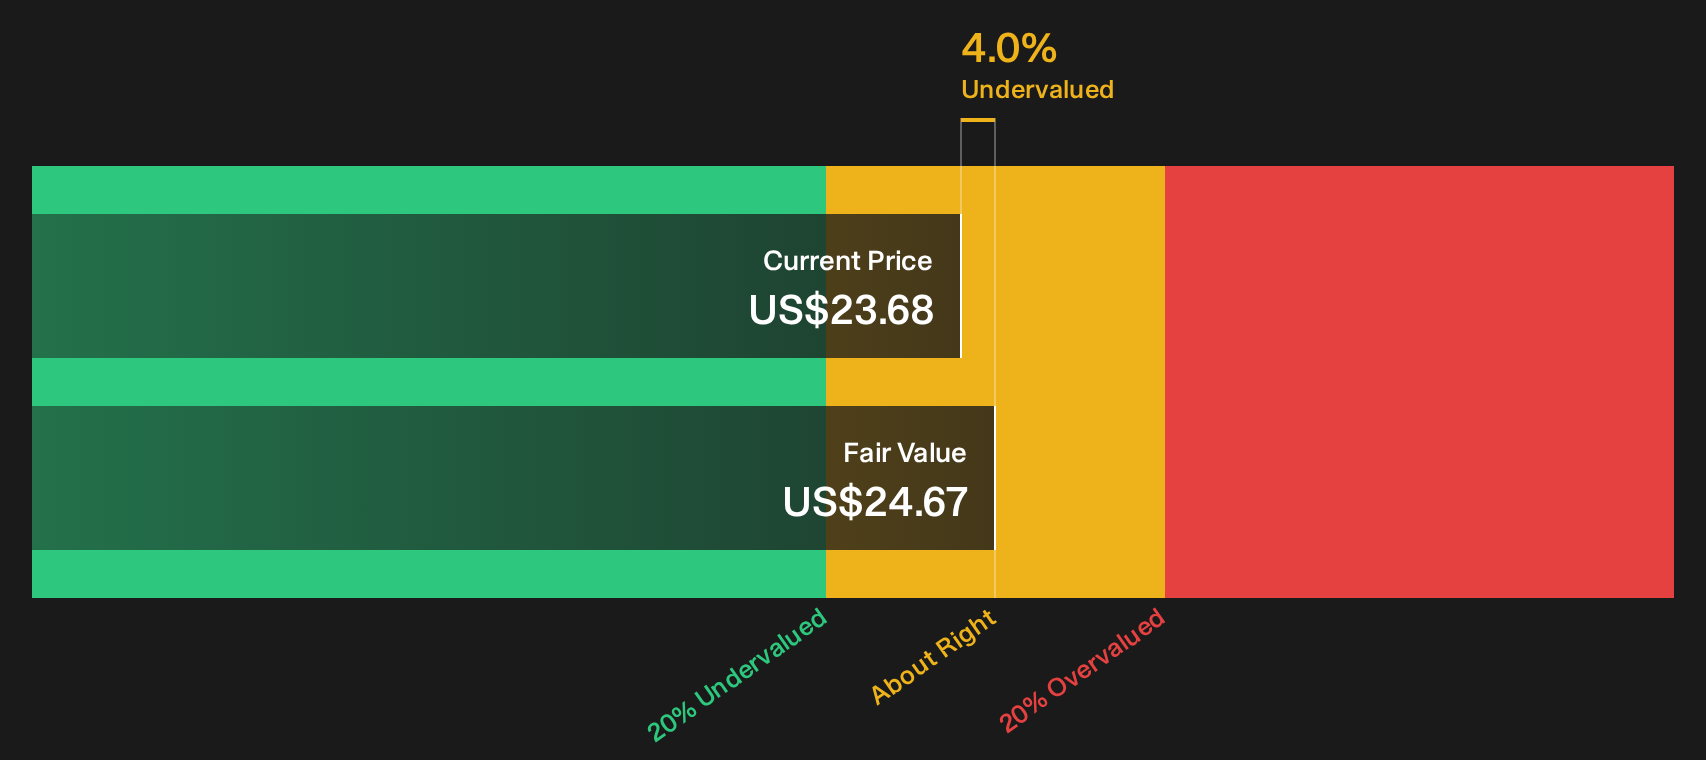
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DHT Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on DHT Holdings valuation today. If you want to move fast and build your own stance on that tug of war, start with the 2 key rewards and 4 important warning signs.
Want more ideas beyond DHT Holdings?
If you stop with DHT Holdings, you only see one angle. Use the Simply Wall St Screener to spot other opportunities before they move without you.
- Target potential mispricings by focusing on quality businesses that look cheap on the numbers through our 31 high quality undervalued stocks.
- Build a steadier income stream by scanning for companies that pair higher yields with resilient payout histories using the 7 dividend fortresses.
- Reduce portfolio stress by concentrating on financially robust operators with strong balance sheets through this focused 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com