
What RenaissanceRe Holdings Stock's Strong Q2 Results Mean For Shareholders
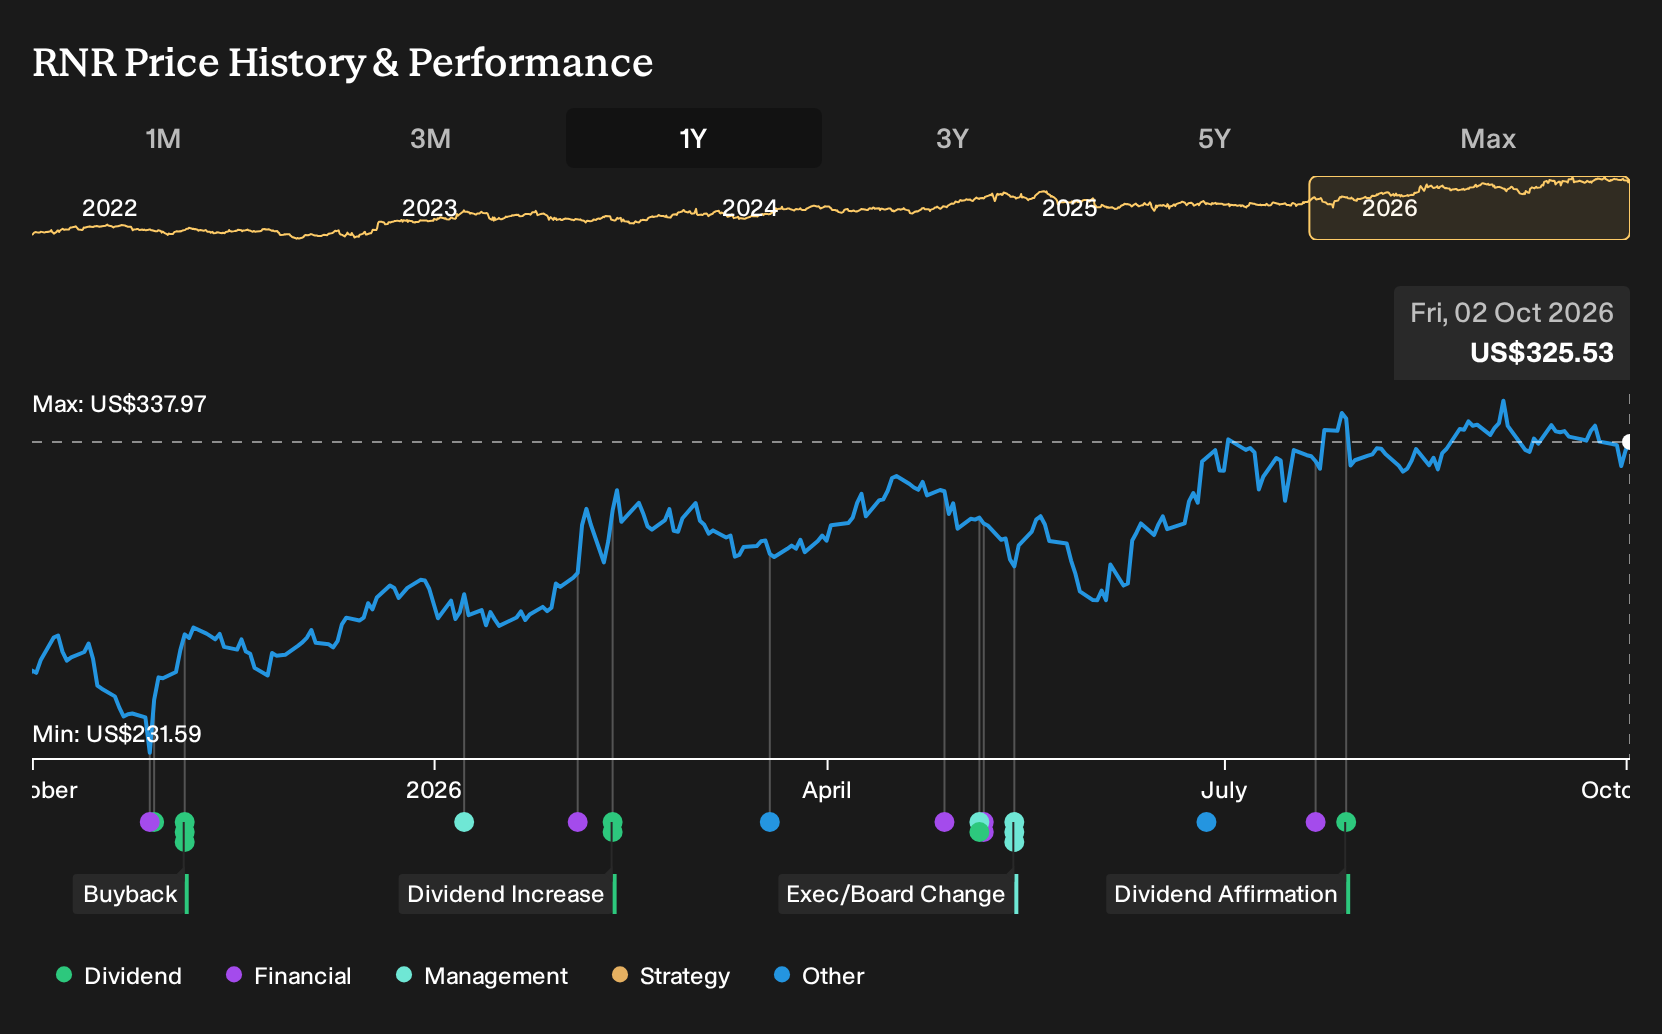
- RenaissanceRe Holdings recently reported strong Q2 2026 results, with management pointing to solid underwriting, higher fee and investment income, 6% growth in tangible book value per share, and US$350 million of share repurchases.
- Management also flagged deeper use of AI across operations, a more constructive view on the current hurricane season, and planned leadership changes from 2027. Together, these factors signal how the business is thinking about risk, efficiency, and long-term positioning.
- Now the focus is on how RenaissanceRe Holdings' stronger underwriting and capital actions could influence the broader investment narrative around the stock.
What Is RenaissanceRe Holdings' Investment Narrative?
To own RenaissanceRe Holdings, you need to buy into a very specific story. This is a reinsurance business built around underwriting discipline, heavy capital needs, and a willingness to return cash when management thinks the odds are in shareholders’ favour. The Q2 2026 update, with stronger underwriting, higher fee and investment income, and a 6% lift in tangible book value per share, feeds that thesis. It also includes US$350 million of buybacks, which aligns with a stock that screens on a low P/E of 5.3x and is described as trading well below some fair value estimates.
The near term hinges on whether that underwriting edge and AI driven efficiency hold up as pricing in property catastrophe lines softens and as leadership changes approach from 2027. Forecasts calling for earnings and revenue to decline over the next three years sit awkwardly next to recent 32.2% earnings growth and a 20.7% return on equity. In the short term, the latest quarter counters the idea that the profit story has already peaked, but it does not erase the key swing factor around how sustainable current economics really are.
Even so, there is a separate pressure point around RenaissanceRe Holdings that could matter far more if ...
There's only one way to know the right time to buy, sell or hold RenaissanceRe Holdings. Head to Simply Wall St's company report for the latest analysis of RenaissanceRe Holdings's Fair Value.
Exploring Other Perspectives
The most optimistic analysts lean hard on capital management as a catalyst. Before this Q2 2026 news, they were pencilling in earnings of about US$1.5b by 2029 and projecting revenues near US$8.3b for RenaissanceRe Holdings, even with shrinking margins. You are seeing one quarter; they are sketching a very different multi year story.
Explore 2 other RenaissanceRe Holdings fair value estimates, including one that suggests the potential for as much as 200% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RenaissanceRe Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RenaissanceRe Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RenaissanceRe Holdings' overall financial health at a glance.
Looking For More Ideas Beyond RenaissanceRe Holdings?
Once you have a view on RenaissanceRe Holdings, it can help to widen the lens and compare it with other businesses that share similar qualities or offer something very different. The Simply Wall St Screener lets you filter for exactly the traits you care about, so you can build a watchlist that fits your own risk profile and return goals.
- If you want potential upside with strict financial filters, focus on companies that pair strong balance sheets with attractive valuations using the 31 high quality undervalued stocks.
- If income matters more to you than rapid growth, concentrate on reliable payers with higher yields by reviewing the 7 dividend fortresses.
- If capital protection is your priority, start with businesses that carry lower risk scores and sturdier fundamentals through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com