
Walmart (WMT) Stock Looks Pricey After Its 138% Five Year Run
Walmart has delivered strong long term returns for shareholders, yet the stock has softened recently, which puts a spotlight on whether its current price still lines up with the earnings behind it. With the share price closing at US$104.26 and a mixed run over shorter timeframes, the question for investors is how much of the retailer's profit power is already reflected in that tag.
- Over the past 5 years the stock has gained 138.4%, so a lot of past optimism and execution is already baked into the story and now needs to be weighed against the earnings that support it.
- Recent news around Walmart, from AI powered shopping partnerships and digital payments to workforce upskilling, can influence how quickly earnings may grow and how dependable those profits look through different retail cycles.
- There is a second opinion on Walmart worth weighing. See what analysts think Walmart's shares could be worth.
For investors, the debate is whether Walmart's current share price is appropriately grounded in the earnings it is generating today and is expected to produce over time.
If you want to stress test this same earnings question beyond Walmart, you can apply the same lens across 30 high quality undervalued stocks.
Has Walmart Run Too Far on Earnings?
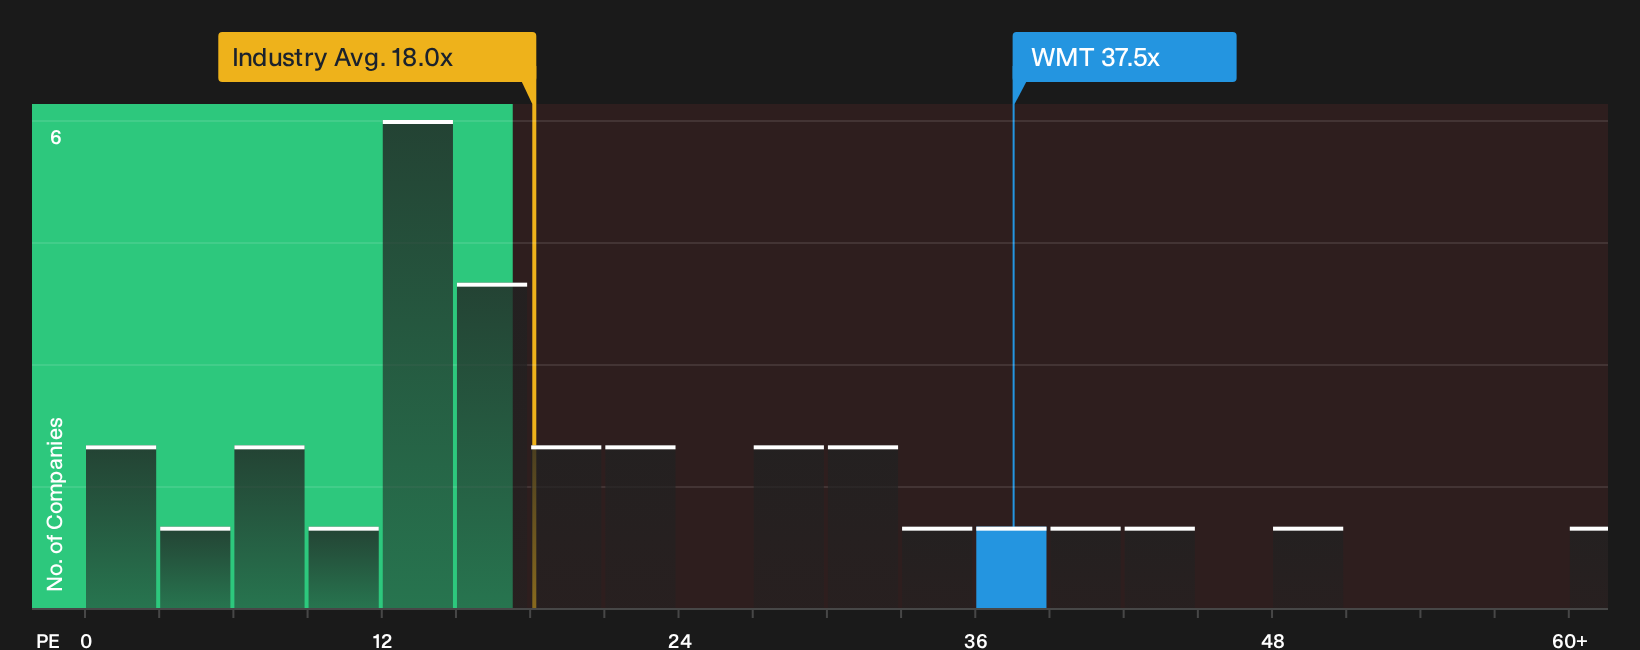
The P/E ratio fits Walmart well because earnings are still the main yardstick investors use for a mature retailer that throws off steady profits. At about 37.5x, Walmart's P/E sits well above the Consumer Retailing industry average of roughly 18.0x and also ahead of the peer group near 22.2x. That means buyers today are paying a much higher price for each dollar of earnings than they would for a typical listed retailer.
The fair P/E that falls out of a model of Walmart's growth profile, margins, size and risk sits lower than the current 37.5x, so the stock screens as overvalued on this framework. Because Walmart is pushing into AI driven partnerships and payments, such as the Flipkart and digital wallet moves, part of this premium likely reflects investor enthusiasm for those newer profit streams as much as the core store base. If you hold or are considering the shares, you are effectively assuming that the earnings power justifies this richer multiple over time, rather than lining up with the more restrained benchmark. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question on Walmart leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or meaningfully less than it is today, and they sit on Simply Wall St's Community page. Each one lays out its own set of assumptions behind an estimated fair value in plain terms, so you can track those against Walmart's actual results as they are reported.
One of the top community narratives on Walmart: 19% undervalued
"Expansion of higher margin business streams Walmart Connect, marketplace, and Walmart+ memberships is diversifying Walmart's income base beyond retail…"
Discover why this Narrative puts Walmart at 19% undervalued.
One more check on Walmart that goes beyond the share price
Before you lean too heavily on Walmart's earnings multiple, it is worth looking at who is steering the business, how their pay packets are structured, and what that implies for the decisions you rely on. See who runs Walmart and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com