
Is DuPont De Nemours (DD) Undervalued Following Its Sugar Separation Advisor Launch?
DuPont de Nemours (DD) has just rolled out its Sugar Separation Advisor, a digital tool that uses experimental chromatography data to help sugar and sweetener producers shortlist AmberLite resins for purification trials.
Against that product launch backdrop, DuPont de Nemours shares recently closed at US$129.98, with short-term momentum softening as the 30-day share price return declined 2.22% and the 90-day share price return fell 7.10%. Even so, the 1-year total shareholder return is 32.23% and the 5-year total shareholder return is 62.00%, pointing to a longer record that many holders will still be focusing on.
Scan how DuPont de Nemours compares with other potential compounders by reviewing a curated set of 19 high quality undiscovered gems that pair solid fundamentals with under-the-radar stories.
DuPont de Nemours now trades at US$129.98 while external estimates and internal cash flow work point to a much higher range of values. How wide is that gap once fair value is pinned down?
Most Popular Narrative: 23.5% Undervalued
On the widely followed narrative view, DuPont de Nemours screens as undervalued, with an implied fair value of $170 against the recent $129.98 close. This puts the focus firmly on how the reshaped Healthcare & Water and Diversified Industrials portfolio actually delivers.
DuPont de Nemours is reshaping its portfolio around Healthcare & Water Technologies and Diversified Industrials, supported by the recent Aramids divestiture and GICS shift to Industrials. This concentrates capital and management attention on businesses that management expects to support revenue growth and operating EBITDA margins over time.
See why 32 investors see DuPont de Nemours as 24% undervalued.
Result: Fair Value of $170 (UNDERVALUED)
Still, DuPont de Nemours faces live PFAS legal exposure and slower Water segment demand. Either of these factors could undercut the 2026 guidance driven narrative.
Find out about the key risks to this DuPont de Nemours narrative.
Another View: DuPont de Nemours Through The P/E Lens
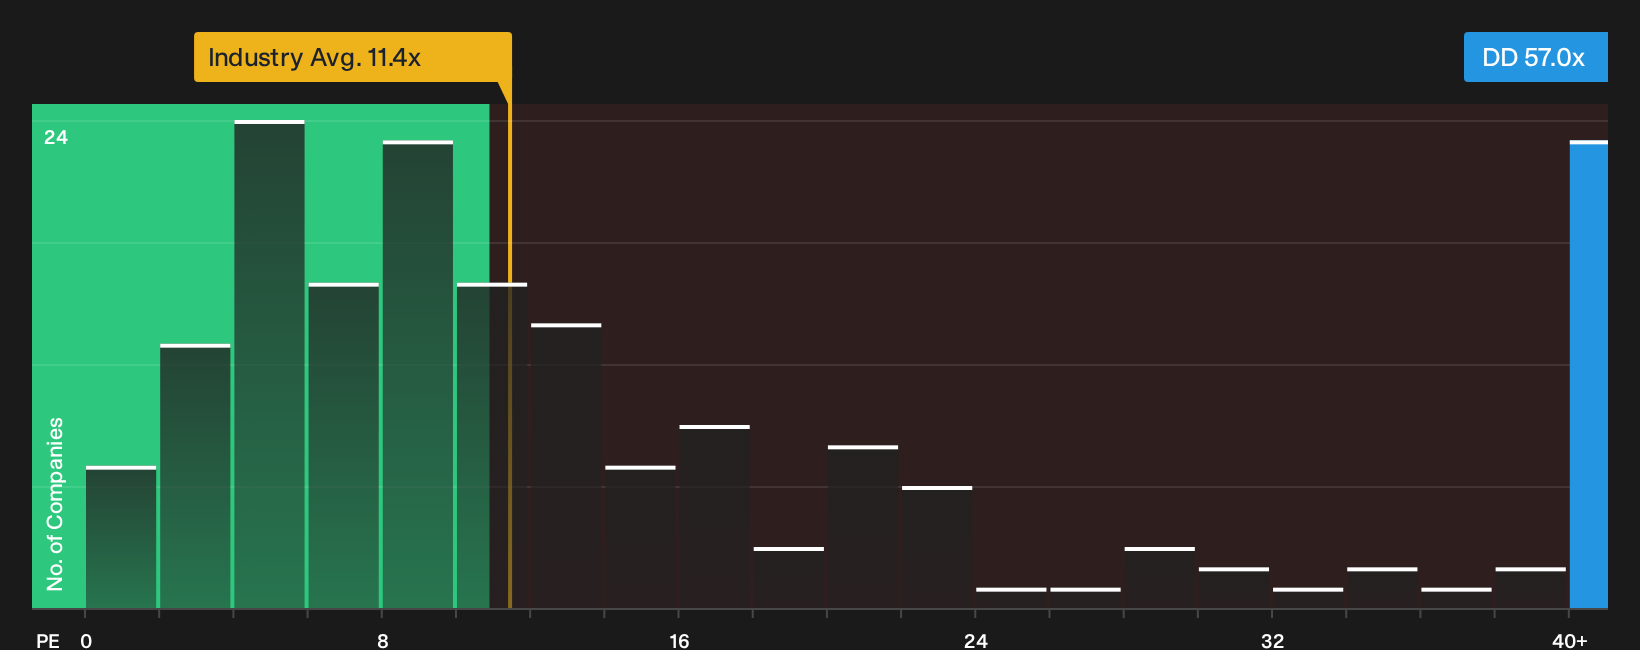
There is a very different message when DuPont de Nemours is viewed through its current P/E ratio. The shares trade on roughly 57x earnings compared with a fair ratio estimate of 35.4x, the Global Industrials average of 11.4x and a peer average of 28.8x. That is a wide valuation gap for you to weigh.
Instead of relying on a single metric, it can help to test this rich earnings multiple against a fuller breakdown of value signals from the same data set, then decide how much valuation risk you are comfortable taking on See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With DuPont de Nemours pulling in both enthusiasm and concern, you do not need to sit on the fence. Act quickly, test the numbers against your own thesis, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond DuPont de Nemours?
If DuPont de Nemours has sharpened your focus on quality and price, do not stop here. Broaden your watchlist with a few targeted screeners that surface very different kinds of opportunities before the crowd catches on.
- Target steadier compounding potential by reviewing 31 resilient stocks with low risk scores that aim to keep volatility and balance sheet stress in check.
- Hunt for mispriced quality by scanning the 31 high quality undervalued stocks that pair robust fundamentals with what may be discounted share prices.
- Strengthen your income stream by assessing 7 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com