
Datadog (DDOG), What Is Behind The Growing Attention?
Fresh commentary around Datadog (DDOG) centers on rising demand tied to AI adoption and more complex software systems, which is contributing to its non-AI customer growth and deeper multi-year platform commitments.
Investors have been leaning into that AI and observability story, with Datadog’s share price at $277.22 after a sharp recent run, including a 32.5% 1 month share price return and a 107.24% year to date share price return. These sit alongside a 193.57% 3 year total shareholder return, pointing to momentum that markets are currently rewarding rather than fading.
Scan beyond Datadog and evaluate other software players riding similar AI and observability trends with the hand picked 90 AI infrastructure stocks.
After a run that leaves Datadog at $277.22 and only a small gap to the average analyst target near $287, the wider spread in fair value estimates matters far more than that 3.6% difference. Where does a reasonable anchor actually sit now?
Most Popular Narrative: 3% Undervalued
On the most followed view, Datadog screens as slightly undervalued, with a fair value of about $285 per share against the current $277.22 price. This puts all the focus on whether the business can keep converting AI interest into durable earnings power.
Expanding AI workloads, with over 750 AI customers including all 10 of the top AI leaders and growing use cases such as GPU monitoring, Agent Observability, AI Guard and Bits AI, can support higher observability and security spend per customer and feed Datadog revenue growth over time.
See why 172 investors see Datadog as 3% undervalued.
On this narrative, the 8.64% discount rate is used to bring those forecast cash flows back to today. A fair value near $285 per share implies the current price embeds some caution around guidance, insider selling and customer concentration rather than unrestrained optimism about AI demand. Earnings of $177.6 million today and an expected move to $780.0 million by 2029 sit at the center of that view, along with a future P/E assumption of 180.8x that stays well above the 29.5x level cited for the wider US software group.
Result: Fair Value of $285 (UNDERVALUED)
Still, Datadog’s story could shift quickly if revenue concentration around very large customers bites harder, or if guidance underwhelms again and compresses that rich 180.8x P/E assumption.
Find out about the key risks to this Datadog narrative.
Another View: Datadog Looks Expensive On Sales
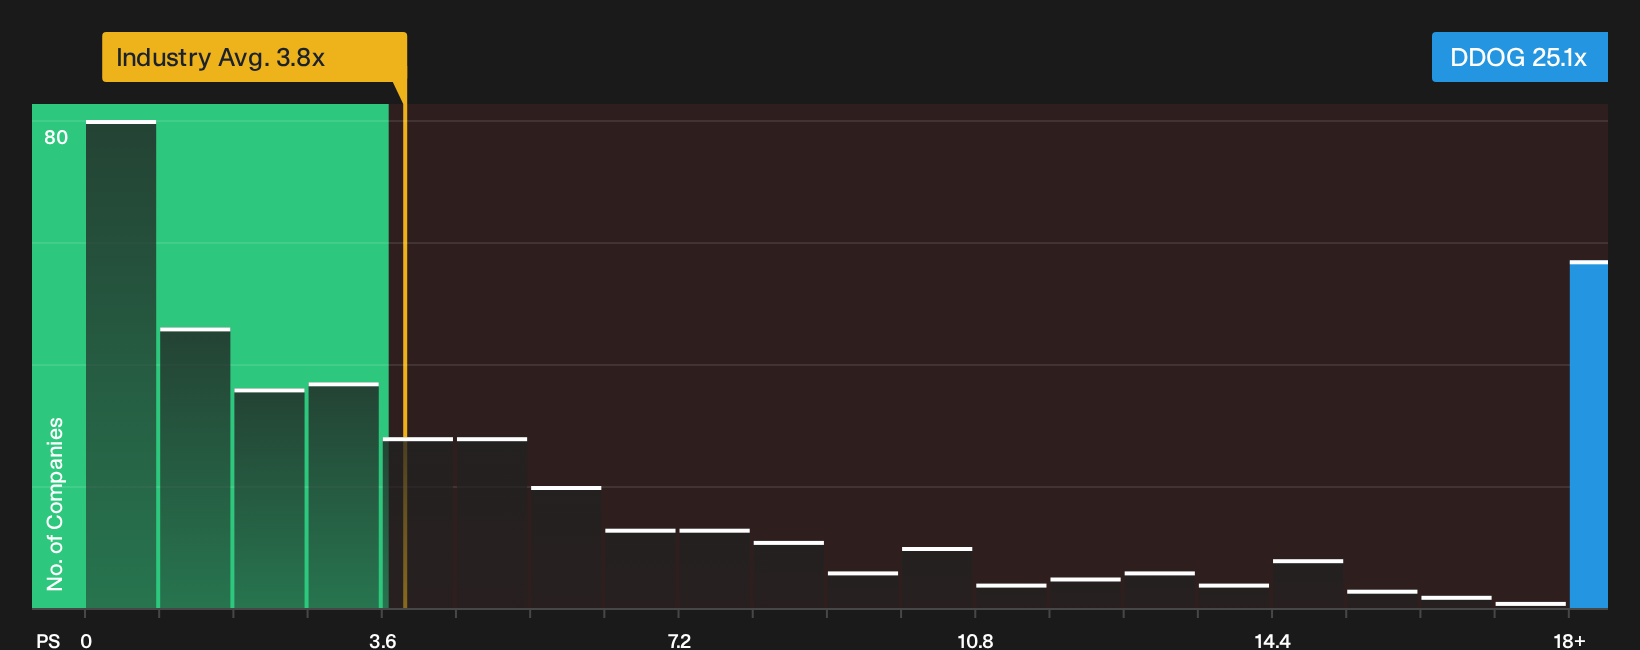
The discounted cash flow work suggests Datadog is undervalued, with the current $277.22 price sitting about 11.8% below an estimated fair value of $314.45. On a simple P/S lens, the story flips. A 25.1x sales multiple is far above the US software group at 3.8x, the peer average at 8.4x, and even a fair ratio of 15.3x, which points to meaningful valuation risk if sentiment cools. Which signal do you think deserves more weight?
Before leaning on either approach too heavily, it helps to see what the numbers are saying in detail about this price level, then weigh that against Datadog's qualitative strengths and risks, See what the numbers say about this price — find out in our valuation breakdown.
That context becomes clearer once you line up Datadog against other software stocks on a consistent sales multiple and see how far its current pricing stretches those comparisons,
Next Steps
The mix of enthusiasm and caution around Datadog will not resolve itself. Act while sentiment is active and weigh both sides by reviewing the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Datadog?
Do not stop with Datadog. Broaden your watchlist with a few targeted stock ideas that match how you like to balance risk, quality and potential upside.
- Target value opportunities that pair quality balance sheets with attractive pricing by scanning the 31 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by focusing on companies screened through the 31 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd arrives by working through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com