
Amplitude (AMPL) Could Be 62% Undervalued Following Its Q2 Earnings Beat
Q2 earnings beat puts Amplitude in focus
Amplitude (AMPL) moved into the spotlight after a Q2 earnings beat, with revenue up 21.2% year over year and results ahead of expectations in billings and adjusted operating income, lifting the stock meaningfully.
Recent trading has reflected that earnings surprise. Amplitude shares have a 90 day share price return of 61.76% and a year-to-date share price return of 30.83%, while the 1 year total shareholder return of 39.92% contrasts with a 5 year total shareholder return that is down 72.47%. This suggests that momentum has picked up only more recently.
Compare Amplitude's recent earnings momentum with other software and data stocks by scanning our curated 37 profitable AI stocks that aren't just burning cash that combine growth exposure with stronger current fundamentals.
The recent surge leaves Amplitude trading close to analyst targets, while internal fair value estimates still imply a wider gap. Which reference point deserves more weight now that expectations have reset?
Most Popular Narrative: 3.8% Overvalued
Amplitude closed at $14.30, while the most followed narrative pegs fair value at $13.77 using an 8.53% discount rate. The story now hinges on whether its AI and product expansion can support that premium.
The continued investment and leadership in AI-driven analytics, supported by multiple strategic talent acquisitions and rapid product innovation (e.g., AI agents, Guides, Surveys), position Amplitude to capitalize on the growing enterprise need for automated, actionable insights, creating opportunities to increase ACV and command premium pricing, ultimately supporting margin expansion and stronger earnings.
See why 9 investors see Amplitude as 4% overvalued.
Result: Fair Value of $13.77 (OVERVALUED)
Still, Amplitude’s heavier infrastructure costs and reliance on larger enterprise contracts could pressure margins and make revenue swings more pronounced if key customers pull back.
Find out about the key risks to this Amplitude narrative.
Another View: SWS DCF Puts Amplitude In A Different Bucket
The analyst narrative frames Amplitude as 3.8% overvalued at $14.30 versus a $13.77 fair value. Our DCF model tells a different story, with a future cash flow value of $23.19 that sits well above the current quote. That gap points to upside potential, but also to the risk that cash flows and discount rate assumptions prove too optimistic. Which set of expectations do you trust more?
For a clearer sense of how that cash flow view is built and where the key sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
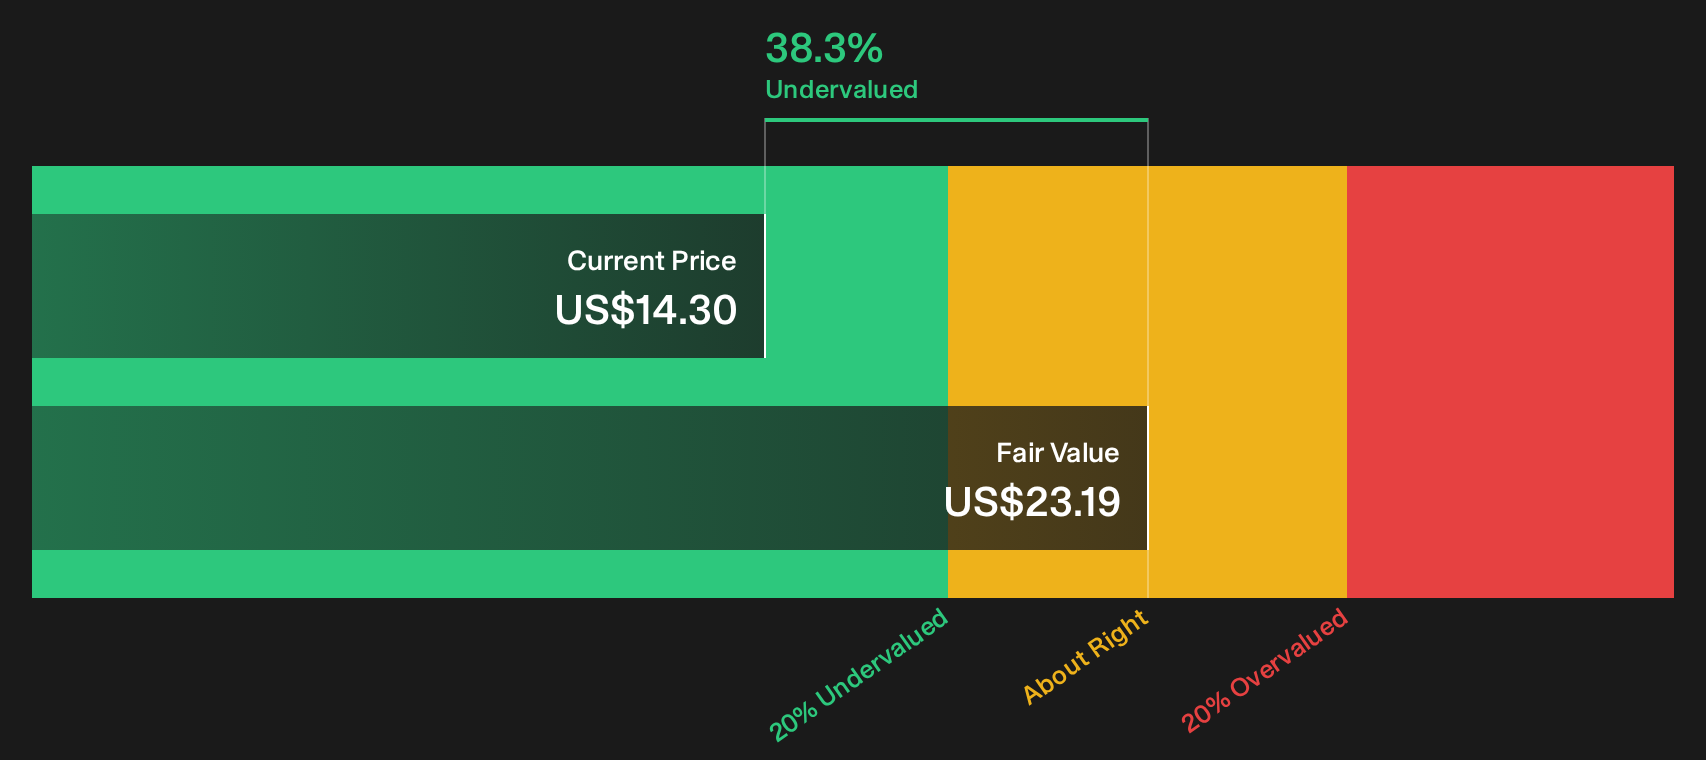
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amplitude for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Amplitude are clear, with optimism on future cash flows and concern around execution risk sitting side by side. Act quickly, look through the detailed numbers, and weigh the trade off for yourself with 2 key rewards and 1 important warning sign.
Ready to find your next idea beyond Amplitude?
If Amplitude has your attention, consider broadening your watchlist. Fresh ideas now can matter more than any single earnings print or valuation model snapshot.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) before capital moves elsewhere.
- Hunt for quality at a discount by reviewing the 28 high quality undervalued stocks that might suit your return and risk preferences.
- Prioritise cash returns by checking out the 7 dividend fortresses that pair higher yields with durable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com