
3 Japanese Growth Stocks With At Least 22% ROE
Tokyo inflation just hit 2.7% in September, and the Bank of Japan is openly weighing rate hikes for the first time in years. Big institutions tend to focus on large, well covered Japanese stocks when policy shifts like this occur. That leaves a pocket of smaller, high quality companies going largely ignored. This article highlights three such under the radar Japanese opportunities from our screen that may be worth a closer look.
The three stocks covered next are just a sample set from this theme, and the full screen surfaced 72 more businesses with equally compelling narratives that are not covered here. To go straight to the source and identify your own high conviction ideas, head into the High-Quality Undiscovered Gems screener.
Sanki Engineering (TSE:1961)
Overview: Sanki Engineering provides HVAC, plumbing, disaster prevention and smart building mechanical systems for commercial and industrial facilities across Japan.
Operations: The company currently generates all reported revenue of ¥258,351 million from projects and services within Japan.
Market Cap: ¥404.4 billion
Sanki Engineering fits this screener because its HVAC and building systems work is tied directly to long term infrastructure needs. The company reports 48.7% net earnings growth and a 22.1% ROE, which indicate strong recent execution. A key question for investors is how those margins might behave if a single unseen pressure in the operating environment were to shift.
That pressure point is already visible in the numbers, so it is worth checking the 3 key rewards and 2 important warning signs before assuming Sanki Engineering’s current profile is the full story.

Tsugami (TSE:6101)
Overview: Tsugami manufactures CNC precision lathes, machining centers and grinding machines that help produce tiny, high accuracy parts for electronics and telecom hardware globally.
Operations: Tsugami records ¥122,170 million of revenue from China, ¥29,844 million from Japan and ¥7,299 million from India, with smaller contributions elsewhere.
Market Cap: ¥255.5 billion
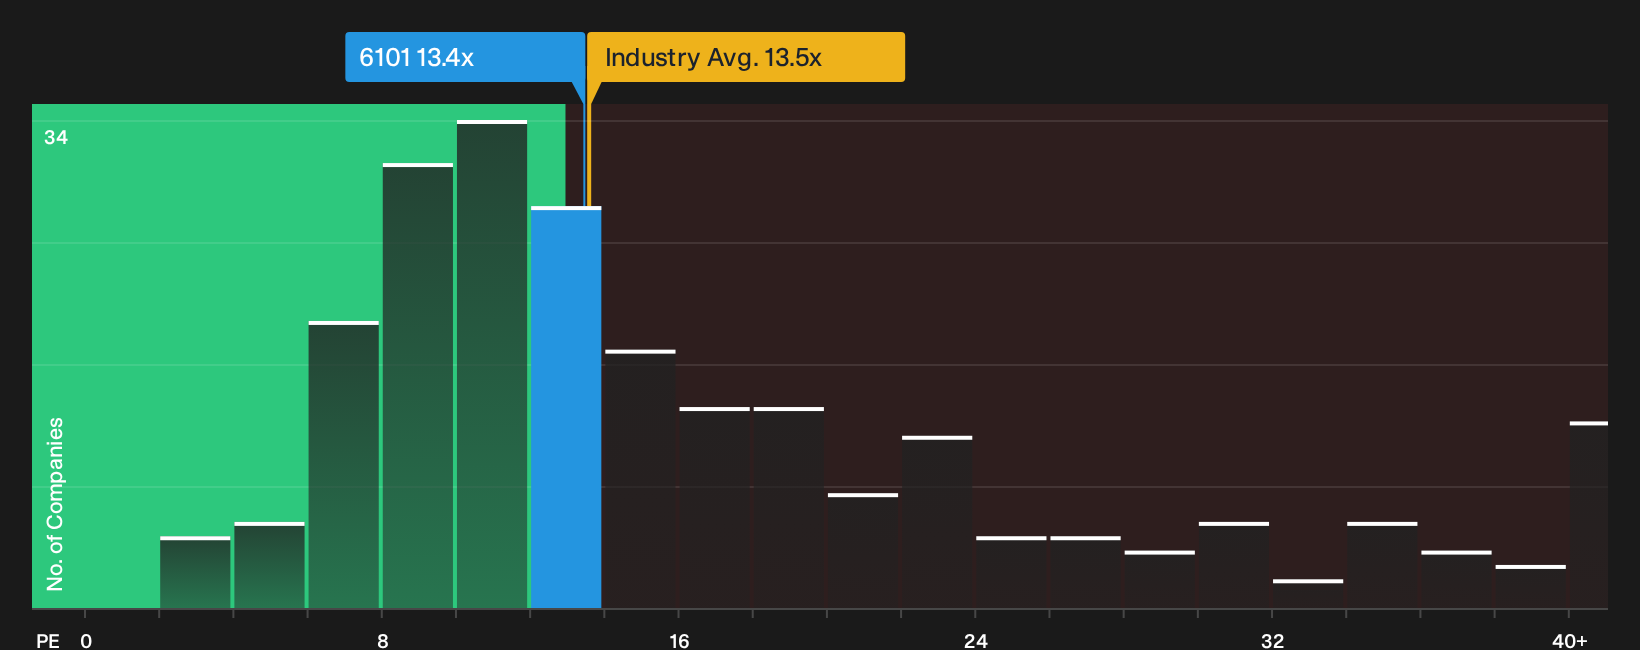
Tsugami aligns with the High-Quality Undiscovered Gems theme by supplying precision machine tools for miniaturized electronics and telecom components, and currently trades on a P/E of about 13.4x, with reported earnings growth of 53.6% and an ROE of 23.2%. For investors evaluating less widely covered industrial suppliers, the relationship between quality and pricing power may depend on how the investment thesis holds up if a single key assumption changes.
If that single assumption is your sticking point, go straight to the 3 key rewards and 1 important major warning sign to see where Tsugami’s quality story could start to decouple.
santec Holdings (TSE:6777)
Overview: santec Holdings develops high precision optical components and measurement instruments, especially tunable lasers and imaging systems for telecom, sensing, and medical uses.
Operations: santec Holdings generates about ¥25,276 million from optical measuring instruments, ¥6,461 million from optical components, and ¥2,939 million from other activities.
Market Cap: ¥274.8 billion
santec Holdings fits the High-Quality Undiscovered Gems screen through its niche optical instruments. Its 31.2% ROE and 25.9% net margins are tied to highly specialized lasers and filters that many large funds do not closely follow. The key consideration for investors is how those margins might respond if a single assumption about this premium niche business model changes.
If that core assumption about santec Holdings’ premium niche has you curious, go straight to the 2 key rewards and 1 important major warning sign to see what could quietly tilt the thesis.

Curious To Seek Stronger Alternatives?
Fresh ideas move first. Momentum shifts quickly, and the most interesting stories often fly under the radar for now. Scan these focused lists before the crowd and get in early.
- Target dependable income streams by reviewing a curated 24 dividend fortresses that may help balance growth ambitions with consistent cash returns.
- Spot early AI momentum and track where real profits meet real products using the hand picked 37 profitable AI stocks that aren't just burning cash.
- Follow the copper supply story and see which miners hold the strongest positions across a refined 16 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com