
NextNav (NN) Names New Business Development Chief, Is The Stock Still Undervalued?
New business development leadership at NextNav
NextNav (NN) has drawn fresh attention after appointing Vijay Venkateswaran as Chief Business Development Officer, putting a veteran of telecom and industrial technology markets in charge of partnerships and go to market plans.
The appointment lands after a softer patch for the NextNav share price, which has slipped around 15% over the past three months and about 15% year to date, even though the 3-year total shareholder return is up sharply while the 1-year total shareholder return is only modestly lower.
Recent moves, including this hire and an upcoming investor presentation on 29 September 2026, come against that backdrop of fading short term momentum and a still strong multi year total shareholder return profile. This suggests that investors are reassessing both growth potential and execution risk at the current US$13.76 share price.
Scan beyond NextNav and compare this leadership-driven story with other hand-picked software and tech plays using the 19 high quality undiscovered gems.
NextNav now trades far below the average analyst target, yet the share price has been drifting lower. Is the market sensibly discounting execution risk, or mispricing the upside after this leadership change?
Most Popular Narrative: 59% Undervalued
On the numbers, the most followed narrative pegs fair value for NextNav at about $33.67, far above the recent $13.76 close. This view puts a lot of weight on how the 5G PNT opportunity and spectrum story ultimately play out.
Progress at the FCC toward an NPRM on 5G based 3D PNT in the lower 900 megahertz band, combined with a congressional push to free more spectrum, sets the stage for commercial rights that can unlock new service revenues and crystallize spectrum value on the balance sheet, supporting higher earnings and asset valuations.
See why 4 investors see NextNav as 59% undervalued.
Result: Fair Value of $33.67 (UNDERVALUED)
Still, the bullish case on NextNav leans heavily on timely FCC action and broad carrier adoption, both of which could slip or fragment and weaken that upside story.
Find out about the key risks to this NextNav narrative.
Another view on NextNav's valuation
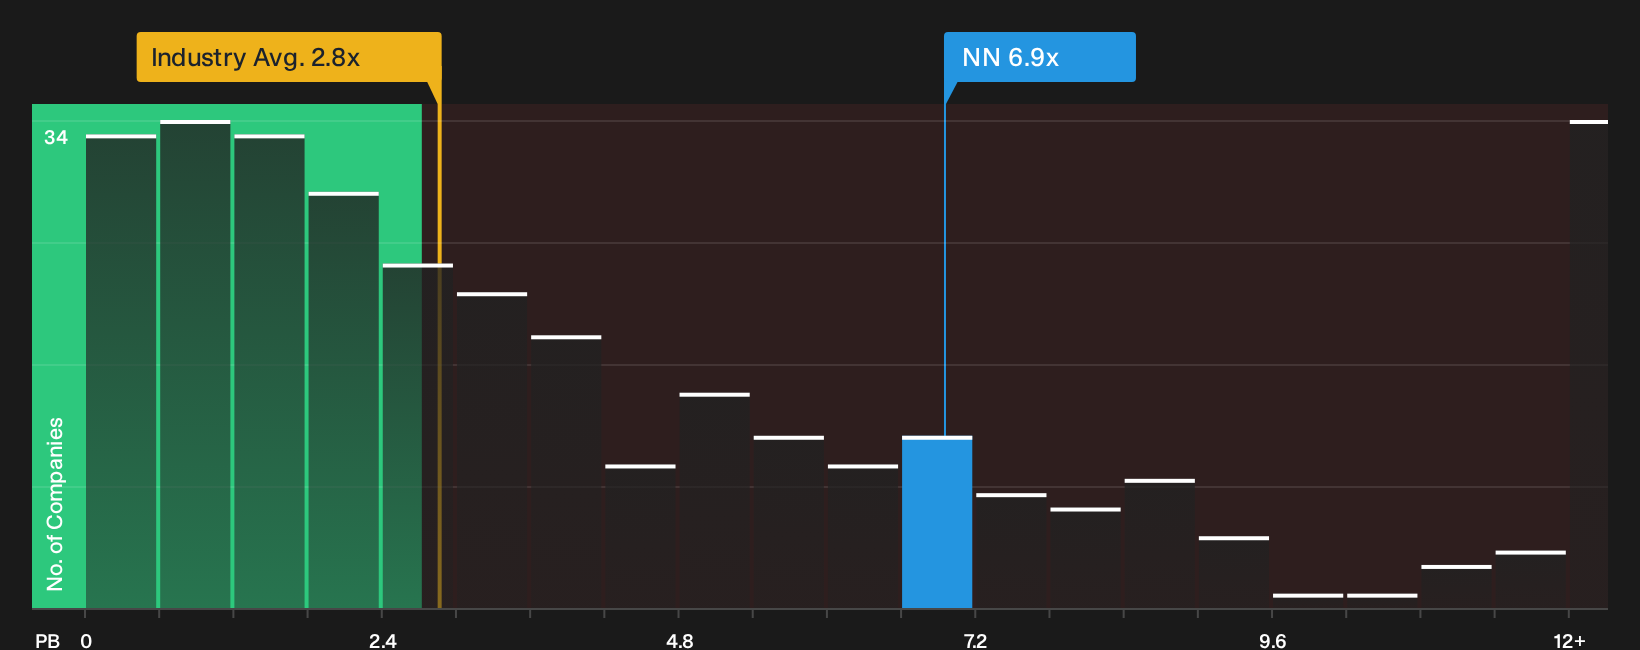
The earlier fair value narrative for NextNav leans heavily on future earnings assumptions and an implied P/E that is extremely high by any normal standard. A simpler cross check looks at the current P/B of 6.9x versus the US Software average of 2.9x and a peer average of 7.1x. That framing paints NextNav as expensive against the sector overall, yet roughly in line with closer peers, which raises an important question: Is the stock priced for perfection, or is it simply reflecting a very specific niche story that either plays out or disappoints?
For a deeper look at how this ratio driven view compares with more detailed valuation work, use the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this overview of NextNav seems divided between potential and risk, consider reviewing the numbers yourself and evaluating the 1 or more red flags highlighted in the 4 important warning signs.
Looking for more investment ideas beyond NextNav?
Do not stop with one ticker. Broaden your watchlist with fresh ideas that fit different goals, risk levels, and income needs using focused stock lists.
- Target potential mispricings by reviewing companies that screen as quality opportunities on the 28 high quality undervalued stocks.
- Strengthen your downside protection by checking businesses that feature resilient balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Build a cash flow stream by scanning for income opportunities among the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com