
What Comes Next For PDF Solutions (PDFS) After A 104% Year
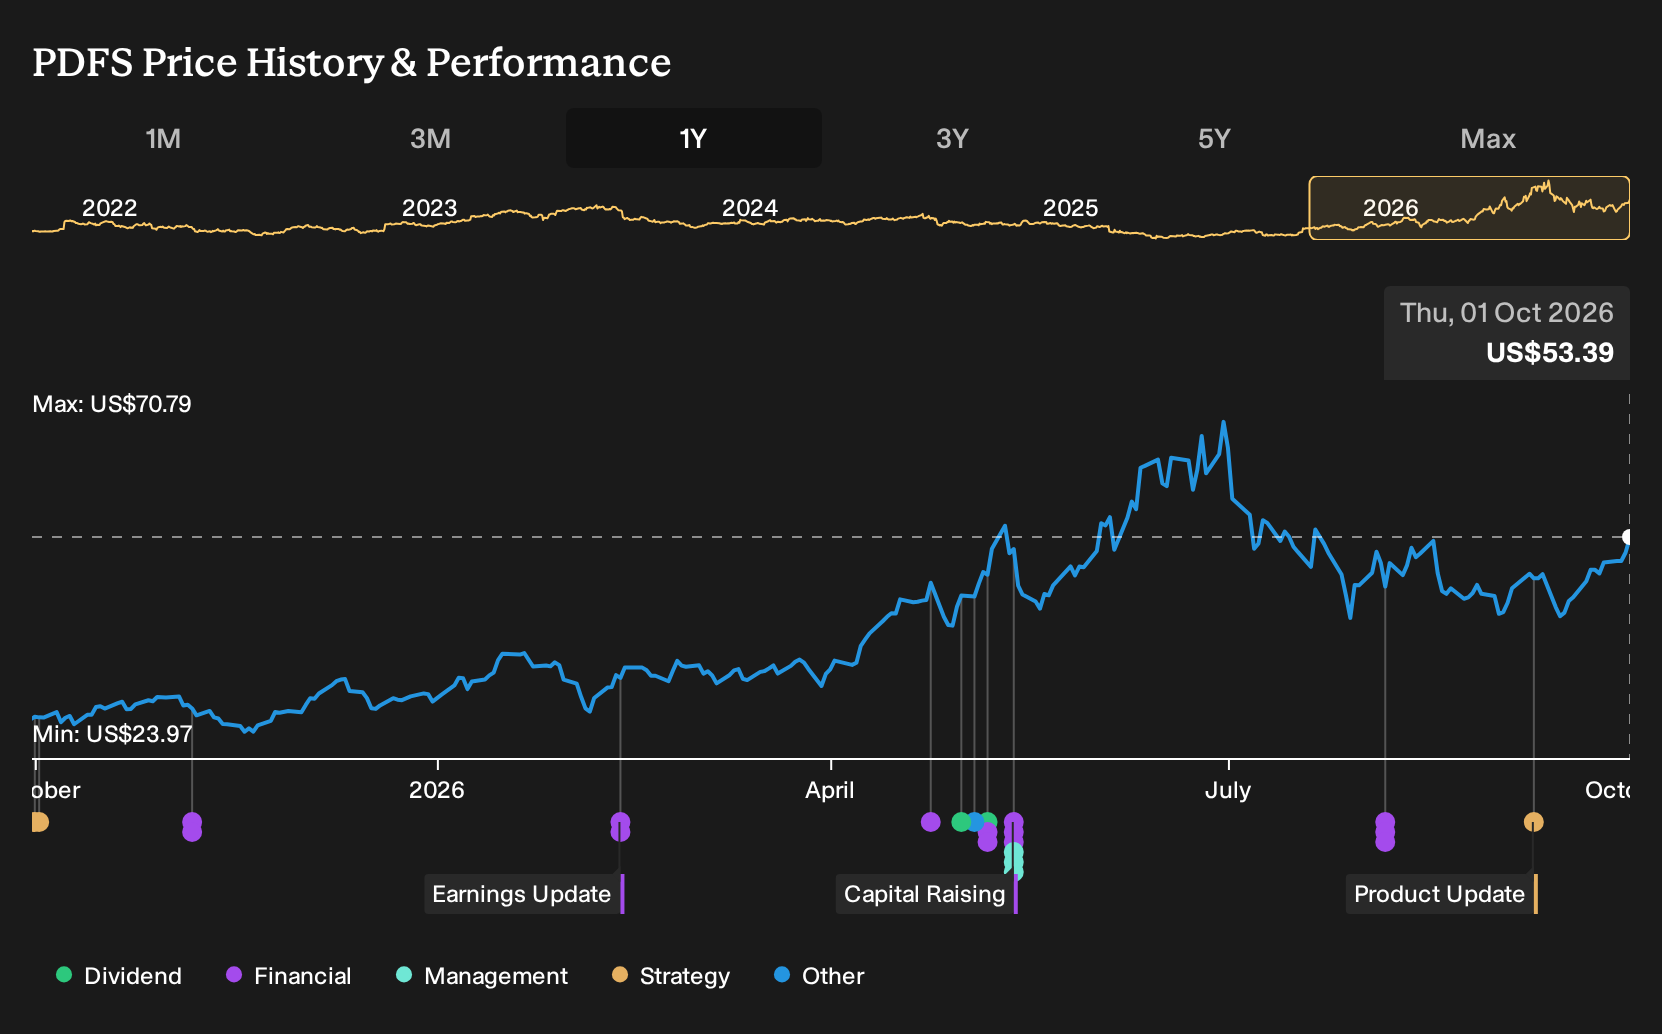
If PDF Solutions was on your watchlist instead of in your portfolio, the outcome over the past year may feel like a missed shot. Holding PDF Solutions over the past year would have returned 104.2%, including dividends. That jump invites a blunt question. Back on 1 October 2025, when analysts were arguing over whether enterprise adoption and semiconductor trends could support a high future P/E, what specific belief about recurring, cloud-based manufacturing analytics would have helped you spot the potential earlier?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
PDF Solutions is not the only name tied to this theme. Zero in on 38 AI small caps and compare how each one is priced.
The Argument You Would Have Been Weighing On PDF Solutions
The shares cost US$26.22 at the start of the period, so anyone looking at PDF Solutions then had to choose between two very different but credible stories.
The bullish narrative pointed to a fair value of US$30. It leaned on the idea that enterprise buyers would keep adopting PDF Solutions' cloud analytics, with recurring revenue growth supported by assumed 19.0% annual revenue growth and a 14.5% profit margin.
The bearish view anchored on a fair value of US$24. It focused on risks from data privacy rules, customer concentration, and proprietary AI efforts at large chipmakers, with an assumed 29.1x future P/E needed to make that case work.
What The Results Changed In The PDF Solutions Argument
PDF Solutions reported Q2 2026 revenue of US$61.5 million and net income of US$4.3 million, with net margin at 6.9% versus 2.2% a year earlier. That shift in profitability supported the view that recurring, cloud analytics could scale margins, although rising regulatory and customer concentration concerns left the cautious case alive. Overall, the evidence pointed in both directions.
The key assumption here was margin expansion from recurring analytics. For any other stock built on a similar story, track net margin alongside subscription or SaaS related revenue in each quarterly report and compare that path with the original thesis.
What PDF Solutions' Price Now Asks You To Believe
Today PDF Solutions trades at US$53.39. The selected Narrative places its Fair Value above that level, built on a view that recurring cloud analytics and deeper chip industry ties could support stronger earnings power than current consensus implies.
For anyone paying today's price, the key question is whether recurring, cloud-based analytics can keep winning share inside large semiconductor workflows fast enough to support meaningfully higher long term margins.
"Accelerating AI adoption and deeper industry partnerships position the company for outsized, recurring revenue and expanding industry influence in semiconductor analytics. Secular shifts in global chip fabrication and advanced packaging will drive long term margin expansion and solidify the company's critical role in end-to-end supply chain solutions."
The price and this Narrative do not agree. → Uncover what this Narrative says PDF Solutions is actually worth
Another Way To Play AI Demand
PDF Solutions lives where chip data gets interpreted. You could look one step away and consider the stack beneath it.
Every model that PDF Solutions helps monitor still needs heavy computing, fast connections, and reliable networking to run effectively.
There is a different business focused on that digital plumbing. It supplies connectivity gear and private cloud software to keep workloads running and managed.
If you like the recurring analytics story at PDF Solutions, you might also care about who keeps the digital infrastructure humming behind the scenes.
One Narrative has already put a figure on it. → Uncover the company trading 47% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com