
Should Carbon Capture Plans Require Action From Cenovus Energy (TSX:CVE) Investors?
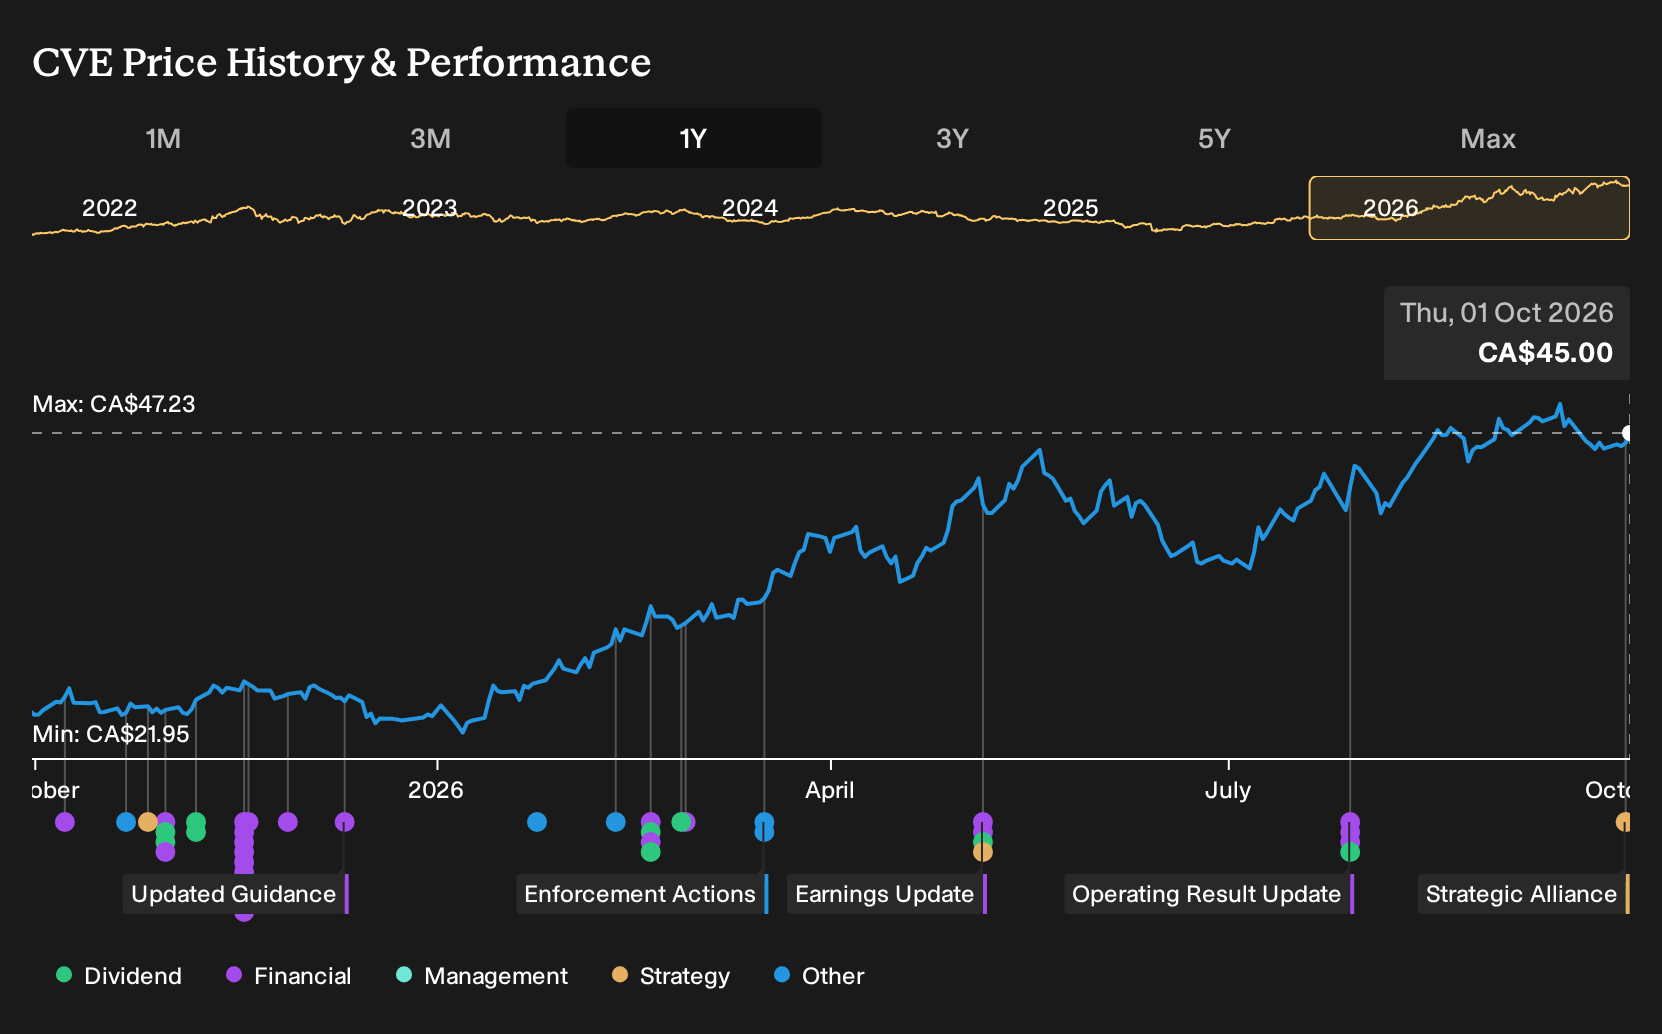
- In late September 2026, Cenovus Energy and four peers confirmed plans to advance the shared Pathways CCS project under a trilateral MOU with Canada and Alberta, targeting capture of about 6 million tonnes of CO2 annually by 2035 and 16 million tonnes by 2045.
- The conditional MOU links potential oil sands expansion to large-scale carbon capture spending and future fiscal terms. This could reshape Cenovus Energy’s long-term cost base, capital allocation priorities and regulatory obligations if final agreements are reached.
- We will now assess how the investment case for Cenovus Energy could shift as the Pathways CCS cost and policy framework firms up.
Scan how Cenovus Energy stacks up against other decarbonisation plays by zeroing in on hand picked 9 resilient stocks with low risk scores with the balance sheets to fund long term carbon capture spending.
Cenovus Energy Investment Narrative Recap
Cenovus Energy appeals to investors who believe its oil sands and refining platform can keep throwing off cash even as emissions rules tighten. The Pathways CCS MOU does not change the near term swing factors. Operational reliability at key assets and any shift in WCS differentials still matter more to the next few quarters.
The bigger risk remains future earnings pressure as analysts expect profit to decline about 6% per year over three years while capital needs stay heavy. If CCS spending and carbon costs climb without matching efficiencies, Cenovus Energy could face tighter margins and less room for buybacks and dividends.
The Pathways CCS commitment links directly to one of the biggest overhangs on Cenovus Energy, specifically long term regulatory and carbon pricing uncertainty. A clearer framework on cost sharing, subsidies and carbon treatment would give investors a better line of sight on future compliance spending and the economics of any oil sands growth projects.
No other fresh corporate announcements sit alongside this MOU. This puts even more attention on execution milestones. Watch for whether binding agreements are signed by mid November 2026, how governments structure fiscal terms, and whether management adjusts capital allocation or project timelines once CCS economics are locked in.
Cenovus Energy is being sized up against a fairly cautious set of sell side forecasts. Analysts see revenue staying roughly flat and expect earnings to move from CA$6.7b today to about CA$6.1b by 2029, which implies an earnings decline of about CA$0.6b over that period. To line that up with current valuation work, the same models assume Cenovus Energy could generate around CA$54.9b of revenue and CA$6.1b of earnings by 2029, with the flat top line effectively meaning a 0% annual revenue growth rate over the next few years.
Uncover how Cenovus Energy's fair value indicates a 14% potential upside to its current price, which could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Pathways CCS news as a possible accelerator, not a drag. They were already modelling Cenovus Energy at about CA$56.8b of revenue and CA$6.9b of earnings by 2029. You can see how that more upbeat CCS catalyst might shift once those forecasts fully reflect this new MOU.
Explore 3 other Cenovus Energy fair value estimates, including one that suggests as much as 147% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cenovus Energy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cenovus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cenovus Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cenovus Energy?
If Cenovus Energy has you thinking about risk, cash generation and balance sheet strength, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- If capital preservation sits high on your list, compare Cenovus Energy with a wider set of resilient businesses by scanning our 9 resilient stocks with low risk scores.
- For investors focused on strong finances and cleaner balance sheets, weigh Cenovus Energy against companies in the list of solid balance sheet and fundamentals (7 results) and see which ones better match your comfort zone.
- If you are hunting for less followed opportunities, round out your watchlist by checking our 9 high quality undiscovered gems that combine quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com