
Discovering US Market's Undiscovered Gems October 2026
Over the last seven days, the United States market has experienced a slight decline of 1.0%, yet it remains up by 11% over the past year with earnings projected to grow by 17% annually. In this dynamic environment, identifying lesser-known stocks with solid fundamentals and growth potential can be key to uncovering opportunities that may not yet be fully appreciated by the broader market.
Top 10 Undiscovered Gems With Strong Fundamentals In The United States
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Insteel Industries | NA | -1.98% | -26.25% | ★★★★★★ |
| OptimumBank Holdings | 29.02% | 36.10% | 35.25% | ★★★★★★ |
| Perma-Pipe International Holdings | 31.47% | 11.47% | 32.99% | ★★★★★★ |
| ADMA Biologics | 48.16% | 37.59% | 68.92% | ★★★★★★ |
| TOYO | 36.72% | 208.58% | 54.90% | ★★★★★☆ |
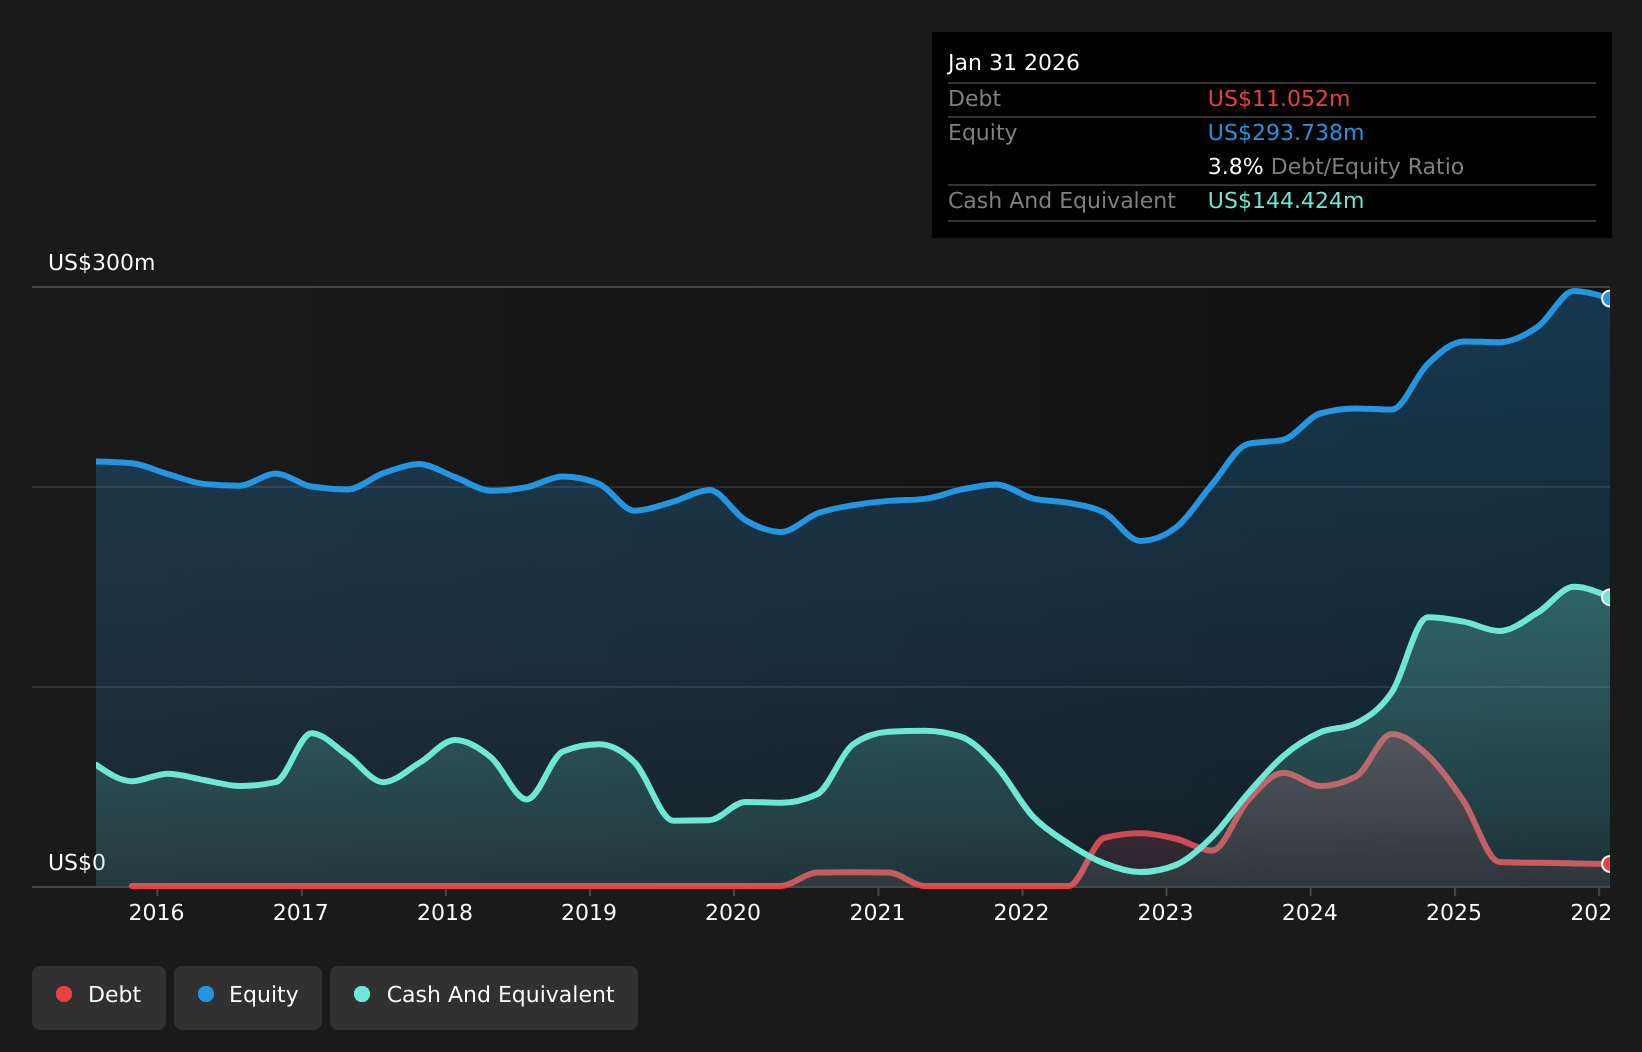
| Metropolitan Bank Holding | 3.80% | 10.49% | 5.16% | ★★★★★☆ |
| Kingstone Companies | 2.94% | 9.01% | 64.05% | ★★★★☆☆ |
| Pangaea Logistics Solutions | 68.85% | -2.42% | -25.03% | ★★★☆☆☆ |
| GDEV | NA | -1.59% | 54.97% | ★★★☆☆☆ |
| F&G Annuities & Life | 48.57% | 13.75% | -26.95% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
ADMA Biologics (ADMA)
Simply Wall St Value Rating: ★★★★★★
Overview: ADMA Biologics, Inc. is a biopharmaceutical company that develops, manufactures, and markets specialty plasma-derived biologics for treating immune deficiencies and infectious diseases globally, with a market cap of approximately $2.25 billion.
Operations: The company's primary revenue stream is from ADMA Biomanufacturing, contributing $494.71 million, with additional income from Plasma Collection Centers at $17.42 million.
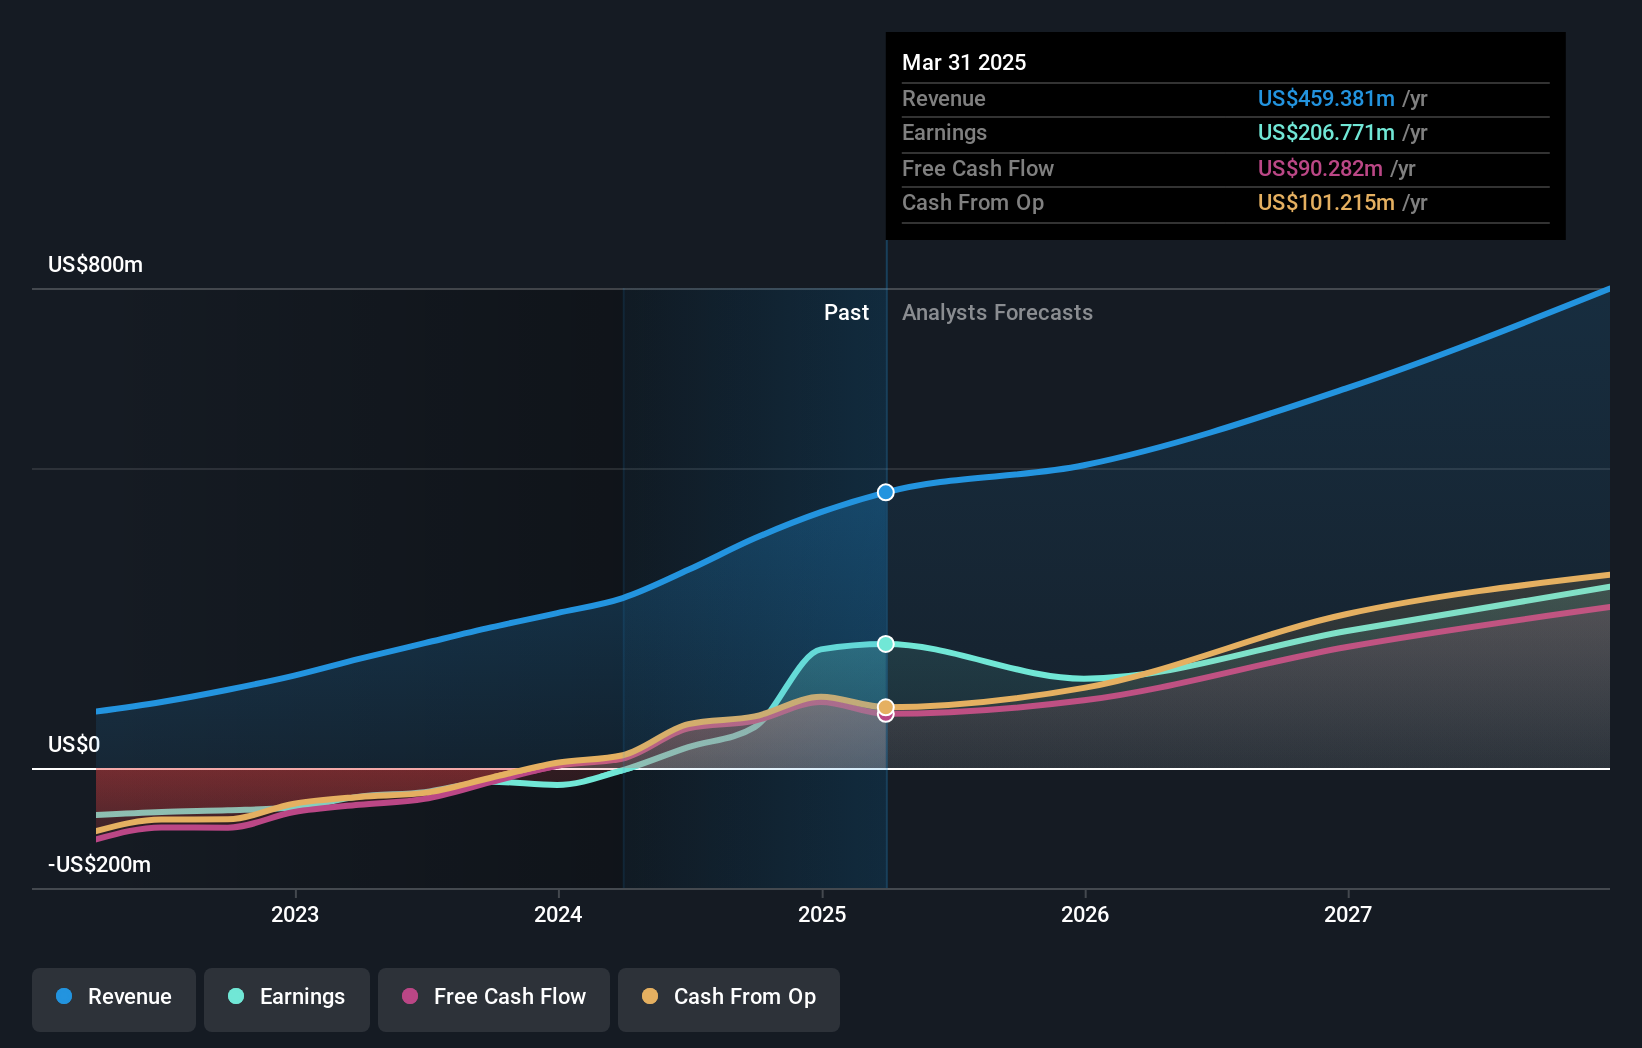
ADMA Biologics, a promising player in the biotech space, showcases a notable improvement in its financial health. The company's debt to equity ratio has impressively dropped from 84.1% to 48.2% over five years, reflecting prudent financial management. Trading at 72.1% below estimated fair value and offering high-quality earnings, ADMA is positioned attractively compared to industry peers. Recent earnings reveal a net income of US$37.82 million for Q2 2026, up from US$34.22 million the previous year, with basic EPS rising to US$0.17 from US$0.14, indicating robust profitability amidst strategic share repurchases totaling US$182.79 million since May 2025.
Daktronics (DAKT)
Simply Wall St Value Rating: ★★★★★★
Overview: Daktronics, Inc. specializes in designing, manufacturing, and selling electronic display systems for sports, commercial, and transportation sectors both domestically and internationally with a market cap of $836.33 million.
Operations: Revenue streams for Daktronics primarily include Live Events at $327.65 million, followed by Commercial and High School Park and Recreation segments, each generating approximately $178 million. The International segment contributes $88.22 million, while the Transportation segment adds $81.50 million to the total revenue.
Daktronics, a notable player in the electronics sector, has shown impressive earnings growth of 336% over the past year, significantly outpacing the industry average of 19%. Trading at a substantial 42.9% below its estimated fair value suggests it offers good relative value. The company recently repurchased shares worth US$4.41 million and is actively seeking acquisitions to boost inorganic growth. With high-quality earnings and more cash than debt, Daktronics seems well-positioned financially. Recent quarterly results highlighted increased sales to US$234.57 million and net income rising to US$19.43 million compared to last year’s figures, indicating solid performance momentum.
- Dive into the specifics of Daktronics here with our thorough health report.
Review our historical performance report to gain insights into Daktronics''s past performance.
F&G Annuities & Life (FG)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: F&G Annuities & Life, Inc. operates in the United States offering annuity and life insurance products, with a market capitalization of approximately $2.84 billion.
Operations: F&G generates revenue primarily from its life insurance segment, which accounted for $6.07 billion.
F&G Annuities & Life, a relatively small player in the insurance sector, has been generating interest with its strategic moves and financial performance. Recently, the company repurchased 3.33 million shares for US$90.68 million, signaling confidence in its valuation. Despite a net loss of US$76 million in Q2 2026 compared to a net income of US$40 million the previous year, F&G reported earnings per share improvement over six months from US$0.08 to US$1.24. With earnings growth projected at 18% annually and trading at a discount of 33% below estimated fair value, it presents intriguing potential for investors seeking undervalued opportunities.

Make It Happen
- Embark on your investment journey to our 21 US Undiscovered Gems With Strong Fundamentals selection here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com