
What KWS SAAT SE KGaA Earnings Results Means For Shareholders
- KWS SAAT SE & Co. KGaA reported full year 2026 results, with sales of €1,626.82 million, net income of €160.84 million, and basic earnings per share of €4.87.
- The mix between lower sales and net income, together with higher basic earnings per share from continuing operations, highlights how portfolio and one off effects are reshaping KWS SAAT SE & Co. KGaA's earnings profile.
- We will now examine how KWS SAAT SE & Co. KGaA's weaker full year net income reshapes the existing investment narrative around the stock.
KWS SAAT SE KGaA Investment Narrative Recap
To own KWS SAAT SE KGaA, you need to be comfortable with a seeds specialist that leans heavily on its sugarbeet and cereals activities while working through weaker areas such as corn, cereals exposure to Russia and vegetables. The latest results show lower sales and net income but higher earnings per share from continuing operations. That suggests portfolio mix and past divestments are doing some work in the background.
The near term swing factor is whether operational execution in pressured segments like corn and vegetables stabilises while R&D output keeps supporting the sugarbeet pipeline. The biggest current risk is that headwinds in corn, Russian cereals and vegetable amortisation pressure persist, which would limit any benefit from better product mix or past deleveraging. The new figures do not appear to change that risk balance in a major way.
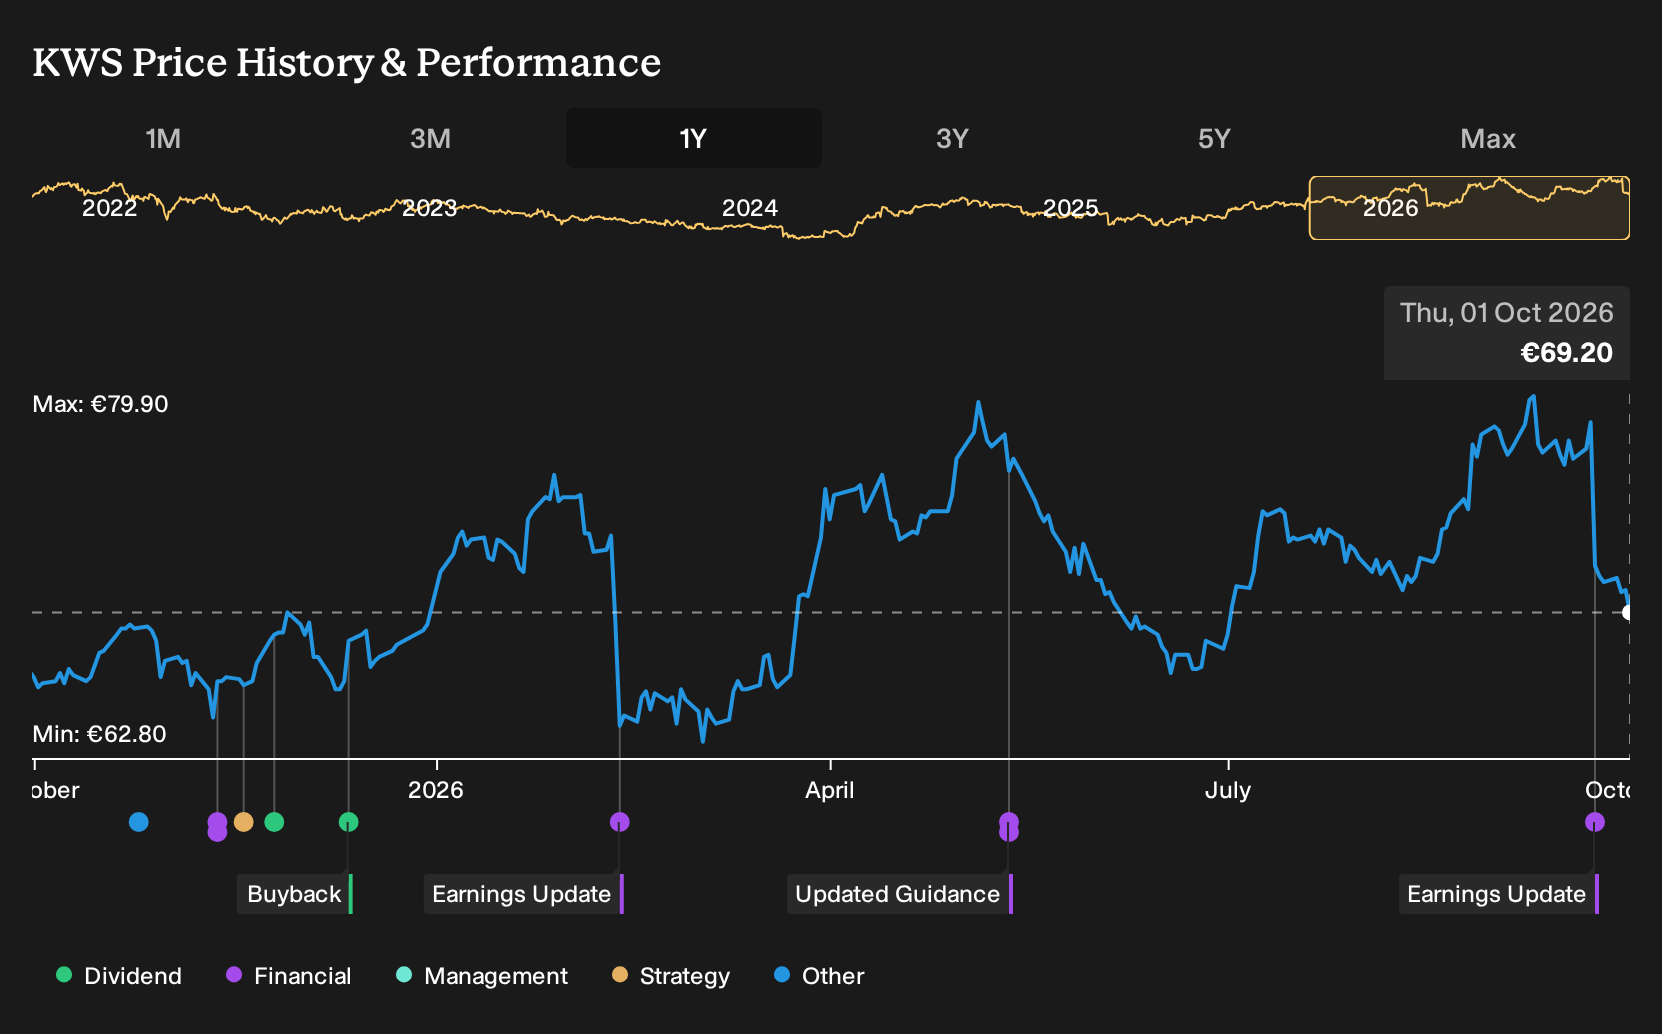
The full year earnings announcement for the year to June 30, 2026 sits at the centre of the current story. Sales of €1,626.82 million and net income of €160.84 million came in below the prior year, while basic earnings per share from continuing operations moved up to €4.80. For you as a shareholder, it means the quality of earnings and capital allocation matter as much as the headline profit drop.
This report is where you test the earlier catalysts around sugarbeet expansion, divestments and R&D against real numbers. Lower profit and unchanged sugar price volatility keep risk on future revenue stability very real, especially when corn and cereals already carry structural questions. Any improvement in financial leverage or product approvals now needs to filter through cleanly to future reports to keep the long term thesis intact.
KWS SAAT SE KGaA's current earnings of €157.2 million are set against analyst projections that point to €1.8b in revenue and €212.9 million in earnings by 2029. This implies forecast revenue growth of 3.1% a year and an earnings increase of about €55.7 million from today.
Uncover how KWS SAAT SE KGaA's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community supplies two fair value views that run from about €84 up to roughly €188, so retail expectations for KWS SAAT SE KGaA are wide apart. When you combine that spread with recent earnings pressure in corn and cereals plus sugarbeet and R&D driven product plans, you get sharply different opinions you should compare directly.
Explore another KWS SAAT SE KGaA fair value estimate, including one that suggests it could be worth just €84.25!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KWS SAAT SE KGaA research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for KWS SAAT SE KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KWS SAAT SE KGaA's overall financial health at a glance.
Looking For More Investment Ideas Beyond KWS SAAT SE KGaA?
If KWS SAAT SE KGaA is only one part of your watchlist, it can help to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who want income at the front of the story rather than the back, scan through a set of higher yield opportunities with 166 dividend fortresses.
- If capital preservation sits at the top of your checklist, compare KWS SAAT SE KGaA with a 226 resilient stocks with low risk scores to see which businesses line up better with your comfort level.
- When you want quality balance sheets supporting the equity story, work through a list of solid balance sheet and fundamentals (207 results) that can sit alongside your existing holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com