
3 UK Stocks Retail Investors May Revisit If EU Ties Start To Warm
An EU referendum story is creeping back into U.K. politics and that kind of long, messy uncertainty often distorts pricing in mid and small caps that are tightly linked to the domestic economy. When sentiment swings around big headline risks, some UK-listed stocks exposed to U.K.–EU relations can be marked down or ignored. This article examines three such domestically focused shares from our screener and outlines how each might be positioned if the relationship with Europe shifts toward closer ties again.
The three stocks below are a sample from this idea. The full screen surfaced 18 more UK mid and small caps with similarly detailed stories that are not covered here. To see everything at once, head into the UK Mid- and Small-Cap Domestic Re-Rating Plays screener to analyze, filter, and identify the domestic re rating plays that best fit your own thesis.
DFS Furniture (LSE:DFS)
DFS Furniture is a pure U.K. consumer play in the screener, with sofas and upholstered furniture directly tied to how confident households feel about spending on their homes.
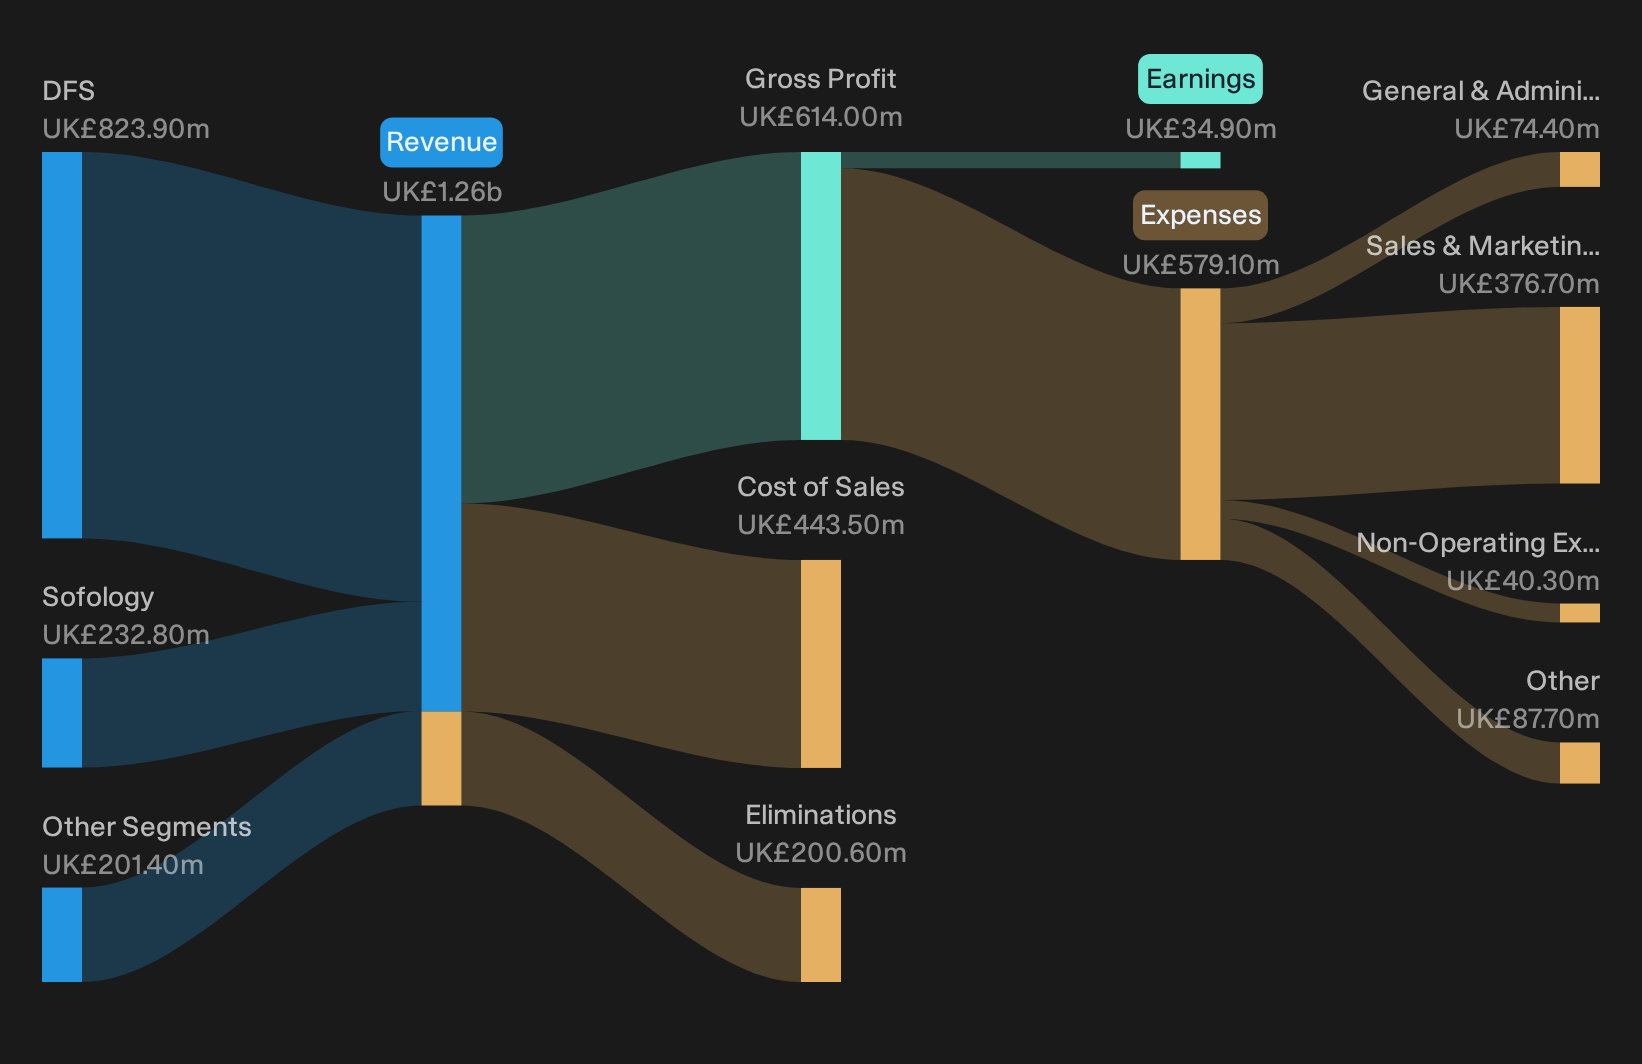
DFS Furniture designs, manufactures, delivers and sells sofas and other upholstered furniture across the DFS and Sofology brands, making it a textbook U.K. domestic consumer stock. Revenue is largely driven by DFS at about £824 million, with Sofology contributing roughly £233 million and other segments around £201 million, and the group currently has a market value of roughly £335 million.
Although the group is using its 39% market share and exclusive brand partnerships to support order intake, the upholstery market is described as subdued and around 20% below pre pandemic volumes.
The key question for DFS Furniture is what happens if that one pressure on big ticket spending finally starts to ease, as this is where the potential for a re rating really sits.
If that reset matters to your thesis, read the full narrative for DFS Furniture to see how DFS Furniture could respond if big ticket demand accelerates again.
Regional REIT (LSE:RGL)
Regional REIT plugs directly into the screener theme as a pure UK regional office landlord, where rental income, valuations and sentiment all lean heavily on domestic business confidence and any shift in how investors price UK political and currency risk.
Regional REIT is a UK focused real estate investment trust with a £138 million market cap, owning income producing regional commercial properties that generated about £73 million from its REIT commercial segment, offering concentrated exposure to offices and business space outside the M25.
For investors watching how UK regional demand might respond if the political mood music with Europe improves, Regional REIT brings a more income oriented angle to the re rating story than the consumer and cyclicals in the same screen.
Intensifying shortage of high quality regional office space, as new developments stall and older stock is repurposed, positions Regional REIT’s upgraded assets for stronger pricing power and higher rental income growth over the medium term.
What happens to that income path now largely hinges on how one unseen pressure in the financing mix interacts with the rental story ahead.
That financing wildcard is exactly what the full narrative for Regional REIT unpacks, showing how Regional REIT could decouple if funding costs and rental momentum start to move in different directions.

Halfords Group (LSE:HFD)
Halfords Group is a pure U.K. consumer cyclical in this screener, with all £1.8b of sales earned at home and heavily tied to how confident people feel about driving, cycling and travelling as domestic conditions and perceptions of U.K. risk gradually shift.
Halfords Group runs a broad motoring and cycling retail chain alongside a nationwide Autocentres garage network, with about £1,062 million of revenue from Retail and £740 million from Autocentres, and the stock currently valued at roughly £570 million.
For a screen built around U.K. domestic re rating potential, Halfords Group offers a mix of everyday spending on cars and bikes that tends to move with real incomes and travel habits, which is exactly where any change in sentiment around closer EU ties could start to show up in the numbers.
"Intensifying shift to e-commerce and direct-to-consumer models is set to further erode footfall in Halfords' physical stores, undermining store-based sales growth and operating leverage, which may drag on group revenue and reduce margin resilience as digital-native competitors scale faster."
What happens to the balance between higher margin services and more pressured store sales will matter far more than any headline about U.K.–EU politics.
That pivot will decide whether Halfords Group slowly grinds or quietly accelerates, so read the full narrative for Halfords Group to see how services, stores and sentiment could really interact.

Curious About Fresh Market Alternatives
Some of the sharpest breakouts start quietly while momentum is still under the radar for now. Scan these fresh ideas before the crowd catches on and act now.
- Spot resilient cash generators before momentum really flies by scanning the curated list of solid balance sheet and fundamentals (9 results) that filters out weak balance sheets and fragile fundamentals.
- Ride powerful income themes while yields remain elevated through the hand picked 1 dividend fortresses designed for investors who want payouts backed by sturdy financial profiles.
- Position ahead of the next infrastructure build out cycle by reviewing the focused 39 power grid technology and infrastructure stocks featuring businesses tied directly to grid upgrades and electrification demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com