
3 Energy Security Stocks Retail Investors Are Watching For LNG And Pipeline Exposure
Energy security is back on center stage as geopolitical unrest, shifting supply routes, and new environmental rules collide, and that mix is reshaping how investors think about storage, terminals, and the pipes that keep fuel and data flowing. Market swings can punish the unprepared and reward those who understand where the pressure points sit. This article unpacks that story and introduces 3 stocks exposed to these news catalysts.
The three stocks covered next are just a sample of the Global Energy Security Infrastructure and Storage Providers idea. The full screen surfaces 26 more companies whose balance sheets, assets, and business models tell equally compelling stories around energy logistics and storage. To identify and analyze the highest conviction fits for your own watchlist, go straight to the Global Energy Security Infrastructure and Storage Providers screener.
Eneva (BOVESPA:ENEV3)
Overview: Eneva is a Brazilian integrated energy company that produces natural gas and liquids and supplies fuel and power solutions, including LNG regasification and floating storage, to electricity generators, pipeline operators, and industrial clients.
Operations: Eneva earns most of its revenue from energy trading of about R$8.7b and Sergipe's Hub of about R$4.2b, alongside coal, solar, gas generation and LNG activities.
Market Cap: R$53.6b
Eneva matters for this energy security screen because it links gas production directly with power plants and LNG handling. This gives investors exposure to the infrastructure that keeps Brazil’s grid supplied when conditions tighten.
"The rapid build out of LNG infrastructure and expansion of the Sergipe Hub and Parnaíba liquefaction capacity increases fixed costs and contractual obligations in a market that could face lower merchant margins if gas or power price spreads narrow."
What happens to Eneva’s appeal depends on how this expanding gas infrastructure interacts with one unresolved pressure on future cash generation.
That unresolved pressure point is exactly what the full narrative for Eneva unpacks, highlighting where Eneva’s expanding footprint could be masking accelerating strengths or future capital strain.

Gas Malaysia Berhad (KLSE:GASMSIA)
Overview: Gas Malaysia Berhad runs a nationwide natural gas and LPG distribution network in Peninsular Malaysia, supplying industrial, commercial, and residential customers.
Operations: The business generated about MYR 6.9b from its Natural Gas & LPG segment in Malaysia, effectively all reported revenue for the year.
Market Cap: MYR 6.2b
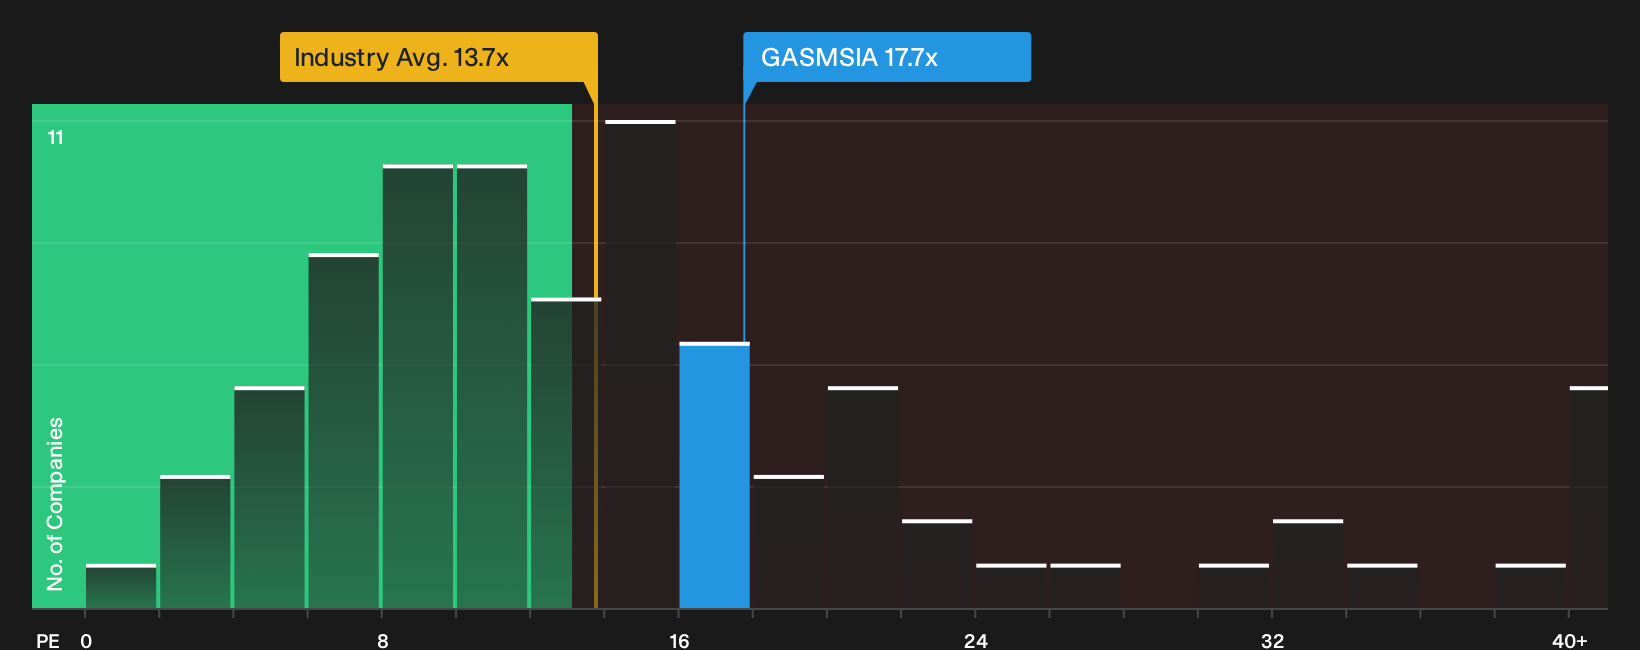
Gas Malaysia Berhad links Malaysia’s factories, businesses, and homes to secure gas supply, which fits neatly with an energy security and storage theme. Investors get exposure to essential distribution pipes and reticulation systems in a single, Malaysia focused network. What happens to cash returns from that grid depends on how one unseen pressure on dividend coverage and funding costs develops.
That pressure point on dividend cover makes it worth scanning the 1 key reward and 2 important warning signs (1 is major!) to see how yield strength stacks up against funding and regulatory risks
Sino Prima Gas Technology (SZSE:300483)
Overview: Sino Prima Gas Technology develops, transports, and sells natural gas across China through its own transmission, pressurization, and pipeline services.
Market Cap: CN¥8.8b
Sino Prima Gas Technology provides exposure to the midstream gas infrastructure that helps keep supply moving when geopolitical shocks affect pipelines and ports. Earnings are forecast to grow quickly while the shares trade at a discount to estimated fair value. However, future returns may depend on how the company’s significant reliance on debt funding influences cash flow resilience and pricing power.
If that debt load is the real swing factor, the 3 key rewards and 1 important major warning sign shows where Sino Prima Gas Technology’s funding risk could be decoupling from its growth story.

Curious About Fresh Investing Alternatives
Markets move fast and early movers often catch potential breakouts while others chase momentum after it is already moving. Scan fresh ideas that may be under the radar for now and consider them promptly.
- Spot resilient cash generators before they are widely talked about by running the list of solid balance sheet and fundamentals (207 results) while the data still offers an early look.
- Target income streams that could help steady a portfolio by reviewing carefully filtered 159 dividend fortresses before yields are affected by yield-focused buyers.
- Explore opportunities related to the infrastructure behind AI demand by checking hand picked 90 AI infrastructure stocks and see which operators are gaining attention while it may still be timely.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com