
Adyen (ENXTAM:ADYEN) Dropped, So What Is Behind The Fresh Attention?
Adyen (ENXTAM:ADYEN) drew fresh attention after hiring outgoing Klarna finance chief Niclas Neglen as its next CFO and management board member, with interim CFO Hwa Tsao shifting to senior vice president of group finance.
The leadership change comes at a tricky moment for Adyen, with the share price at €855.6 after declining 15% over the past 30 days and falling 38.76% year to date. At the same time, the 3 year total shareholder return of 20.88% contrasts with a 41.24% decline over the past twelve months, suggesting long term holders have seen gains compress and recent momentum fade as investors reassess growth and risk around the business.
Compare Adyen's reset with a hand picked group of resilient payment and fintech players by scanning the list of solid balance sheet and fundamentals (207 results) for potential alternatives and complements in your portfolio.
After a drop of more than 40% over the past year, yet with 3 year returns still positive, Adyen now sits at a crossroads. Does that reset finally tilt the risk reward back toward buyers, or not?
Most Popular Narrative: 12% Undervalued
On the narrative view, Adyen's fair value of €974.81 sits meaningfully above the last close at €855.6, which puts fresh focus on whether recent share price weakness has gone too far or if the reset still reflects open questions on execution and margins.
My thesis is that Adyen’s business is stronger than the recent market mood implies, but the stock is not obviously cheap enough for that strength to create a large margin of safety. At around €886, I get to a base-case fair value of roughly €900 per share after adjusting my DCF for execution risk, FX noise, and integration risk. That is not a big disconnect. So this is not a “the market is completely asleep” setup. It is a more nuanced call: I think the market is underestimating free cash flow durability, but not by enough to make the stock clearly mispriced today.
See why 14 investors see Adyen as 12% undervalued.
Result: Fair Value of €974.81 (UNDERVALUED)
Still, two pressure points could flip that story for Adyen fast. Slower uptake of new products, or any stumble integrating Talon.One and Orb, would hurt confidence.
Find out about the key risks to this Adyen narrative.
Another View On Adyen's Valuation
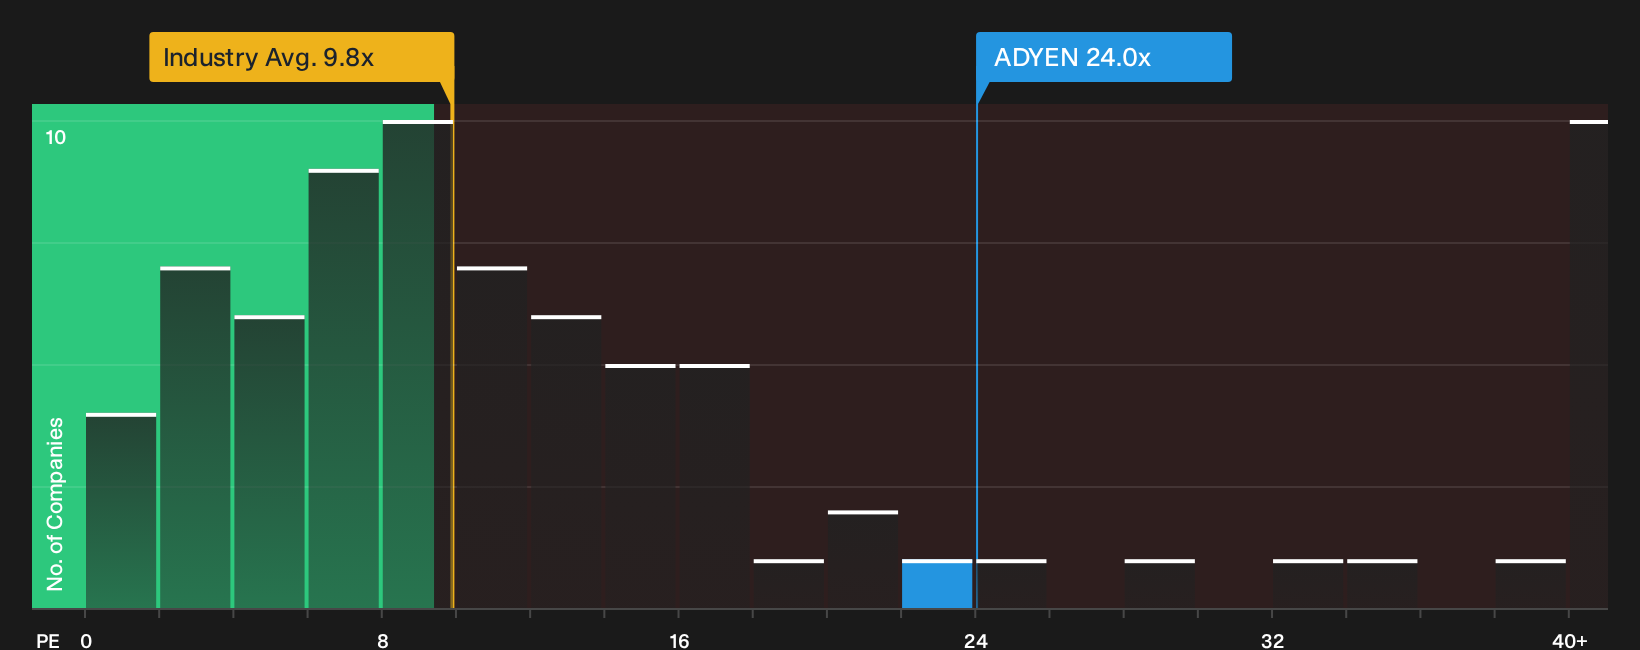
On simple earnings multiples, Adyen screens far less generous. The stock trades on a P/E of 24x, compared with a fair ratio of 20.5x and peer averages around 16x and 9.8x. That gap points to clear de rating risk if growth or execution wobbles again.
For investors weighing that trade off, the valuation breakdown can help put the current premium into context and show whether the numbers still justify paying up for quality, or if patience makes more sense here, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn on Adyen after this mix of setbacks and support factors? Act quickly by checking the full picture of both sides with 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Adyen?
If Adyen has you reassessing your options, do not stop here. Use the Simply Wall Street Screener to surface fresh ideas that match your goals.
- Target resilient quality by scanning a 224 resilient stocks with low risk scores that already clears strict risk filters and balance sheet checks.
- Hunt for mispriced potential with a 617 high quality undiscovered gems that highlights financially solid businesses the market has not fully focused on yet.
- Anchor your watchlist in fundamentals with a 158 dividend fortresses that pairs higher yields with underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com