
EcoGraf Leads The Charge With 2 Other ASX Penny Stocks
The Australian market is experiencing heightened volatility, with recent sell-offs and global tensions impacting investor sentiment. Despite this uncertainty, penny stocks continue to attract attention for their potential growth opportunities. Often associated with smaller or newer companies, these stocks can offer significant upside when supported by strong financials and solid fundamentals.
Let's dive into some prime choices out of the screener.
EcoGraf (ASX:EGR)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: EcoGraf Limited focuses on exploring and producing graphite products for the lithium-ion battery and advanced manufacturing markets in Tanzania and Australia, with a market cap of A$133.85 million.
Operations: The company generates revenue from its operations in Tanzania and Australia, with A$0.40 million from Tanzania and A$2.69 million from Australia.
Market Cap: A$133.85M
EcoGraf Limited, with a market cap of A$133.85 million, is navigating the challenges typical of penny stocks. It remains pre-revenue, generating less than US$1 million annually. Despite reducing losses by 15% per year over five years, it reported a net loss of A$2.19 million for the year ending June 2026. Recent equity offerings raised A$3.552 million to bolster its cash runway beyond six months and support ongoing projects in Tanzania and Australia. The company faces going concern doubts from auditors but has promising exploration projects and strategic agreements that could enhance future revenue streams if successfully executed.
- Click here and access our complete financial health analysis report to understand the dynamics of EcoGraf.
- Gain insights into EcoGraf's historical outcomes by reviewing our past performance report.
K&S (ASX:KSC)
Simply Wall St Financial Health Rating: ★★★★☆☆
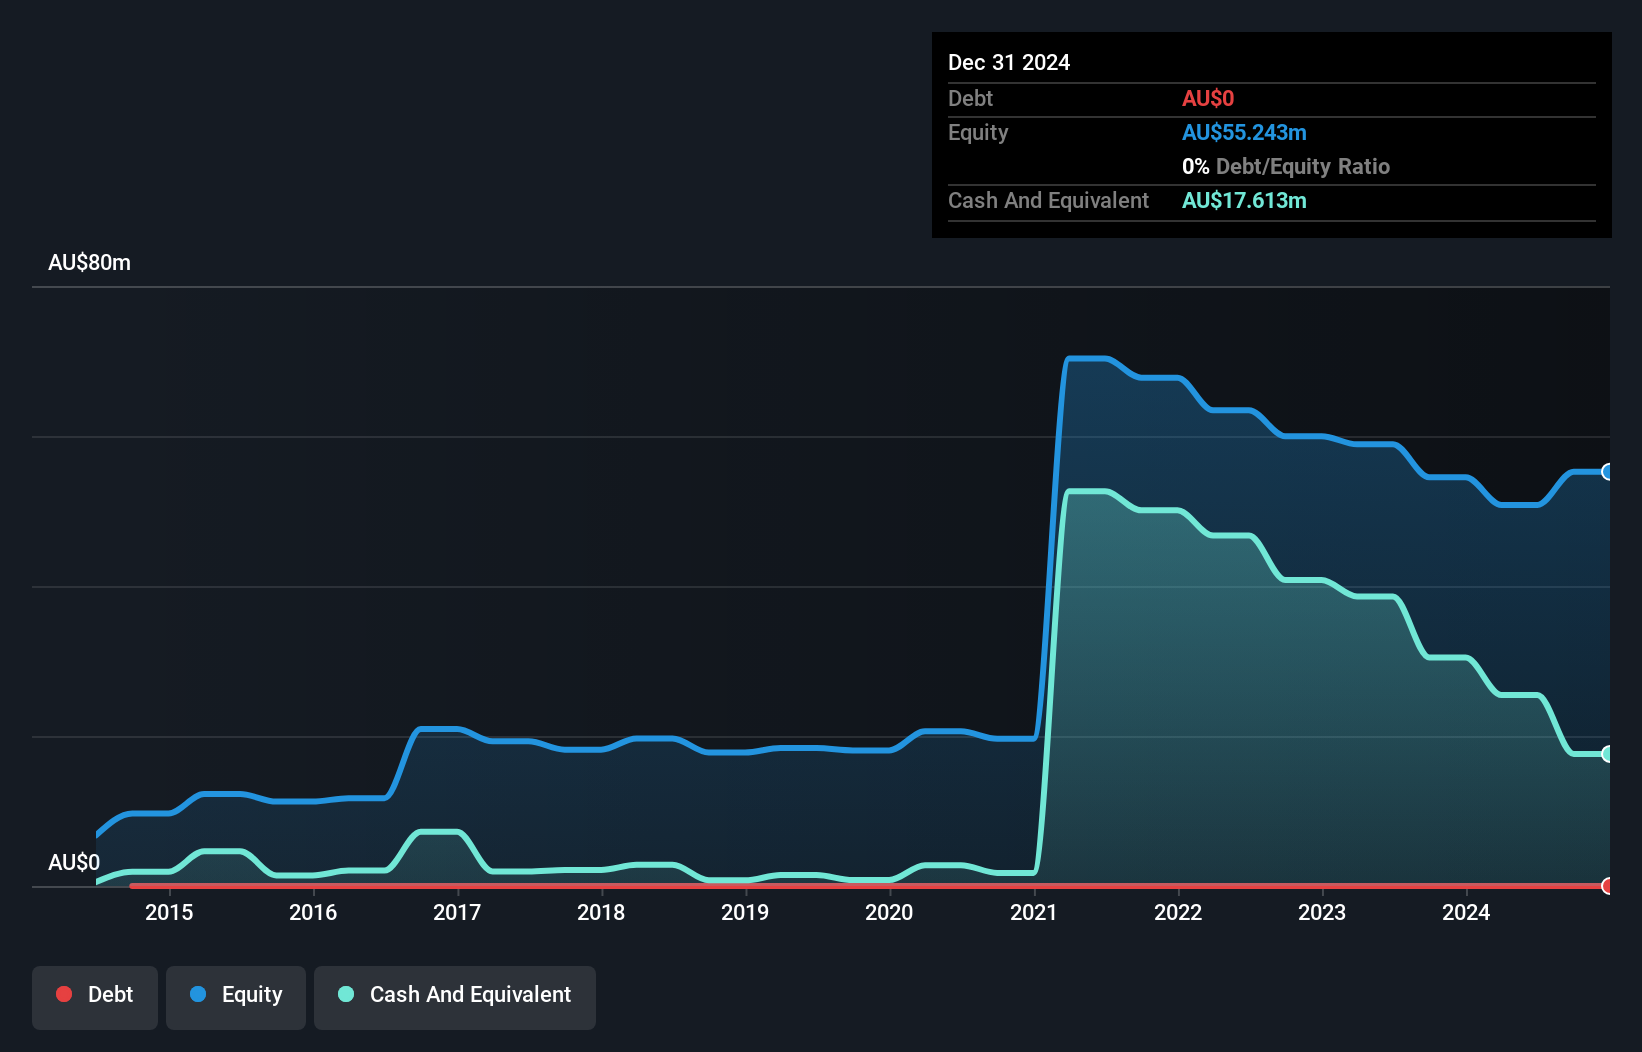
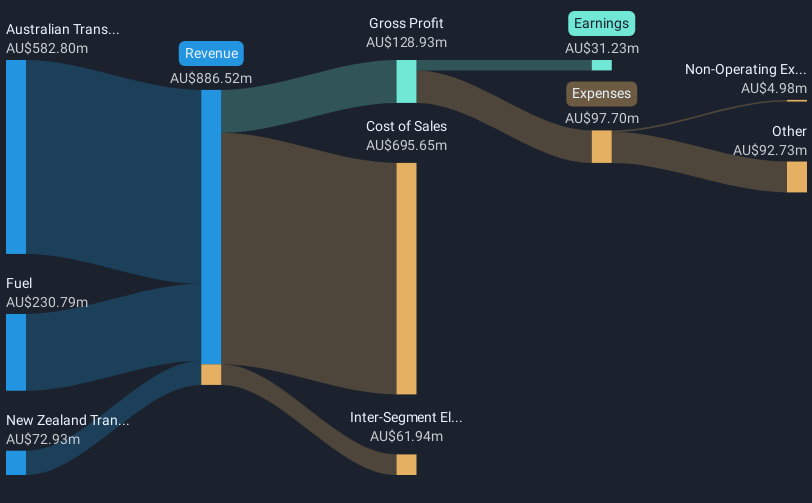
Overview: K&S Corporation Limited offers transport and logistics solutions in Australia and New Zealand, with a market cap of A$433.81 million.
Operations: The company's revenue is primarily derived from Australian Transport at A$496.64 million, followed by Fuel at A$203.28 million, and New Zealand Transport contributing A$79.01 million.
Market Cap: A$433.81M
K&S Corporation Limited, with a market cap of A$433.81 million, is experiencing challenges typical for its category. The company reported a decline in revenue to A$738.61 million and net income to A$22.78 million for the fiscal year ending June 2026, alongside reduced profit margins and earnings per share compared to the previous year. Despite these setbacks, K&S maintains high-quality earnings and has not diluted shareholders recently. While its dividend yield of 3.47% is not covered by free cash flow, debt levels are well-managed with satisfactory coverage by operating cash flow and interest payments supported by EBIT.
- Jump into the full analysis health report here for a deeper understanding of K&S.
- Examine K&S' past performance report to understand how it has performed in prior years.
VEEM (ASX:VEE)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: VEEM Ltd designs, produces, markets, and sells precision engineered products across Australia, the United States, Sweden, Italy, and the United Kingdom with a market cap of A$77.78 million.
Operations: The company's revenue is derived entirely from its Machinery & Industrial Equipment segment, totaling A$51.73 million.
Market Cap: A$77.78M
VEEM Ltd, with a market cap of A$77.78 million, faces challenges typical for its category as it navigates financial difficulties. The company reported a significant decline in revenue to A$51.73 million and a net loss of A$17.81 million for the fiscal year ending June 2026, reflecting increased losses over the past five years. Despite being unprofitable, VEEM's debt is well-managed with more cash than total debt and short-term assets exceeding both short and long-term liabilities. However, its recent removal from the S&P/ASX Emerging Companies Index highlights ongoing volatility concerns for investors in this sector.
- Click here to discover the nuances of VEEM with our detailed analytical financial health report.
- Review our growth performance report to gain insights into VEEM's future.

Next Steps
- Dive into all 399 of the ASX Penny Stocks we have identified here.
- Ready For A Different Approach? Outshine the giants: these 18 early-stage AI stocks could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com