
Nueva Expresión Textil (BME:NXT) Stock Price Pullback Meets Rich Recovery Valuation
Traders treated Nueva Expresión Textil like yesterday’s story. The share price has been under pressure, down about 5% over the past week and roughly 9% over the month, even before absorbing the latest numbers.
The fresh H1 2026 report presents a different picture. The textile group reported Total Revenue of €29.463m and Net Income of €3.001m, with Basic EPS at €0.007. That profit figure now sits alongside a P/E of 126.3x, which keeps the focus on earnings quality and how much investors are willing to pay for this recovery story.
Is Nueva Expresión Textil’s 126.3x P/E signalling a premium story that the recent share pullback has misunderstood, or a fragile recovery priced for perfection? Compare that rich multiple against cash flows and peers in the valuation analysis for Nueva Expresión Textil.
H1 2026 Earnings Summary
- Total Revenue (H1 2026 vs. H1 2025): €29.463m vs. €16.349m (reflecting a higher reported level year on year)
- Net Income (Excl. Extra Items, H1 2026 vs. H1 2025): €3.001m vs. €1.273m (reflecting a higher reported profit level year on year)
- Basic EPS (Earnings Per Share, H1 2026 vs. H1 2025): €0.007 vs. €0.0032 (reflecting a higher earnings figure per share year on year)
- Trailing 12-Month Net Profit Margin (H1 2026 vs. prior year): 12.1% vs. 12.6% (indicating a slightly lower margin on a trailing basis)
Prefer clean charts instead of another wall of earnings tables and footnotes? See Nueva Expresión Textil’s full visual breakdown, including how the current valuation compares, in the company report for Nueva Expresión Textil.
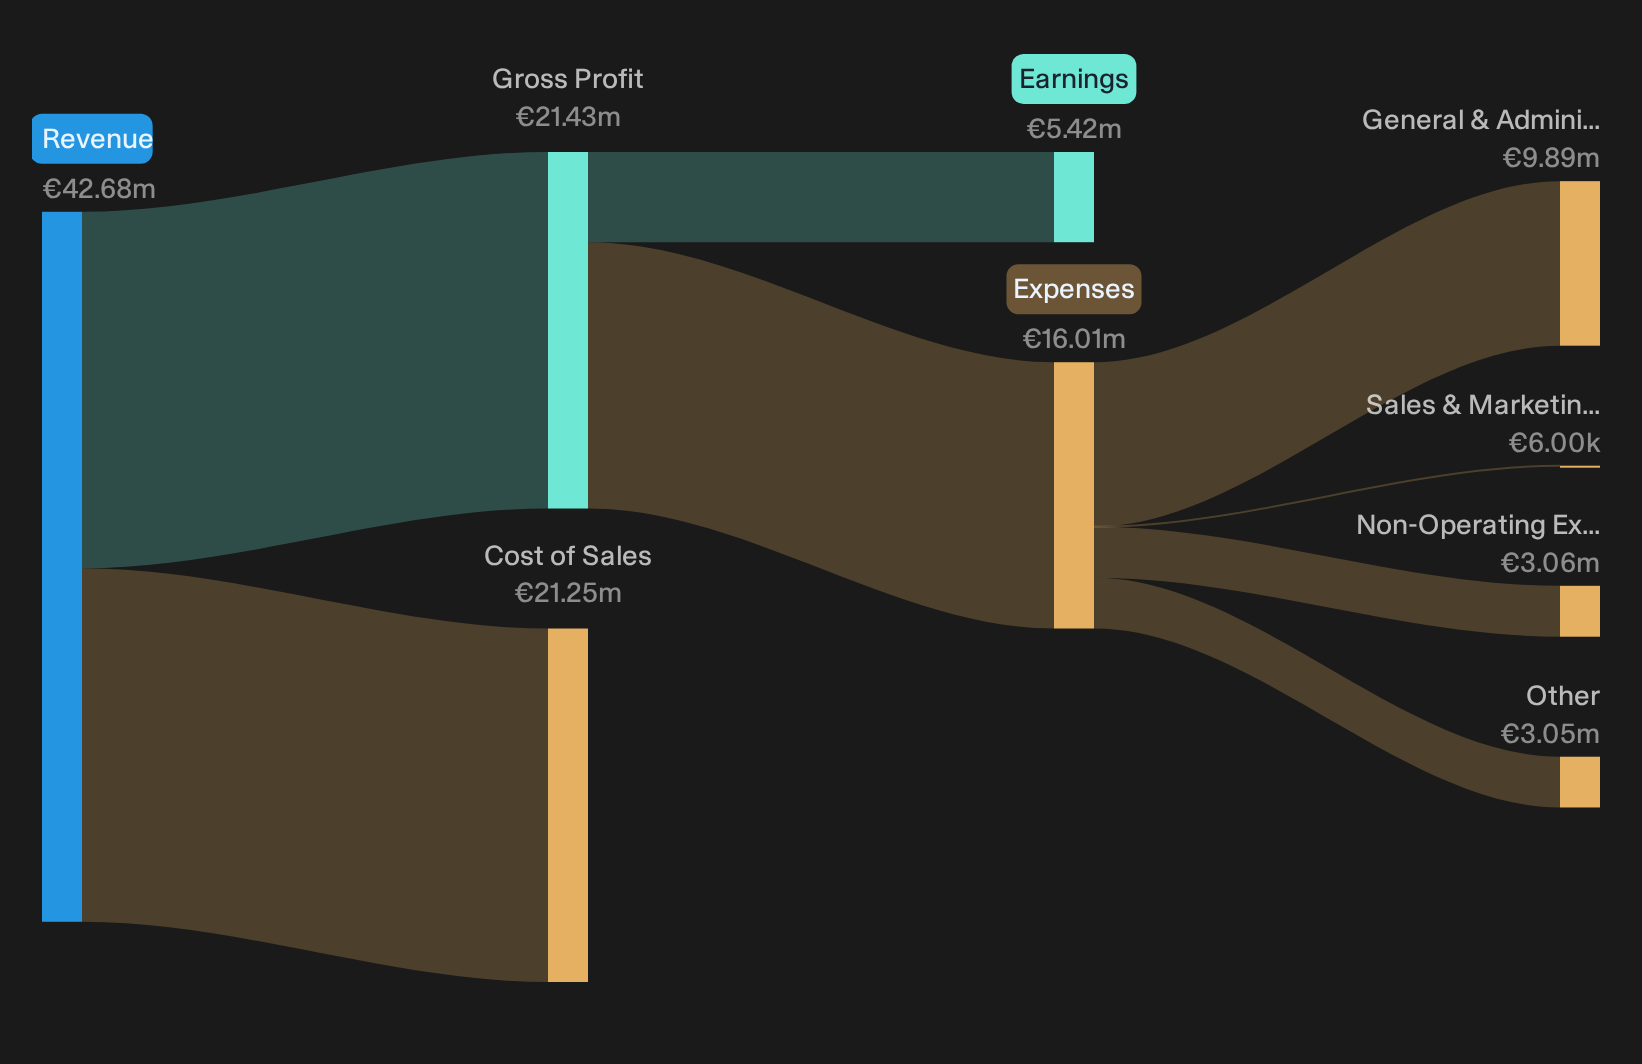
Nueva Expresión Textil: Signals Supporting The Upside Story
On the bullish side, Nueva Expresión Textil now pairs €29.463m in H1 2026 revenue with €3.001m of net income, which is a healthier profit figure than the previous year’s half. That shift suggests the technical and medical textile positioning is at least earning its keep. The trailing 12.1% net margin, only slightly below the prior 12.6%, points to broadly intact economics even as the share price has drifted lower in recent weeks.
Where The Nueva Expresión Textil Bear Case Still Bites
The cautious view does not disappear. Profitability on a trailing basis has softened a touch, with net margin easing to 12.1% from 12.6%, which keeps questions about cost pressure and pricing power alive in a competitive textile arena. Recent share performance, down over the past 7, 30 and 90 days, shows that investors are not yet treating this recovery as a done deal, despite the higher reported earnings level.
After a period of margin cooling and a share price that has slipped, it helps to know if this is isolated or part of deeper structural issues. Review the independent risk analysis for Nueva Expresión Textil which shows 3 important warning signs to see whether these concerns hint at broader vulnerabilities that management has yet to fully address.Take Control Of Your Next Move
If Nueva Expresión Textil’s sharp valuation contrast and recent share pullback have your attention, register for free with Simply Wall St and add it to a Watchlist so you can watch price against fair value and wait for your preferred entry point. After you commit capital, keep the focus on what matters by tracking your holdings through the Portfolio Command Center, which filters out market noise and flags key updates that might affect your thesis. For longer term decisions, compare your thinking with thousands of other investors inside the Community and see how sentiment shifts as new information lands. By spotting potential catalysts and emerging risks early, you give yourself a better chance of staying ahead of the market instead of reacting to it late.
Seeking Alternatives Beyond Nueva Expresión Textil?
Fresh ideas can move quickly. Some gain momentum quietly, then start breaking out while most investors are still caught watching yesterday’s stories. Scan these curated lists before the crowd and act now.
- Spot resilient compounders early and review a curated 223 resilient stocks with low risk scores that helps you focus on stocks where downside risk scores stay contained while upside stories are still forming.
- Ride structural electricity demand and assess a hand picked 39 power grid technology and infrastructure stocks designed for investors watching grid upgrades, transmission capacity and hardware suppliers before momentum really starts flying.
- Target real-world AI adoption and investigate carefully filtered 131 healthcare AI stocks where algorithms meet hospitals, diagnostics and treatment workflows that remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com