
5N Plus (TSX:VNP) Could Be 28% Undervalued After Its 50% Utah Expansion Plan
5N Plus (TSX:VNP) just laid out plans to expand its St. George, Utah facility by about 50%. This move puts fresh attention on its advanced materials exposure across defence, space solar, medical imaging and industrial sensing.
Recent trading has been volatile for 5N Plus, with the share price up 32.85% over the past month but down 25.27% over the last 90 days. The year-to-date share price return sits at 78.39%, and the 1-year total shareholder return is 85.61%, pointing to strong longer term momentum despite shorter term swings.
Scan beyond 5N Plus and line up other advanced materials and critical mineral players using our curated 33 best rare earth metal stocks.
5N Plus now trades about 42% below the average analyst target, yet its own intrinsic fair value gauge points to only a small premium. Is the discount a genuine opportunity, or is the market simply pricing in risk more sharply?
Most Popular Narrative: 28% Undervalued
On Simply Wall St’s most followed narrative, 5N Plus screens as undervalued, with a fair value of CA$44.76 against a last close of CA$32.11. That gap rests on the idea that contracted demand in solar and space can support earnings and cash flows for years.
Ongoing capacity expansions and record backlog in both terrestrial renewable energy and space power sectors (booking out to 2029-2031) reflect increasing global demand for high-purity specialty materials as electronics, IoT, and digital infrastructure markets scale. These trends underpin long-term revenue visibility, lower customer concentration risk, and improve stability in cash flows.
See why 24 investors see 5N Plus as 28% undervalued.
Result: Fair Value of CA$44.76 (UNDERVALUED)
Still, a sharp policy reversal, such as reduced clean energy support, or a setback with a key customer like First Solar could quickly challenge that undervaluation story.
Find out about the key risks to this 5N Plus narrative.
Another View On 5N Plus Valuation
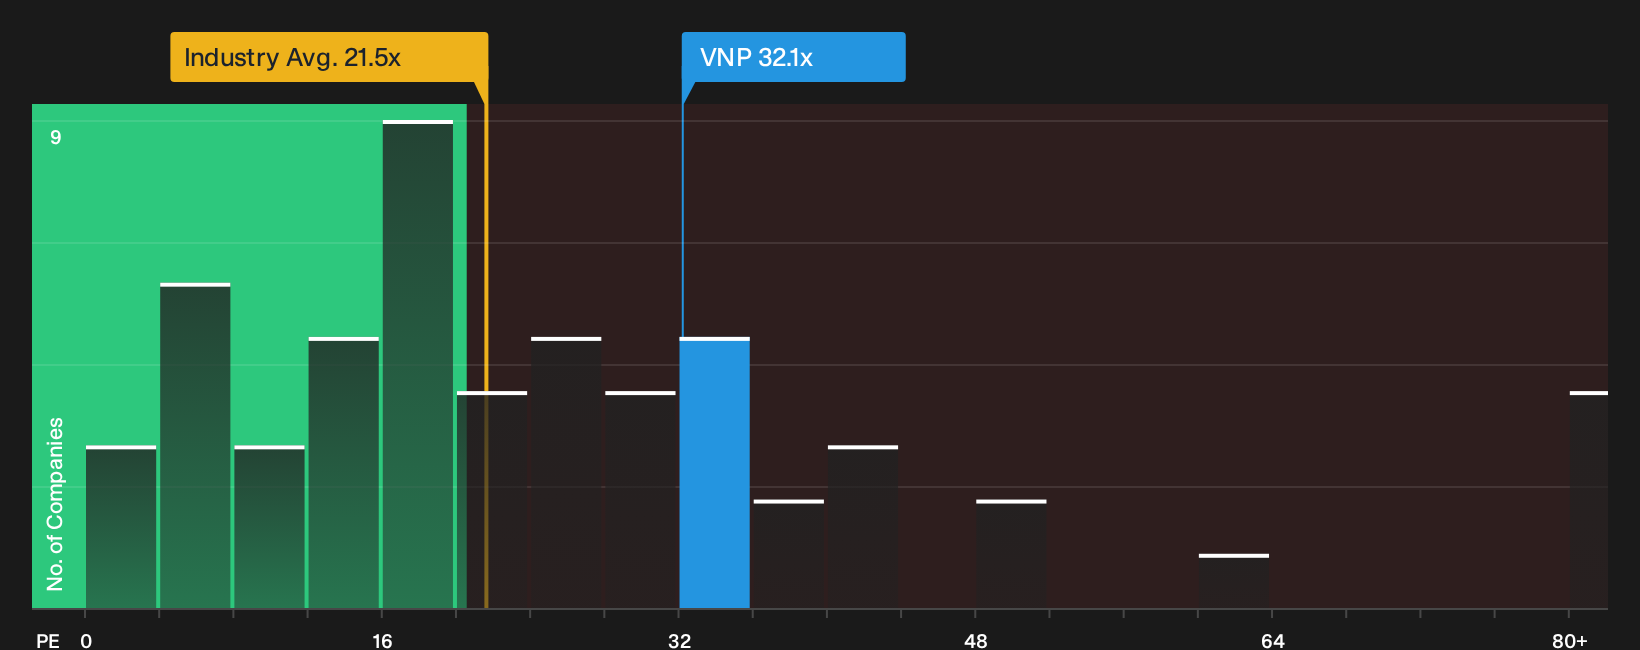
The fair value story for 5N Plus looks very different once the focus shifts from future cash flows to what investors are actually paying for current earnings. The stock trades on a P/E of 32.1x, while peers average 7.2x and the fair ratio sits at 15.7x.
That gap points to a rich earnings multiple relative to both the sector and the fair ratio that the market could move towards. This would matter if sentiment cooled or growth forecasts were revised. Does this premium reflect resilience in 5N Plus, or is it a valuation risk you are comfortable carrying?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on 5N Plus leaves you torn, use that tension as a prompt to move fast and test the story against the data yourself. Start with the balance between risk and upside by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond 5N Plus?
Do not stop with 5N Plus alone. Broaden your watchlist with fresh ideas that match your style, from value and income to sturdier balance sheets.
- Target stronger foundations by scanning companies with healthier finances and consistent fundamentals using this focused list of solid balance sheet and fundamentals (7 results).
- Hunt for value opportunities by reviewing a curated 5 high quality undervalued stocks that filters for quality as well as pricing appeal.
- Lock in potential income streams by assessing a hand picked set of 1 dividend fortresses that emphasise yield and resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com