
Regeneron (REGN) Stock May Be Underpriced Despite Its $1b Alliance Expansion
Regeneron Pharmaceuticals has had a mixed run, with the share price climbing over the longer haul yet slipping in recent weeks, which raises a simple question for anyone looking at the stock today. Do the current earnings of Regeneron support where the market is pricing the business now, or has sentiment moved further than the underlying profit story?
- Over the past 5 years the stock has delivered a gain of 34.4%, putting real weight on the question of whether that performance is adequately backed by the company’s earnings power.
- The expanded alliance with Sanofi brings Regeneron US$1b upfront and the potential for sizeable milestone payments, which can influence how investors think about future profitability and the earnings base that might justify today’s valuation.
- The analysts covering Regeneron Pharmaceuticals have run their own numbers. See what analysts think Regeneron Pharmaceuticals's shares could be worth.
The issue now is whether Regeneron’s current share price can be explained by its earnings when set against the Fair Ratio benchmark.
To see how Regeneron Pharmaceuticals stacks up against other earnings focused opportunities, it can help to compare it with companies screened for 27 high quality undervalued stocks.
Is Regeneron Pharmaceuticals Still Cheap on Earnings?
The P/E ratio tends to matter most for a profitable, established drug developer like Regeneron Pharmaceuticals, because earnings are a central driver of how holders get paid back over time.
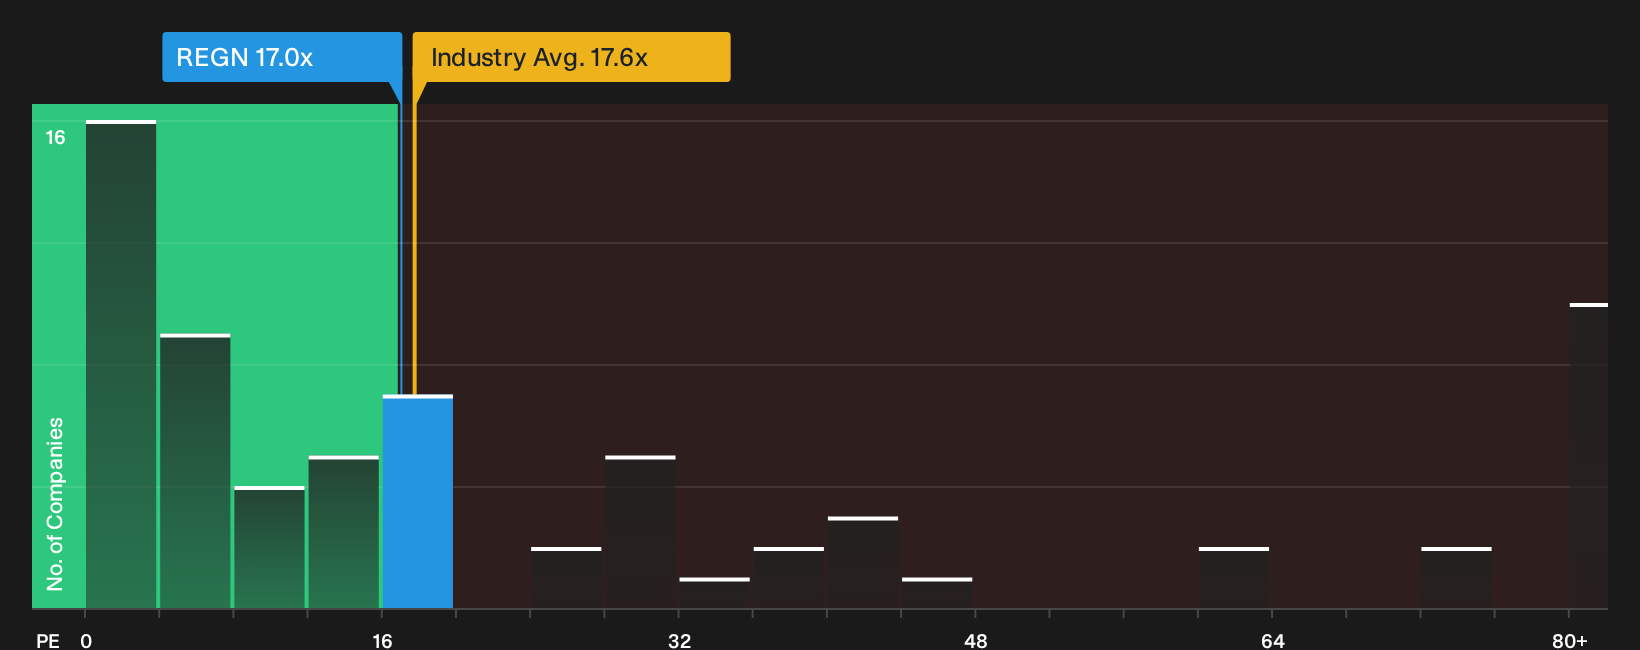
Right now the stock trades on a P/E of about 17.0x, which is very close to the Biotechs sector average of roughly 17.6x and well below the peer group on about 27.1x. Against a Fair Ratio benchmark that reflects Regeneron’s own mix of margins, growth profile, size and risk, the current multiple screens as undervalued rather than stretched. The recent expansion of the Sanofi alliance has sharpened focus on future antibody revenue streams. Even with that catalyst in the background, the earnings multiple still sits at a discount to what this framework suggests as a more typical level for the business. Explore the numbers behind Regeneron Pharmaceuticals's P/E valuation.
The Regeneron Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Regeneron Pharmaceuticals pick up where the P/E puzzle leaves off and explain what kind of growth, margins and earnings path would need to occur for the stock to be worth materially more or less than it is today, using the Community page as their home. Rather than rely on a single multiple or model output, each narrative lays out the assumptions behind its view of fair value so you can compare those inputs with actual results as they are reported.
Community views on Regeneron Pharmaceuticals split between those who see more upside in the pipeline and Sanofi profit share and those who worry current expectations already bake in a lot of that progress.
Bull case: 14% undervalued
"Current valuation implies the market is heavily discounting the durability of Dupixent, the conversion of the retinal business to EYLEA HD, and the potential from the late stage pipeline and expanded Sanofi collaboration..."
Discover why this Narrative puts Regeneron Pharmaceuticals at 14% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect Regeneron Pharmaceuticals to remain exposed to concentrated product risk as EYLEA faces biosimilar competition and Dupixent growth moderates against tougher comparisons in 2026..."
Explore why this Narrative puts Regeneron Pharmaceuticals at roughly fairly valued.
One more crucial piece for the Regeneron Pharmaceuticals puzzle
Everything so far has focused on what Regeneron Pharmaceuticals earns today, but Wall Street models sketch out where analysts think profit and cash generation could be a few years from now. This gives you another reference point alongside the current multiple. Explore where analysts expect Regeneron Pharmaceuticals to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com