
What KLA (KLAC)'s Revenue Outlook Means For Shareholders
- KLA reported June quarter revenue of US$3.658b and GAAP net income of US$1.363b, then guided fiscal Q1 2027 revenue to about US$4.0b, plus or minus US$200m.
- The guidance lift and management’s comments about accelerating momentum into late 2026 and 2027 describe rising demand for KLA’s process control and inspection tools.
- We will now look at how KLA’s raised near term revenue outlook and accelerating momentum interact with its broader investment narrative.
Scan beyond KLA and identify other chipmakers with similar momentum using our hand picked list of 90 AI infrastructure stocks.
KLA Investment Narrative Recap
To own KLA, you need to believe that demand for process control tools linked to AI, high bandwidth memory and advanced packaging keeps translating into orders from leading edge fabs. The raised fiscal Q1 2027 revenue guidance around US$4.0b points to healthy near term execution on that backlog, so the core operating thesis around tool intensity and mix does not materially change.
The key short term swing factor is how quickly KLA converts its roughly US$12.5b backlog into shipments without hitting supply bottlenecks or customer pushouts. The biggest current risk still sits around tariffs, elevated memory input costs and any renewed China equipment softness, which could pressure margins even if headline revenue tracks guidance.
The most relevant data point tied to this news is KLA’s updated guidance for the September quarter at US$3.8b to US$4.2b of revenue, following the June period where the company delivered US$3.658b of sales and US$1.363b of GAAP net income. That outlook implies management currently sees enough visibility in AI and advanced packaging related demand to support sequential top line expansion.
For you as an investor, that guidance interacts directly with the backlog and margin story. Converting higher shipments at roughly 62% gross margin guidance, while absorbing tariff and DRAM cost headwinds, is the execution test. Any slippage in China orders, advanced node spend or cost control would show up quickly against such a tightly defined revenue range.
KLA Long Term Assumptions and Valuation Context
KLA's narrative projects US$24.7b revenue and US$10.4b earnings by 2029. This assumes revenue grows by 22.1% per year and earnings rise by about US$5.6b from US$4.8b today.
Uncover why KLA's fair value indicates a 17% potential upside to its current price, a discount that could narrow quickly as sentiment catches up.
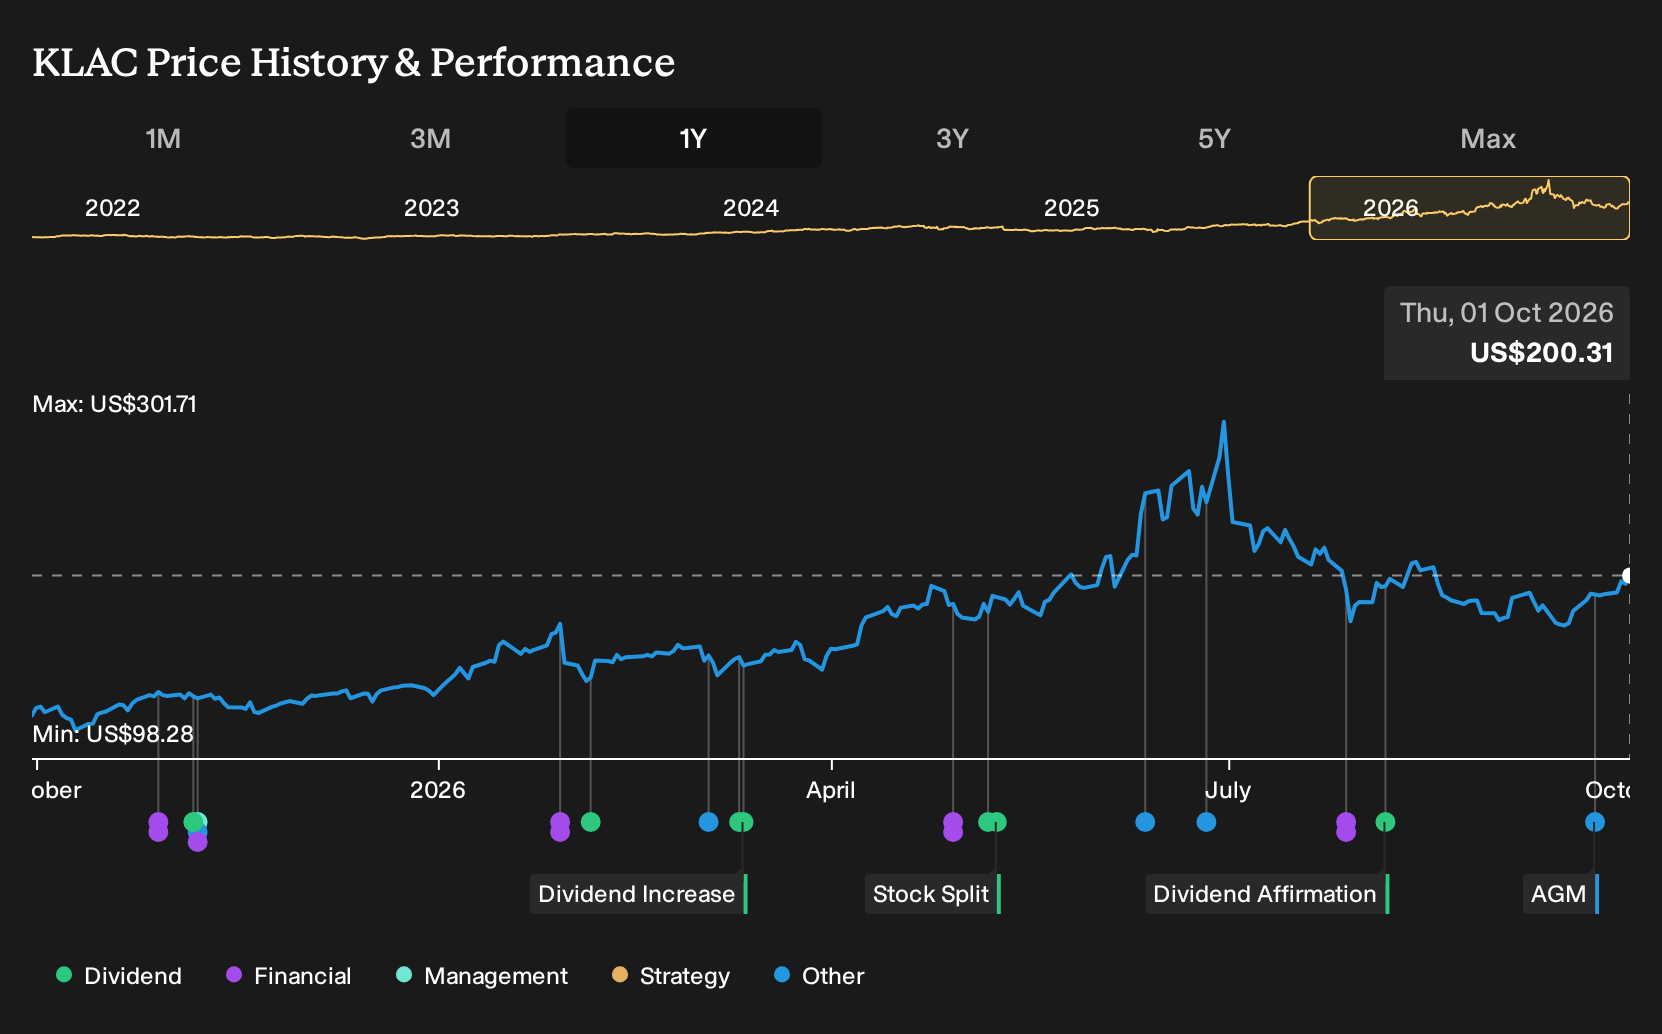
Exploring Other Perspectives
Some of the most optimistic analysts on KLA focus on advanced packaging as the big swing factor. Before this guidance, they were penciling in about US$26.1b of revenue and US$11.1b of earnings by 2029, versus consensus at US$24.7b and US$10.4b. Views like that are likely to be revisited as fresh numbers land.
Explore 5 other KLA fair value estimates, including one that suggests there could be as much as 52% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your KLA research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KLA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KLA's overall financial health at a glance.
Looking for more ideas beyond KLA?
Once you have a view on KLA, it can help to widen the lens and compare it with other opportunities that have different risk profiles, income potential, or balance sheet strength. The Simply Wall St Screener lets you do that quickly by filtering for the traits that matter most to you.
- If capital preservation ranks high for you, start with a basket of 31 resilient stocks with low risk scores that score well on resilience and downside protection.
- For investors hunting for mispriced quality, compare KLA with a 27 high quality undervalued stocks that combine robust fundamentals with more modest expectations baked into the price.
- If you want diversification into businesses the market may be overlooking, cast a wider net with a 19 high quality undiscovered gems that pair solid financials with far less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com