
Elite Canadian Dividend Stocks To Own In October 2026
Canadian dividend stocks are drawing fresh attention as global bond yields climb to multi decade highs and borrowing costs bite. Reliable cash payouts look especially appealing when bond markets swing and headlines focus on fiscal strains. Well covered dividends that clear a 3% yield hurdle and have a record of stability offer you a way to keep income flowing. This article highlights three such candidates from that group.
The three Canadian dividend stocks covered below are only a small sample, and the full screen surfaced 18 more companies with similarly compelling income stories that are not included here. To identify and analyze the higher conviction ideas that best fit your own portfolio, head straight to the Dividend Powerhouses (3%+ Yield) screener.
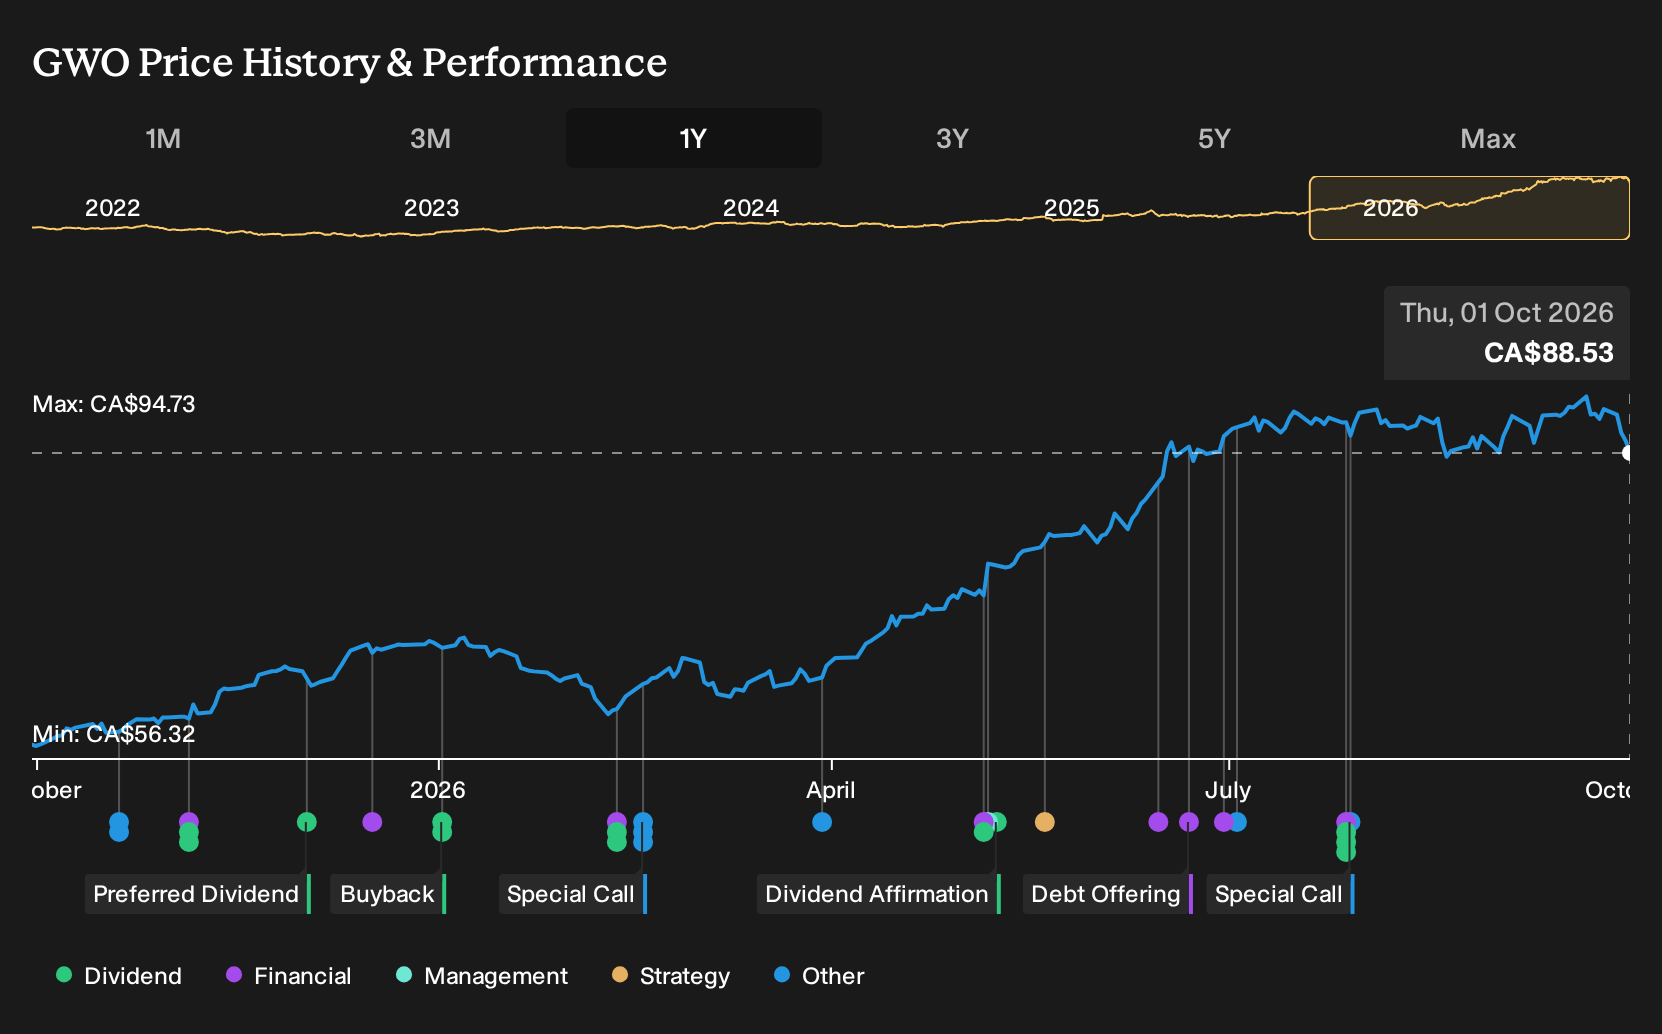
Great-West Lifeco (TSX:GWO)
Great-West Lifeco is a large insurer and retirement specialist whose life, annuity and workplace savings franchises supply the steady cash flows that support a 3%+ dividend profile. This is exactly what this income focused screen is built to surface.
Great-West Lifeco runs life and health insurance, retirement savings, wealth management and reinsurance businesses across Canada, the United States and Europe, anchored by Canada Life, Empower and Irish Life. Revenue is concentrated in Canada at about CA$12.4b, with CA$8.6b from Europe, CA$6.2b from the United States and CA$5.6b from Capital and Risk Solutions. The group is a large-cap insurer with a market value of roughly CA$80.5b.
"The company is shifting further toward capital light retirement and wealth businesses, which already account for a rising share of base earnings and show strong fee based revenue and operating leverage."
What happens to dividend headroom if that mix shift combines with a single pressure point on how new business is priced and written?
If that pressure point is what you are weighing, go straight to the full narrative for Great-West Lifeco to see how Great-West Lifeco’s mix shift could accelerate or stall dividend flexibility.
Sun Life Financial (TSX:SLF)
Sun Life Financial combines long established life and health insurance with asset management income that helps support the well covered 3%+ dividend this screener looks for, backed by recurring fees rather than one off windfalls.
Sun Life Financial runs insurance, health, wealth, and asset management operations worldwide, generating about CA$15.7b from Canada, CA$12.9b from the U.S., CA$7.7b from Sun Life Asset Management and CA$2.6b from Asia, with a market value near CA$61.8b.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources. This is reinforced by double-digit sales and CSM growth in the region year-over-year."
The real swing factor for that dividend friendly profile is how one pressure point in U.S. benefits earnings resolves over the next few years.
If that U.S. benefits pressure eases or even just stabilizes, the full narrative for Sun Life Financial explains how Sun Life Financial’s fee engine could accelerate the income story.

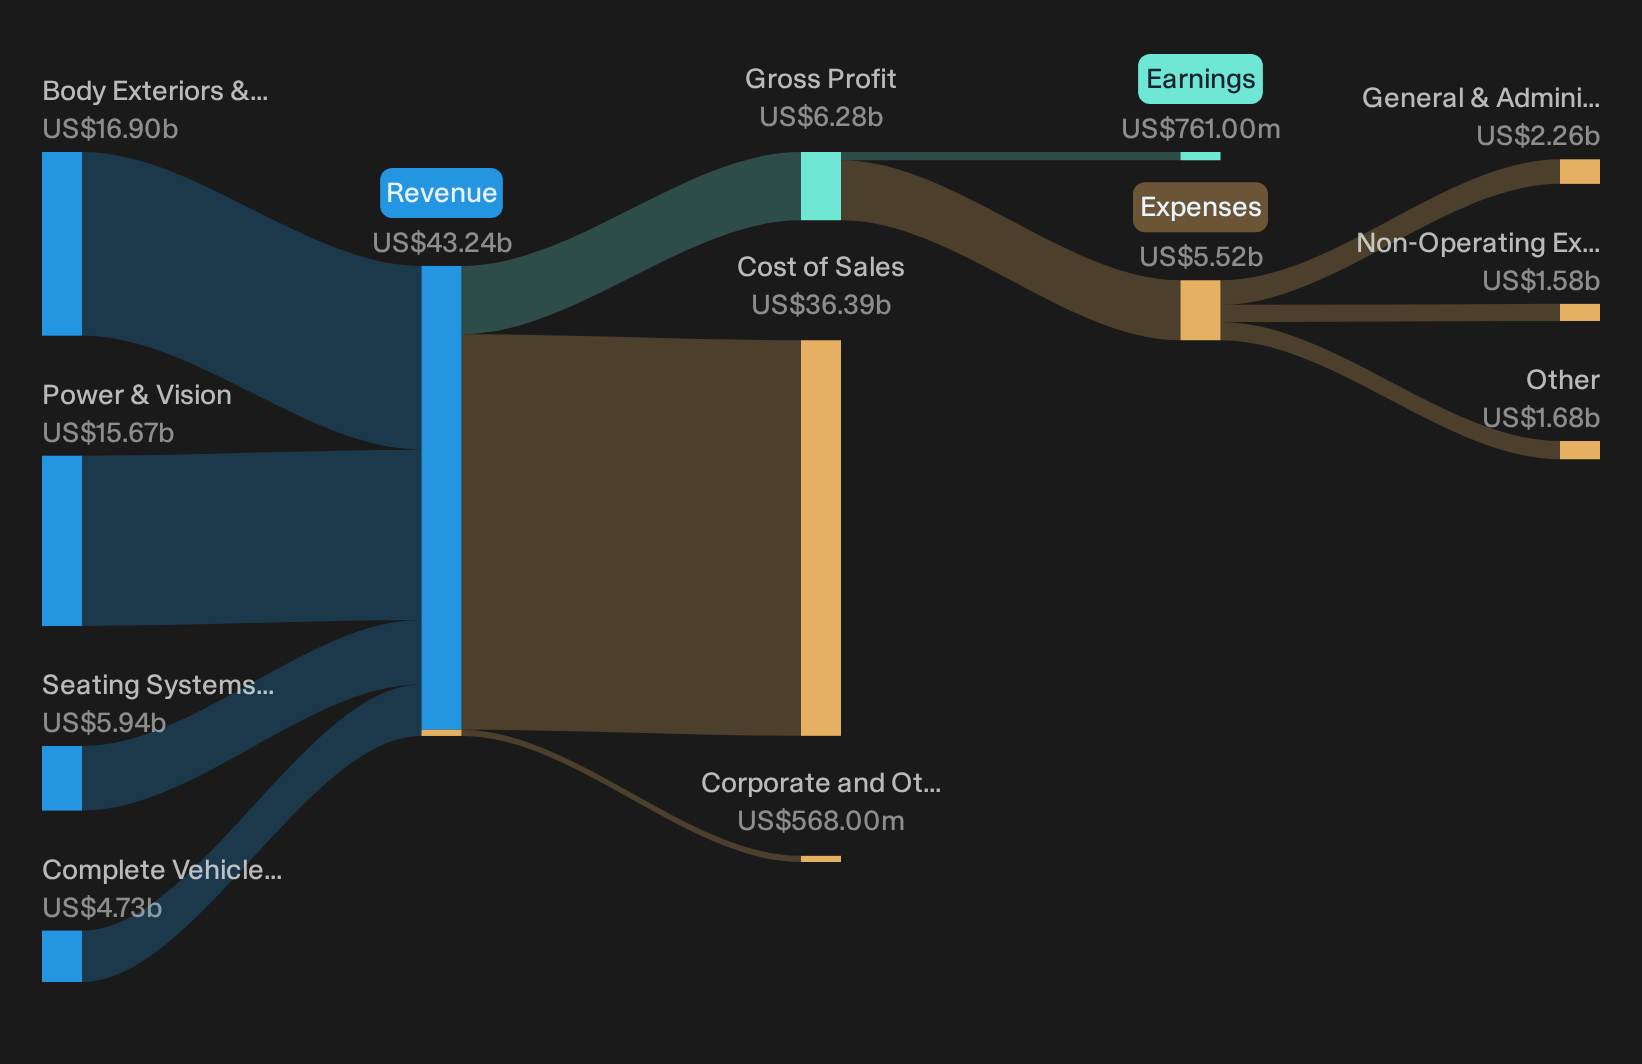
Magna International (TSX:MG)
Magna International supplies everything from body structures to seating and full vehicle assembly, with high volume Power & Vision and Body Exteriors & Structures products generating the predictable cash flows that underpin its 3%+ dividend profile. These operations anchor a business valued around CA$24.1b.
For dividend focused investors, Magna International offers a different angle on steady income, rooted in long running component programs that throw off cash even when auto cycles feel choppy.
"Magna International is focusing on operational excellence and restructuring actions, which are expected to result in meaningful margin expansion over the next two years."
A key consideration for that income story is how one less obvious cost pressure shapes the next stage of margin recovery.
That cost squeeze is exactly what the full narrative for Magna International unpacks, showing how Magna International’s margin reset could accelerate, stall, or quietly decouple from auto volumes.
Seeking Alternatives Before The Crowd
Fresh ideas tend to move first when momentum builds, while slower money may end up chasing prices that are already moving quickly. Scan under the radar for now and act with discipline.
- Target resilient income streams that can keep paying when headlines turn noisy by scanning the 1 dividend fortresses.
- Identify early-stage growth stories before they appear on widely followed watchlists by reviewing the 9 high quality undiscovered gems.
- Monitor structural demand in critical materials related to electrification by checking the 17 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com