
Israel Discount Bank (TASE:DSCT) Could Be 8% Undervalued As Class Action Advances
Class action approval puts Israel Discount Bank under closer scrutiny
Israel Discount Bank (TASE:DSCT) is back in focus after the Central District Court approved the management of a class action over interest on positive current account balances.
The case, centered on alleged unjust enrichment between April 2022 and May 2025, now covers customers who held sizeable positive balances and could influence how the bank handles everyday deposits.
Against this backdrop, Israel Discount Bank’s 90 day share price return of 15.31% and 1 year total shareholder return of 11.53% point to momentum that has been building over time, while the 3 year and 5 year total shareholder returns of 90.85% and 142.41% show how longer term holders have been rewarded despite short term legal uncertainty.
Compare how Israel Discount Bank’s legal overhang and recent returns stack up against a curated 222 resilient stocks with low risk scores that may offer a different balance between regulatory exposure and stability.
Israel Discount Bank has delivered sizeable long term returns while carrying a fresh legal cloud. The core question now is whether that mix of strength and scrutiny still comes at a reasonable price.
Most Popular Narrative: 8% Undervalued
Israel Discount Bank’s last close at ₪34.8 sits below the most followed fair value estimate of ₪37.99, which frames the current legal noise against a longer term earnings story built into that valuation.
Ongoing implementation of digital transformation and workflow automation projects (e.g., moving activities from branches to back office, use of AI in customer service) is expected to drive sustained efficiency gains, lower operating expenses, and improve net margins in upcoming quarters.
Ongoing integration of digital channels reflected in high customer satisfaction ratings for mobile and web platforms positions the bank to capture younger, tech-savvy customers, opening new revenue streams and supporting higher fee and commission income.
See why 2 investors see Israel Discount Bank as 8% undervalued.
The narrative’s fair value of ₪37.99 uses a 10.11% discount rate and assumes earnings growth backed by digital projects, cost control and a more efficient balance between fee income and lending, which together point to a business that the market narrative currently prices about 8.4% above where the shares trade.
Result: Fair Value of ₪37.99 (UNDERVALUED)
Still, the legal overhang around interest practices and the earnings hit from the CAL sale and related VAT ruling could both chip away at the current Israel Discount Bank narrative.
Find out about the key risks to this Israel Discount Bank narrative.
Another View: What Israel Discount Bank’s P/E Is Telling You
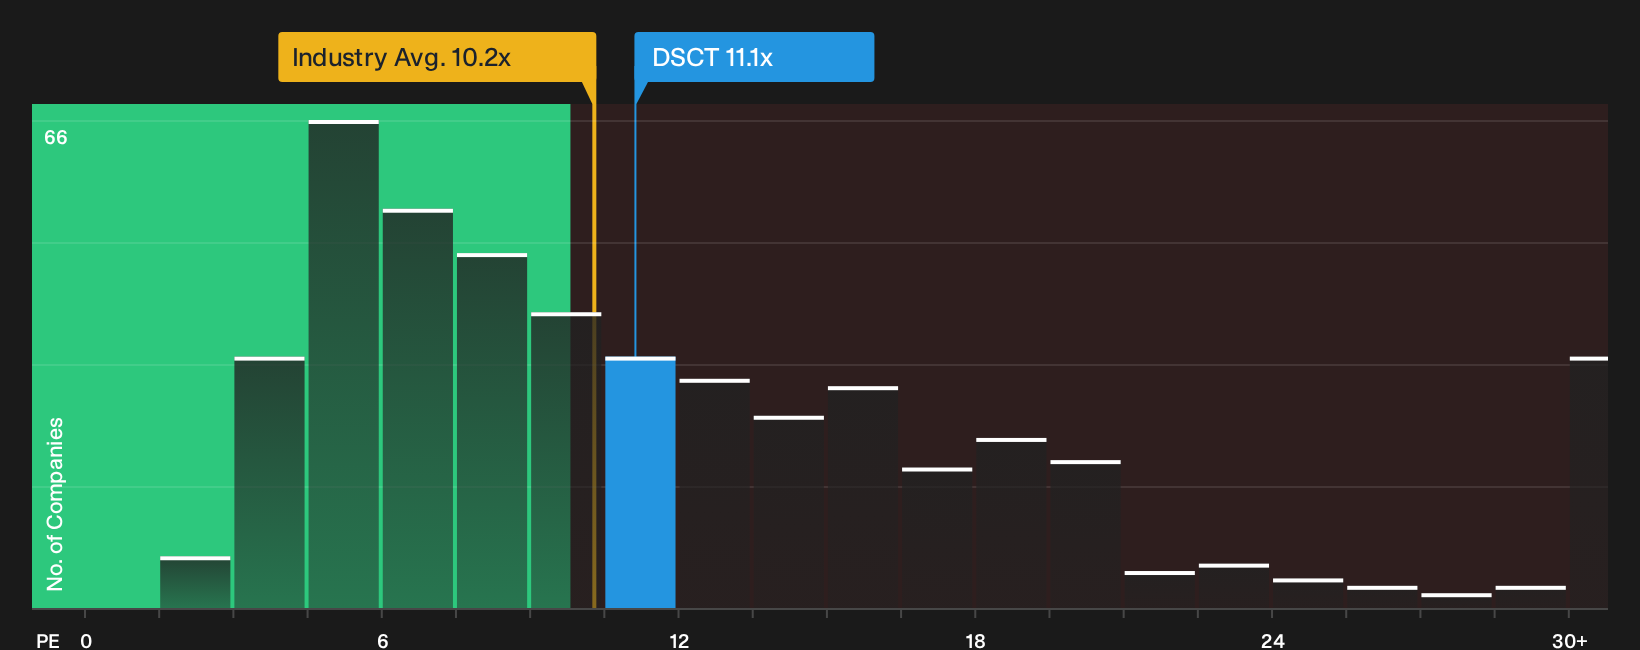
Israel Discount Bank looks inexpensive against its own fair value models, yet its 11.1x P/E is slightly higher than both peer averages at 10.7x and the Asian banks group at 10.2x, and close to a fair ratio of 11.3x, which leaves only a thin margin for error if sentiment turns.
That narrow gap between today’s P/E and the fair ratio raises a simple question for investors weighing the class action and earnings story: is this pricing cushion enough for your risk comfort level, or do you prefer more room for surprises, as shown in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of legal risk and valuation debate around Israel Discount Bank feels finely balanced, treat that as your cue to run the numbers yourself, weigh both sides of the story and see the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Israel Discount Bank?
If Israel Discount Bank has sharpened your focus on risk, return and valuation, now is the time to widen your watchlist using structured, data driven ideas.
- Explore potential opportunities in quality businesses that trade below estimated worth by scanning the 196 high quality undervalued stocks.
- Review the 157 dividend fortresses to identify securities that combine income potential with resilience.
- Filter for companies with sturdy finances by using the list of solid balance sheet and fundamentals (206 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com