
Frasers Property (SGX:TQ5) Could Be 64% Undervalued After Mitsubishi Estate Partnership
Frasers Property (SGX:TQ5) has teamed up with Mitsubishi Estate to overhaul Valley Point and Frasers Suites Singapore into a long-tenure mixed-use project, a move that puts a prime riverfront asset back in focus for investors.
Frasers Property’s recent announcement lands after a stretch where momentum has softened, with the share price down 13.27% year to date and the 90 day share price return declining 8.41%, even though the 3 year total shareholder return of 38.59% still paints a stronger longer term picture.
Scan how Frasers Property compares with other asset backed plays by reviewing the hand picked list of solid balance sheet and fundamentals (206 results) that investors are watching right now.
Frasers Property now trades well below both analyst targets and intrinsic value estimates. The real puzzle is how far that gap can reasonably close based on today’s cash flows and asset base.
Preferred P/E of 22.3x for Frasers Property: Is it justified?
On simple earnings terms, Frasers Property trades on a P/E of 22.3x, which places a clear valuation premium against both its sector and an internally estimated fair level for the multiple.
The P/E ratio compares the share price to earnings per share, so a higher figure usually signals that investors are willing to pay more today for every dollar of current profit. For a diversified real estate group with exposure across industrial, retail, residential and hospitality, that kind of premium often reflects expectations around asset quality, future project pipelines and the resilience of cash generation through cycles.
The current setup points to investors paying up relative to peers. The stock trades on a P/E of 22.3x, while the Singapore real estate industry sits closer to 13.4x, which is a much lower level. The internal fair P/E ratio estimate of 14.8x is also well below where the shares are priced today, suggesting the market is assigning a substantially richer multiple than the level the model indicates the valuation could move toward.
Explore the SWS fair ratio for Frasers Property.
Result: Price-to-earnings of 22.3x (OVERVALUED)
Still, that premium on Frasers Property can come under pressure if project cash flows are delayed or if broader real estate transaction volumes remain muted.
Find out about the key risks to this Frasers Property narrative.
Another View on Frasers Property’s Valuation
The P/E premium on Frasers Property tells only half the story. Our DCF model values the shares at S$2.73, while the stock trades at S$0.98, which implies a 64.1% discount to that future cash flow estimate.
The gap between a market price that low and a model value that high frames a very different question for investors. Is the market overreacting to weaker recent earnings and low 3.3% return on equity, or is the DCF too optimistic about what this real estate group can sustainably earn?
Look into how the SWS DCF model arrives at its fair value.
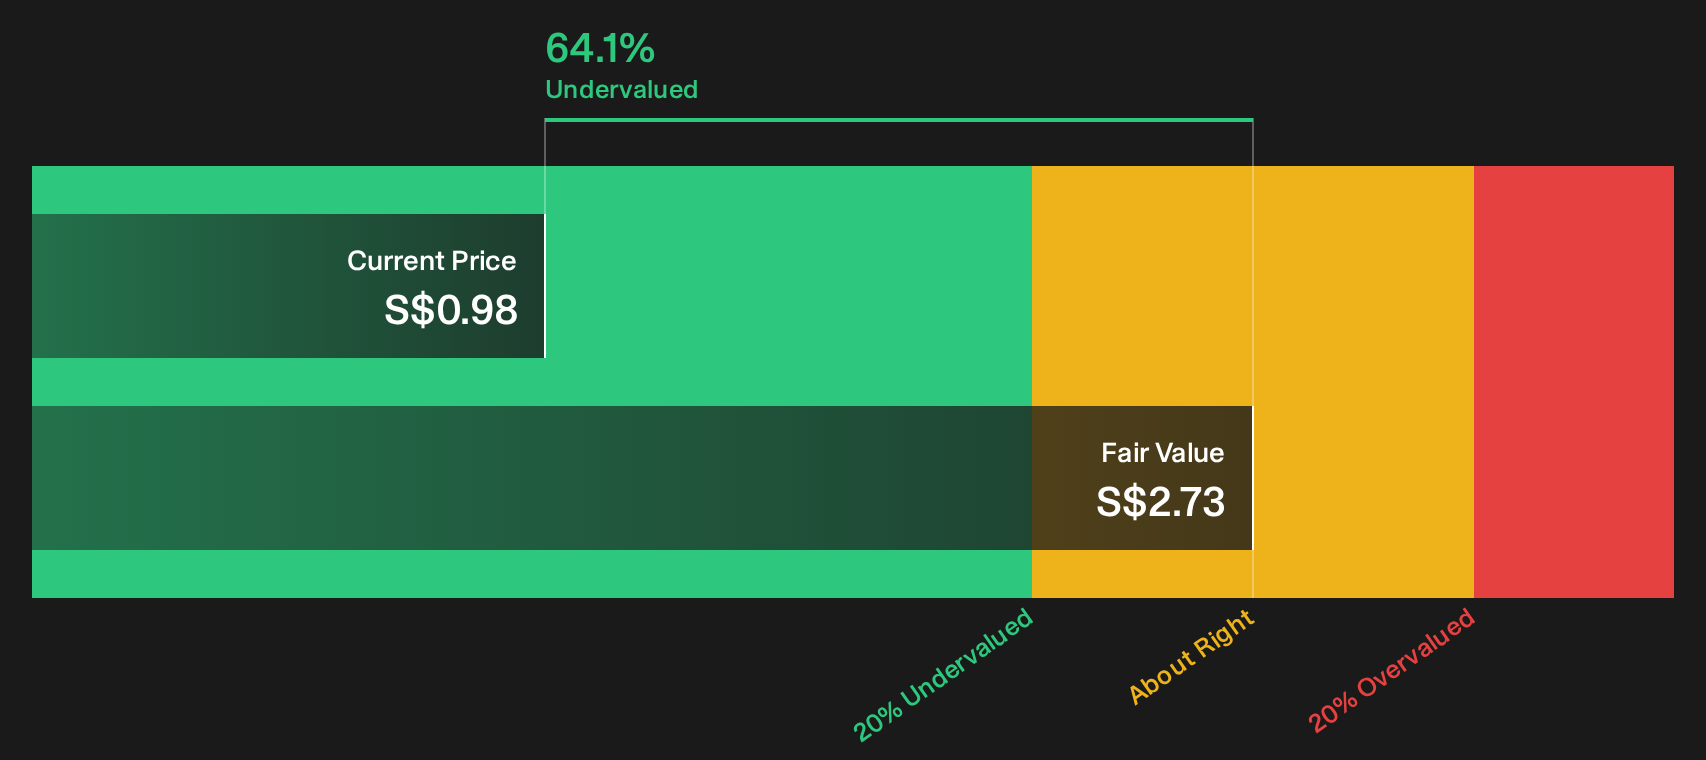
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Frasers Property for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Frasers Property’s valuation and quality can feel confusing, so move quickly, test the numbers yourself and weigh both sides of the story with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Frasers Property?
If you only stop at Frasers Property, you leave a lot of potential on the table. Cast a wider net and pressure test your next move.
- Target robust quality at a reasonable price by reviewing the 196 high quality undervalued stocks, which screens for strong fundamentals paired with appealing valuations.
- Strengthen your income stream by scanning the 157 dividend fortresses, which focuses on companies offering yields above 5% with an emphasis on resilience.
- Lower portfolio stress by filtering for the 222 resilient stocks with low risk scores, which highlights businesses with sturdier balance sheets and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com